Author: Christopher Arco

  • Why Self-Employed Need Alternative Loans to Qualify

    Why Self-Employed Need Alternative Loans to Qualify

    Alternative loans are specialized mortgage products that qualify self-employed borrowers based on actual cash flow rather than tax-reduced net income. The core problem is structural: mortgage underwriting prioritizes standardized, salary-based income that does not reflect how self-employed people actually earn and spend. A freelance designer pulling $180,000 in gross revenue may report $60,000 in taxable income after legitimate deductions. That gap is exactly why self-employed need alternative loans. Non-QM products like bank statement loans and DSCR loans exist to close that gap by reading your finances the way they actually work.

    Why traditional income verification fails self-employed borrowers

    Standard mortgage underwriting was built around the W-2 employee. The system works cleanly when a borrower has a single employer, a fixed salary, and a predictable pay stub. Self-employed borrowers do not fit that mold, and the friction is by design, not by accident.

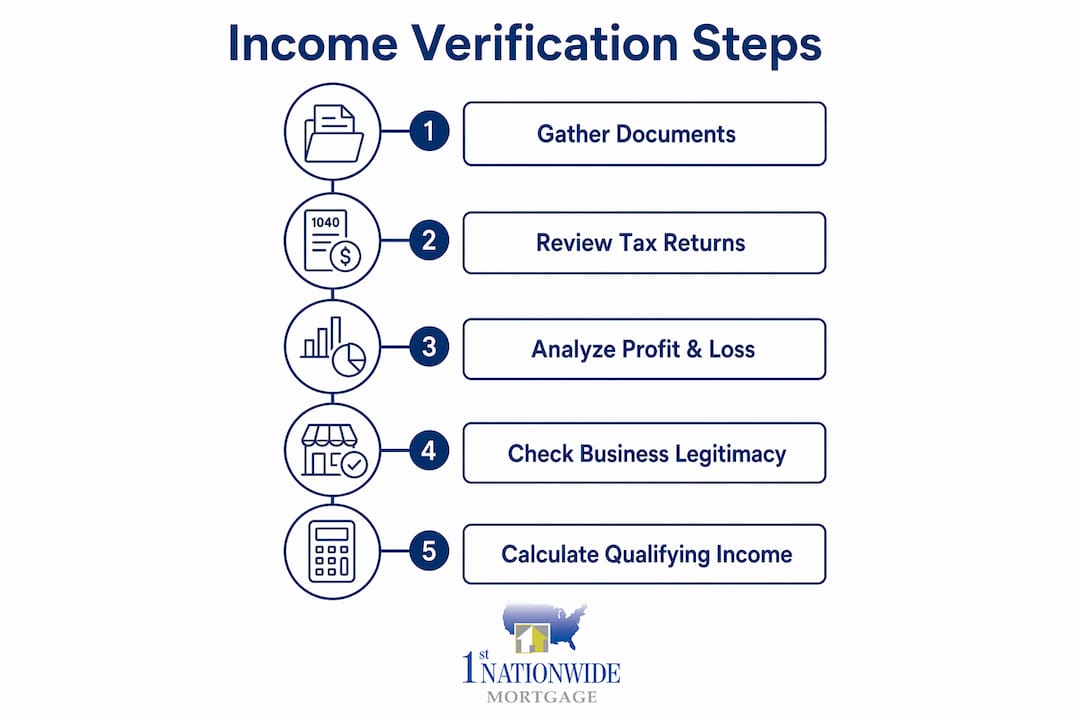
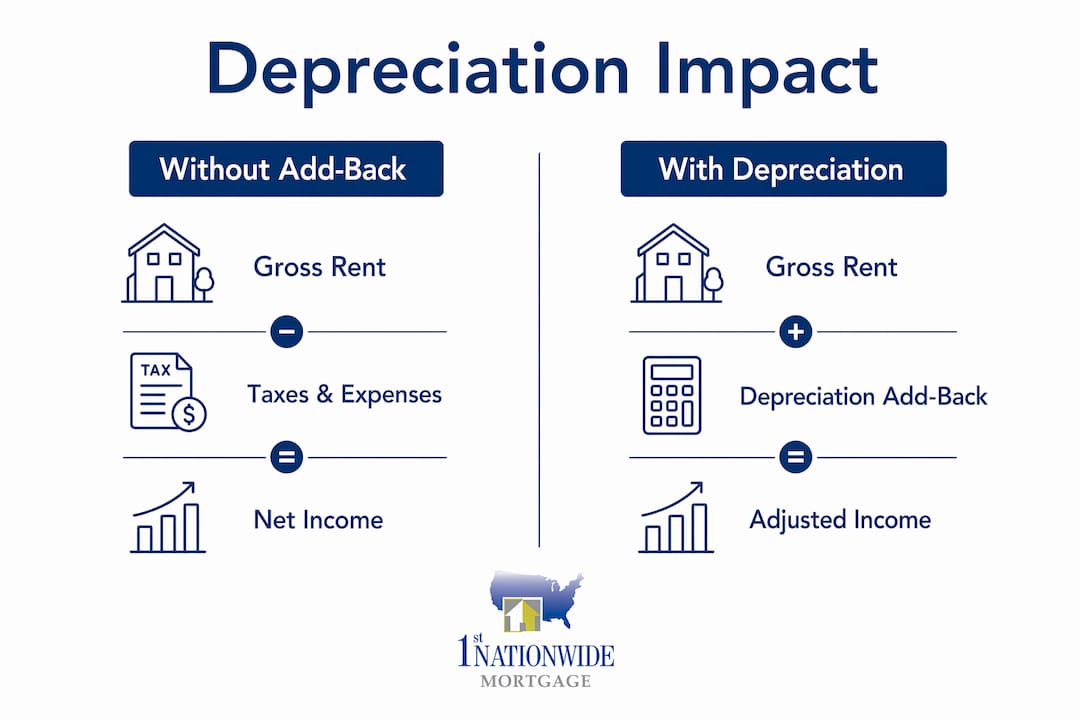
    Underwriters use two years of tax returns, including personal Form 1040s and business returns, to calculate qualifying income. They add back non-cash deductions like depreciation, but the net figure still reflects tax-optimized reporting rather than real cash flow. Income calculations average the two years or favor the most recent year if it shows an upward trend. That sounds fair until you realize most self-employed borrowers have intentionally minimized that number.

    The deeper issue is the deduction paradox. Aggressive tax deductions reduce qualifying income dollar for dollar, even when actual business cash flow and lifestyle spending are far higher. A borrower with $200,000 in gross revenue who writes off $130,000 in expenses has only $70,000 in qualifying income. That borrower is not struggling financially. The tax code is working exactly as intended. But the underwriting system reads that $70,000 and limits the loan accordingly.

    Self-employed income is also fragmented. Income verification gaps appear because self-employment income is spread across 1099 forms, profit and loss statements, tax returns, and bank records. Each document tells part of the story. No single form captures the full picture the way a W-2 does. Underwriters must reconcile all of them, and any inconsistency creates delays or denials.

    Common pitfalls self-employed applicants face include:

    • Declining income trend. If year two shows lower net income than year one, underwriters may use the lower figure or deny the application entirely.
    • Business age. Most conventional programs require at least two years of self-employment history, verified by tax returns and business licenses.
    • Commingled accounts. Mixing personal and business deposits in one account makes it harder to document income cleanly.
    • Large unexplained deposits. Underwriters flag irregular large deposits and require written explanations, slowing the process.

    Pro Tip: Before applying for any mortgage, ask your accountant to run a “qualifying income analysis” using your last two tax returns. This tells you exactly what an underwriter will see before you ever submit an application.

    Why self-employed borrowers need alternative financing options

    The case for alternative financing is not about borrowers with weak finances. It is about borrowers whose finances look weak on paper because the tax code rewards them for making them look that way. That is the central paradox driving demand for non-QM and alternative loan programs.

    Here is how the paradox plays out in practice:

    1. You earn strong gross revenue. Your business generates $250,000 per year in deposits.
    2. You deduct aggressively. Your accountant writes off $160,000 in legitimate business expenses, reducing taxable income to $90,000.
    3. You apply for a conventional loan. The underwriter calculates qualifying income at $90,000, which may not support the loan amount you need.
    4. You get denied or offered far less. The lender sees a borrower earning $90,000, not the business owner depositing $250,000.
    5. An alternative loan reads the deposits. A bank statement loan uses 12–24 months of deposits, applies an expense factor, and arrives at a qualifying income that reflects your actual cash flow.

    Alternative loan programs use bank statements, profit and loss statements, or rental income for qualification rather than tax returns. This flexible underwriting is not a loophole. It is a purpose-built solution for borrowers whose income is real but documented differently.

    The situations where conventional loans fail self-employed applicants are predictable. A consultant who incorporated two years ago, a freelancer with multiple income streams, a real estate investor whose personal income is minimal but whose properties cash flow well. All three have the financial capacity to repay a loan. None of them qualify cleanly under conventional guidelines.
    Hands exchanging loan documents in office

    Pro Tip: If you are planning to buy a home in the next 12–18 months, talk to a loan officer who specializes in self-employed mortgage qualification before you file your next tax return. The decisions you make on your return this year directly affect what you qualify for next year.

    What types of alternative loans work for self-employed borrowers?

    Several non-QM loan structures address the income documentation gap. Each one uses a different qualifying method, and the right choice depends on your business structure, credit profile, and financial goals.
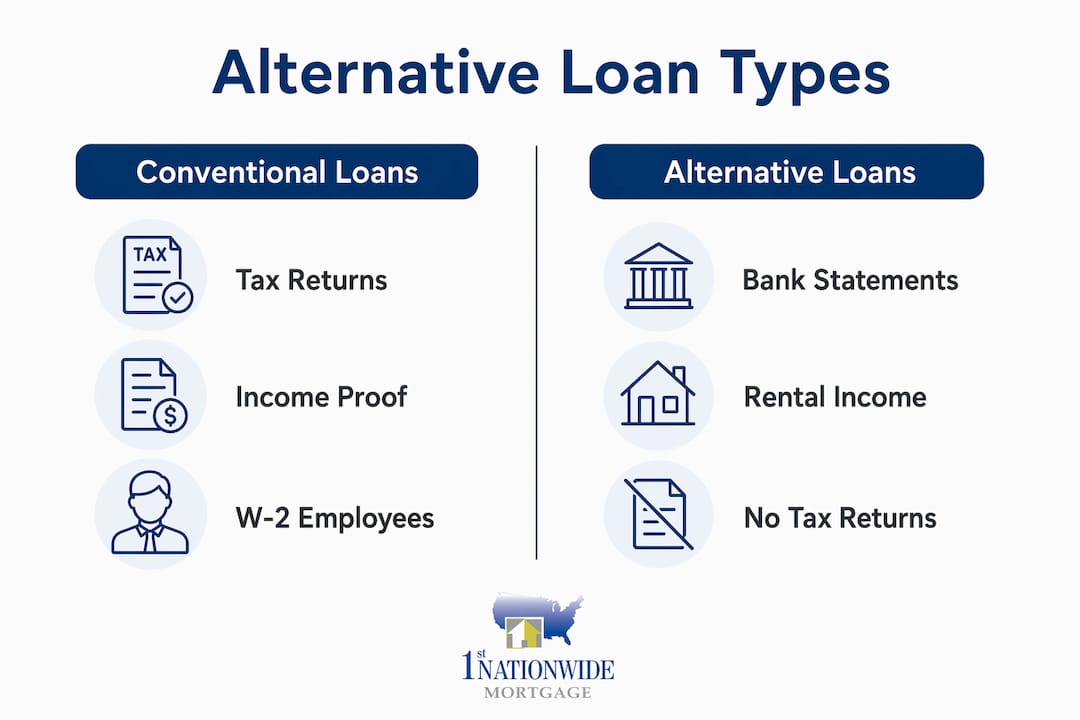
    Infographic comparing conventional and alternative loans

    Bank statement loans

    Bank statement loans qualify applicants based on 12–24 months of bank deposits rather than tax returns. The lender applies an expense factor to the total deposits to estimate net income. At 1st Nationwide Mortgage, the standard expense factor is 50% on business accounts. That factor drops to 35–40% when a CPA-certified profit and loss statement supports a lower expense ratio. The minimum credit score is 620, and down payments typically run 10–20%.

    This structure works well for consultants, freelancers, and small business owners who deposit consistently but write off heavily. The loan reads your bank account, not your tax return.

    DSCR loans

    DSCR loans allow qualification based on rental property cash flow, with no personal income verification required. The Debt-Service Coverage Ratio measures whether the property’s rental income covers its mortgage payment. A DSCR of 1.0 means the property breaks even. Some lenders accept a DSCR as low as 0.8 with strong credit. At 1st Nationwide Mortgage, DSCR loans work for LLCs, with no limit on the number of financed properties.

    This product is the primary tool for self-employed real estate investors who hold properties in business entities and have minimal personal income on paper.

    No income verification loans

    No income, no asset (NONI) loans require neither income documentation nor asset verification. These products serve foreign nationals and borrowers with no documentable income. They carry stricter equity and credit requirements to offset the documentation gap.

    Loan type Qualifying method Typical down payment Best for
    Bank statement loan 12–24 months of deposits 10–20% Freelancers, consultants, small business owners
    DSCR loan Rental property cash flow 20–25% Real estate investors, LLC borrowers
    NONI loan No income or asset docs 30%+ Foreign nationals, no-doc borrowers
    Conventional loan 2 years of tax returns 3–20% W-2 employees, salaried borrowers

    The key distinction across all alternative loan types is that they measure financial capacity differently. None of them ignore risk. They simply use a different lens to assess it.

    How to prepare and qualify for an alternative loan

    Preparation separates borrowers who close quickly from those who get stuck in documentation requests. The process is manageable when you know what lenders are looking for.

    • Organize 12–24 months of bank statements. Use separate business and personal accounts. Commingled accounts complicate the income calculation and raise flags.
    • Get a CPA-certified profit and loss statement. A certified P&L can lower the expense factor a lender applies to your deposits, which directly increases your qualifying income.
    • Reconcile your books before applying. Discrepancies between IRS-reported income and business bank statements are a leading cause of loan denial. Underwriters compare these documents closely, and mismatches trigger documentation requests or outright denials.
    • Check your credit score. Alternative loans typically require a minimum 620 credit score. A score above 700 gives you access to better pricing and lower down payment options.
    • Understand your debt-to-income ratio. Even with alternative income documentation, lenders calculate a debt-to-income ratio. Know your monthly obligations before you apply.
    • Consult a loan officer who specializes in non-QM lending. General mortgage brokers often lack the product knowledge to structure an alternative loan correctly. A specialist knows which program fits your income profile.

    Many self-employed borrowers mistakenly believe they must eliminate all tax deductions to qualify for a mortgage. Reducing discretionary write-offs in the one to two years before applying can increase qualifying income without losing all tax benefits. This nuanced approach preserves borrowing capacity while maintaining some tax savings.

    Pro Tip: Ask your lender how they verify self-employed income before you submit documents. Different lenders apply different expense factors and use different averaging methods. Knowing the formula in advance lets you present your financials in the most favorable, accurate light.

    Key Takeaways

    Self-employed borrowers need alternative loans because conventional underwriting reads tax-optimized income, not actual cash flow, making non-QM products the most direct path to qualification.

    Point Details
    Tax deductions create the gap Aggressive write-offs reduce qualifying income even when real cash flow is strong.
    Bank statement loans solve the core problem Lenders use 12–24 months of deposits, not tax returns, to calculate income.
    DSCR loans bypass personal income entirely Rental property cash flow qualifies the loan, making them ideal for investors.
    Clean documentation prevents denial Reconciled bank statements and tax returns reduce the risk of underwriter flags.
    Strategic deduction planning helps Reducing discretionary write-offs one to two years before applying raises qualifying income.

    What I have learned after years of working with self-employed borrowers

    The most common frustration I hear from self-employed borrowers is that they feel penalized for running their business well. They followed their accountant’s advice, minimized their tax bill, and then walked into a mortgage application expecting the same result a salaried colleague gets. The system surprised them.

    What I have found is that the problem is rarely the borrower’s finances. It is the mismatch between how the tax code rewards self-employment and how conventional underwriting measures it. These two systems were not designed to work together. Alternative loans exist precisely because that mismatch is structural, not situational.

    The borrowers who close successfully are the ones who plan ahead. They talk to a loan officer before they file their taxes, not after. They understand that the return they file in april shapes what they qualify for in september. That timing awareness is the single biggest advantage a self-employed borrower can have.

    One thing I push back on is the idea that alternative loans are a last resort. For a self-employed borrower with strong deposits and a solid credit profile, a bank statement loan is often the right loan, not a fallback. It reads your finances accurately. A conventional loan, in that situation, would actually misrepresent your capacity.

    The other misconception I see regularly is that non-QM means high risk. DSCR loans, for example, are underwritten on the property’s cash flow. That is a disciplined, asset-based qualification method. It is not looser than conventional underwriting. It is just different.

    — Chris Arco, NMLS #1281

    Alternative loan programs for self-employed borrowers at 1st Nationwide Mortgage

    Self-employed borrowers who have been turned away by conventional lenders often find that the right loan program was available all along. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, licensed in 18 states and rated BBB A+.
    https://1stnwm.com

    The bank statement loan program at 1st Nationwide Mortgage uses 12–24 months of deposits to calculate qualifying income, with expense factors as low as 35% when supported by a CPA-certified P&L. For real estate investors, the DSCR loan program qualifies based on rental property cash flow with no personal income documentation required. Use the mortgage calculators to run your numbers before you apply, or contact a loan specialist directly to review your income profile and identify the right program.

    FAQ

    What is a bank statement loan for self-employed borrowers?

    A bank statement loan qualifies borrowers using 12–24 months of bank deposits rather than tax returns. It is designed for self-employed individuals whose tax deductions reduce reported income below what conventional lenders accept.

    Why do tax deductions hurt mortgage qualification?

    Tax deductions reduce qualifying income dollar for dollar under conventional underwriting. A borrower with $200,000 in gross revenue and $130,000 in deductions qualifies on only $70,000 in income, regardless of actual cash flow.

    What credit score do I need for an alternative loan?

    Most bank statement and DSCR loan programs require a minimum 620 credit score. A score above 700 typically unlocks better rates and lower down payment requirements.

    Can I qualify for a mortgage without showing tax returns?

    Yes. Bank statement loans, DSCR loans, and NONI programs all offer no-tax-return mortgage options that use alternative documentation. The qualifying method depends on your income type and property goals.

    How do I avoid loan denial as a self-employed borrower?

    Reconcile your bank statements and tax returns before applying, since discrepancies between these documents are a leading cause of denial. A CPA-certified profit and loss statement and clean, separated business accounts significantly reduce underwriter friction.
  • Self-Certified Mortgage Explained: 2026 Complete Guide

    Self-Certified Mortgage Explained: 2026 Complete Guide

    A self-certified mortgage is a loan where the borrower declares their income without providing traditional documentation like tax returns or W-2s. True self-cert mortgages are now illegal for primary residences under the Dodd-Frank Act’s Ability-to-Repay rule, which took effect after the 2008 financial crisis. That legal shift matters if you are self-employed, a freelancer, or a real estate investor searching for flexible qualification options. The good news: legal alternatives like bank statement loans and DSCR loans now serve the same borrowers with real income verification and real buyer protections. Understanding what is a self-certified mortgage explained correctly means knowing both what existed and what replaced it.

    What is a self-certified mortgage, and why did it change?

    A self-certified mortgage, also called a stated income loan, let borrowers declare their income on a loan application with no third-party verification. Lenders accepted the number at face value. That approach worked for some borrowers with legitimate but hard-to-document income, but it created a serious systemic problem.

    Stated income loans became widespread before 2008 because they were fast and easy to originate. Lenders had little incentive to verify accuracy when rising home prices masked default risk. The result was a wave of inflated applications.

    About 30% of stated-income borrowers before the 2008 crisis overstated their income by more than 50%. That level of misrepresentation contributed directly to the mortgage meltdown and the foreclosures that followed.

    That statistic explains why regulators acted decisively. The Dodd-Frank Act, signed in 2010, introduced the Ability-to-Repay rule, which requires lenders to verify a borrower’s capacity to repay before approving any mortgage on a primary residence. The rule ended blind self-certification for most borrowers. Lenders who ignore it face legal liability and loan buyback risk. The term “liar loans,” which critics used to describe pre-crisis stated income products, reflects how badly the system was abused.

    What are the modern alternatives to self-certified mortgages?

    Professionals discussing mortgage regulations

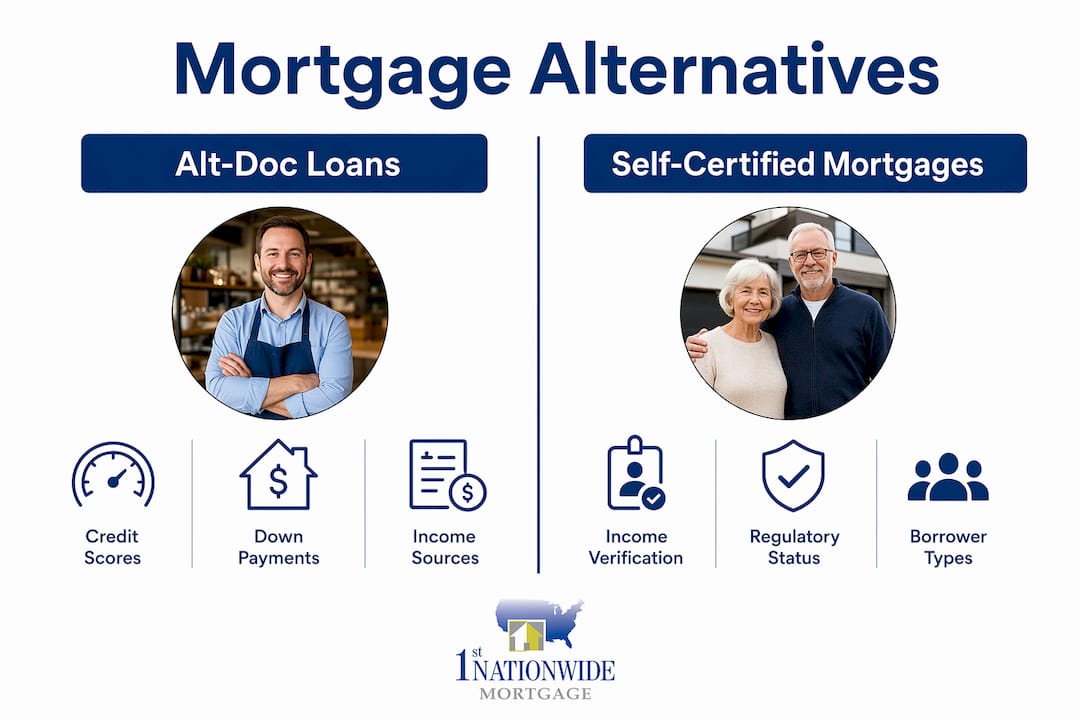
    The legal successors to self-cert mortgages are called alternative documentation loans, or Alt-Doc loans. They fall under the broader category of non-QM (non-qualified mortgage) products. These loans verify income, but they use sources other than tax returns.

    The most common types available in 2026 include:

    • Bank statement loans: Lenders review 12–24 months of personal or business bank deposits to calculate qualifying income. This works well for self-employed borrowers whose tax write-offs reduce their reported income below what conventional lenders accept.
    • Asset depletion loans: Lenders divide a borrower’s total liquid assets by the loan term to derive a monthly income figure. No employment required.
    • DSCR loans (Debt Service Coverage Ratio): Used for investment properties. The property’s rental income qualifies the loan, not the borrower’s personal income. This works for LLCs and investors with multiple financed properties.
    • NONI loans (No Income, No Asset): Designed for foreign nationals and borrowers with no documentable income in the U.S. system.

    Modern Alt-Doc loans carry regulated minimum credit scores around 620–660 and require higher down payments and cash reserves than conventional loans. That structure protects both the lender and the borrower. These products comply fully with Dodd-Frank because income is verified, just through a different method than a W-2 or tax return.

    Self-employed borrowers often underreport taxable income due to business deductions but may have strong actual cash flow. Alt-Doc loans are built precisely for that gap between reported income and real earnings.

    Infographic comparing alt-doc and self-certified mortgages

    How does self-certification work in practice today?

    True no-doc self-certification is illegal for primary residences under the Ability-to-Repay rule. What exists today is structured alternative verification, not a blank check for borrowers to state any number they choose.

    Here is how the process works for a bank statement loan, the most common Alt-Doc product:

    1. Submit 12–24 months of bank statements. Business accounts are standard. Personal accounts are accepted by some lenders.
    2. Lender applies an expense factor. The standard is 50% on business deposits. That means $20,000 in monthly deposits becomes $10,000 in qualifying income. A CPA-certified profit and loss statement can reduce that factor to 35–40%, increasing qualifying income.
    3. Lender calculates debt-to-income ratio. The derived income figure is used to measure how much of your monthly income goes toward debt payments.
    4. Credit and down payment review. Most bank statement programs require a minimum 620 credit score and 10–20% down.
    5. Underwriting and approval. The file goes through full underwriting, including property appraisal and title review.

    For investment properties, DSCR loans skip personal income entirely. The lender calculates whether the property’s rental income covers the mortgage payment. A DSCR of 1.0 means rent equals the payment. Most lenders prefer 1.1 or higher.

    Pro Tip: If you use a business bank account, keep personal and business expenses separate for at least 12 months before applying. Clean deposits with minimal non-business transactions make underwriting faster and your qualifying income higher.

    Investment properties and secondary homes face different standards than primary residences. Some limited no-doc structures remain available for those property types, but they require substantial down payments and carry higher interest rates. Borrowers who qualify for these products typically have significant equity or assets.

    What are the benefits and risks of alternative documentation mortgages?

    Alt-Doc loans solve a real problem for non-traditional income earners. They also carry trade-offs that borrowers must understand before committing.

    Factor Benefit Risk
    Qualification Accessible for self-employed, freelancers, and investors Stricter credit and reserve requirements than conventional loans
    Documentation No tax returns required Bank statements must show consistent, clean deposits
    Processing Fewer documents can mean faster review Underwriting is still thorough; errors delay closing
    Cost Access to homeownership otherwise unavailable Higher interest rates than conventional or FHA loans
    Property use Works for investment properties and primary residences No-doc loans are four times more likely to default than standard mortgages

    The higher default risk on no-doc products is not a coincidence. It reflects the reduced verification. That is why lenders price these loans with higher rates and require larger down payments. The rate premium compensates for the added uncertainty in the income picture.

    No-doc and low-doc loans carry higher interest rates and risk profiles than conventional loans. Borrowers must weigh the benefit of qualifying against the long-term cost of a higher rate. On a $400,000 loan, even a 1% rate difference adds up to tens of thousands of dollars over 30 years.

    Pro Tip: Build at least 6–12 months of mortgage payment reserves before applying for an Alt-Doc loan. Lenders require it, and it protects you if income dips after closing.

    The historic reputation of these products as “liar loans” is worth acknowledging directly. Modern Alt-Doc loans are not that. Bank statement loans involve active mathematical underwriting where lenders apply expense factors to deposits, versus old stated income loans that accepted unverifiable borrower claims. The safeguards are real.

    What are the typical self-certified mortgage requirements in 2026?

    Alt-Doc loan requirements vary by lender and loan type, but the following benchmarks apply across most programs in 2026.

    Credit score minimums:

    • Bank statement loans: 620 minimum, with better rates above 680
    • DSCR loans: typically 620–660 minimum
    • Asset depletion loans: often 680 or higher
    • Stated income products for self-employed borrowers commonly require 680 or higher with 20% or more down

    Down payment requirements:

    • Bank statement loans: 10–20% for primary residences
    • DSCR loans: typically 20–25%
    • No-doc or limited-doc products: often 30% or more

    Cash reserves:

    • Most Alt-Doc programs require 6–12 months of mortgage payments in liquid reserves after closing
    • DSCR loans may require additional reserves based on the number of financed properties

    Documentation typically required:

    • 12–24 months of business or personal bank statements
    • Proof of business ownership (business license, CPA letter, or articles of incorporation)
    • For DSCR loans: a signed lease or market rent analysis
    • Government-issued ID and property appraisal

    Eligible property types:

    • Primary residences: bank statement loans and asset depletion loans apply
    • Investment properties: DSCR loans are the primary tool
    • Secondary homes: most Alt-Doc programs apply with standard requirements

    Alternative-documentation loans are available for a wide range of property types, but the income verification method must match the property’s purpose. A DSCR loan on a primary residence, for example, is not a standard product. Matching the right loan type to your property and income situation is the first step toward a successful application.

    You can review a full breakdown of how these programs work for self-employed borrowers in this alternative income documentation guide from 1st Nationwide Mortgage.

    Key Takeaways

    Self-certified mortgages no longer exist in their original form. Legal Alt-Doc loans now verify income through bank statements, assets, or rental cash flow instead of tax returns.

    Point Details
    Self-cert loans are illegal for primary residences The Dodd-Frank Ability-to-Repay rule bans true no-doc mortgages on primary homes.
    Bank statement loans are the main alternative Lenders use 12–24 months of deposits with a 50% expense factor to calculate qualifying income.
    DSCR loans work for investors Rental income qualifies the loan; personal income is not required.
    Credit and reserves matter more here Most Alt-Doc programs require a 620+ credit score and 6–12 months of cash reserves.
    Higher rates reflect higher risk Alt-Doc loans cost more than conventional loans; borrowers must calculate the long-term trade-off.

    What I’ve learned from 15 years of Alt-Doc lending

    I have worked with hundreds of self-employed borrowers who came to me frustrated after being turned down by conventional lenders. The most common story: a business owner with $200,000 in annual deposits, a 720 credit score, and a tax return showing $40,000 in net income after deductions. Conventional underwriting sees $40,000. A bank statement loan sees the actual cash flow.

    What I want borrowers to understand is that the end of true self-certification was not a loss. The pre-2008 system was broken. Borrowers were approved for loans they could not afford, and the documentation that should have protected them was never collected. The foreclosure wave that followed hurt real families.

    The Alt-Doc products available today are genuinely better. They verify income through a different lens, but they verify it. That verification protects you as much as it protects the lender. If your income cannot support the payment under any reasonable calculation, you should not be in that loan.

    My honest advice: before you apply for any Alt-Doc product, run your own numbers. Add up 12 months of business deposits, cut them in half, and see if the resulting income figure supports the mortgage payment you are targeting. If it does, you are likely in good shape. If it does not, you may need a larger down payment, a less expensive property, or more time to build your deposit history.

    The self-employed mortgage qualification process is more transparent than most borrowers expect. The lenders who do this well are not looking for reasons to deny you. They are looking for a clear picture of your financial reality.

    — Chris Arco, NMLS #1281

    Alt-Doc mortgage programs at 1st Nationwide Mortgage

    1st Nationwide Mortgage is a direct mortgage banker, not a broker, licensed in 18 states and rated A+ by the BBB. For borrowers who cannot qualify through conventional income documentation, 1st Nationwide Mortgage offers bank statement loans, DSCR loans, and NONI programs built specifically for self-employed borrowers, freelancers, and real estate investors.

    https://1stnwm.com

    The bank statement loan program accepts 12 or 24 months of deposits and applies a structured expense factor to derive qualifying income, no tax returns required. The DSCR loan program qualifies investment properties based on rental cash flow, with no limit on the number of financed properties and full LLC eligibility. Use the mortgage calculators to estimate payments and run DSCR scenarios before you apply. When you are ready to talk through your specific situation, the team at 1st Nationwide Mortgage is available to walk you through which program fits your income profile.

    FAQ

    What is a self-certified mortgage in simple terms?

    A self-certified mortgage is a loan where the borrower states their income without providing tax returns or pay stubs. True self-cert loans are now illegal for primary residences in the U.S. under the Dodd-Frank Act.

    Are self-certified mortgages still available in 2026?

    True no-doc self-cert mortgages are not available for primary residences. Legal alternatives like bank statement loans and DSCR loans serve the same borrowers with compliant income verification methods.

    Who qualifies for an alternative documentation mortgage?

    Self-employed borrowers, freelancers, gig workers, and real estate investors with non-traditional income are the primary candidates. Most programs require a minimum 620 credit score and 10–25% down.

    How does a bank statement loan verify income?

    Lenders review 12–24 months of bank deposits and apply a 50% expense factor to calculate net qualifying income. A CPA-certified profit and loss statement can reduce that factor to 35–40%.

    What is the difference between a DSCR loan and a bank statement loan?

    A bank statement loan uses the borrower’s personal or business deposits to qualify. A DSCR loan uses the investment property’s rental income to qualify, with no personal income documentation required.

  • Mortgage Pre-Qualification Explained for Homebuyers

    Mortgage Pre-Qualification Explained for Homebuyers

    Mortgage pre-qualification is defined as a lender’s early estimate of how much you may be able to borrow, based on financial information you provide without formal document verification. This estimate gives you a working budget before you start house hunting, and it does not trigger a Loan Estimate under federal TRID regulations because no property address or verified documentation is involved. Pre-qualification differs from pre-approval, which requires a hard credit pull, income documentation, and underwriting analysis. Knowing the difference between these two steps protects you from overestimating your buying power and helps you move through the homebuying process with realistic expectations.

    How does mortgage pre-qualification work?

    Pre-qualification is built almost entirely on information you supply. You tell a lender your estimated income, monthly debts, and available assets. The lender uses those figures, along with general debt-to-income ratio guidelines, to produce a rough loan amount estimate. No appraisal, no underwriting review, and no hard credit pull occur at this stage.

    Mortgage banker reviewing client financial documents

    Because the process relies on self-reported data, the estimate is only as accurate as the numbers you provide. If you underestimate your monthly debt obligations or overstate your income, the resulting figure will be off. Lenders treat pre-qualification as a directional opinion, not a financial commitment. The informal nature of pre-qualification means no regulatory disclosures are required, unlike the formal Loan Estimate triggered later in the process.

    What lenders typically ask for during pre-qualification:

    • Gross monthly income: Your salary, self-employment income, or rental income before taxes
    • Monthly debt payments: Car loans, student loans, credit card minimums, and other recurring obligations
    • Estimated assets: Savings, checking, and retirement account balances
    • Desired loan amount or purchase price range: Helps the lender frame the estimate
    • Credit score range: Sometimes requested, though usually not verified at this stage

    Pro Tip: Ask your lender directly whether they ran a soft credit check or used only self-reported figures. Some lenders pull a soft inquiry during pre-qualification, which gives a more accurate picture without affecting your credit score.

    What is the difference between pre-qualification and pre-approval?

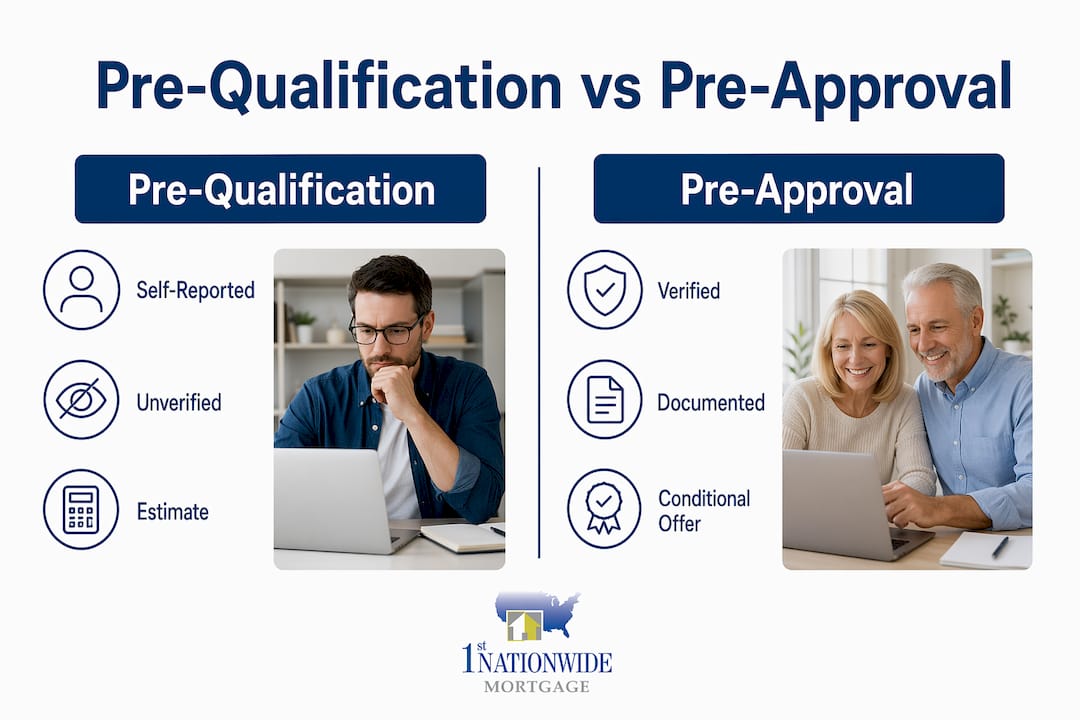
    Pre-qualification is informal and unverified. Pre-approval is documented, verified, and far closer to a conditional loan commitment. The distinction matters because sellers typically prefer pre-approval letters over pre-qualification letters when evaluating offers. A pre-qualification letter signals interest. A pre-approval letter signals financial credibility.

    Pre-approval requires you to submit pay stubs, W-2s, tax returns, bank statements, and authorization for a hard credit pull. The lender’s underwriting team reviews those documents and issues a letter specifying a loan amount, loan type, and conditions. Even then, pre-approval remains conditional, subject to a satisfactory appraisal, title search, and final underwriting sign-off before closing.

    The table below summarizes the core differences:

    Feature Pre-qualification Pre-approval
    Data source Self-reported by borrower Verified documents submitted
    Credit check Usually none or soft inquiry Hard credit pull required
    Income verification None Pay stubs, W-2s, tax returns
    Lender commitment None Conditional commitment
    Seller perception Weak signal Strong signal of readiness
    TRID Loan Estimate Not triggered May be triggered
    Typical use Budget planning Making serious purchase offers

    Infographic comparing pre-qualification and pre-approval

    One practical point worth understanding: mortgage industry experts note that lenders sometimes use “pre-qualification” and “pre-approval” interchangeably, which creates real confusion for buyers. Always ask your lender exactly what data they reviewed and whether any verification occurred. That single question tells you which category your letter actually falls into.

    For self-employed borrowers, the gap between pre-qualification and pre-approval is especially significant. Standard income documentation may not reflect actual earnings. Understanding self-employed mortgage qualification early helps you prepare the right documents before moving to pre-approval.

    What are the benefits and limitations of mortgage pre-qualification?

    Pre-qualification delivers real value when used correctly. Its primary benefit is early budget clarity. Knowing your approximate price range before you tour homes prevents you from falling in love with a property you cannot finance. It also opens a productive conversation with a loan officer about your financial profile and what steps to take before applying formally.

    Additional benefits include:

    • No credit score impact: Pre-qualification does not affect your credit score since it typically skips the hard credit inquiry.
    • Fast turnaround: You can often get a pre-qualification estimate the same day, sometimes within minutes online.
    • Financial gap identification: A lender may flag a debt-to-income ratio that is too high or a credit score range that needs improvement before you apply.
    • Lender comparison: You can speak with multiple lenders during pre-qualification without the credit impact that comes from multiple hard pulls.

    The limitations are equally real. A pre-qualification letter carries no evidentiary weight with most sellers in a competitive market. It does not guarantee you will qualify for the loan amount stated. If your self-reported income was higher than what your tax returns show, the estimate will not survive the pre-approval process.

    The most common misconception is treating a pre-qualification letter as a firm loan offer. It is not. Misinterpreting pre-qualification as a guarantee leads buyers to pursue homes outside their real financial reach, which wastes time and risks failed offers.

    Pro Tip: Before you start touring homes, ask your lender what it would take to move from pre-qualification to pre-approval. That conversation reveals exactly what documents you need and how long the process will take.

    How do you get pre-qualified for a mortgage?

    Getting pre-qualified is straightforward. You can do it by phone, through an online form, or in person with a loan officer. The entire process typically takes less than an hour. Here is what to expect, step by step:

    1. Gather your financial information. Pull together your estimated gross monthly income, a list of monthly debt payments, and approximate balances in your savings and checking accounts. You do not need official documents yet, but having accurate numbers matters.

    2. Choose how to connect with a lender. Online pre-qualification forms are fast and available around the clock. Phone conversations with a loan officer give you the chance to ask questions in real time. In-person meetings work well if you have a complex financial picture.

    3. Provide your information. The lender will ask about income, debts, assets, and sometimes your estimated credit score range. Answer as accurately as possible. Inflated numbers produce an inflated estimate that will not hold up later.

    4. Receive your estimate. The lender returns a loan amount range or maximum purchase price based on your inputs. This figure reflects standard debt-to-income ratio thresholds and general credit guidelines, not a verified review of your finances.

    5. Ask clarifying questions. Find out whether a soft credit check was run, what loan programs you may qualify for, and what the next steps toward pre-approval look like. Understanding what lenders verify during pre-approval helps you prepare now.

    6. Use the estimate to set your budget. Shop for homes within a price range that gives you a comfortable cushion below the maximum estimate. This protects you if your verified income or credit comes in slightly lower during pre-approval.

    The 100% of final loan underwriting only happens after you identify a property and go under contract. Pre-qualification is the starting line, not the finish line.

    Key Takeaways

    Mortgage pre-qualification is an unverified, self-reported estimate that sets your budget but carries no lender commitment and holds little weight with sellers compared to pre-approval.

    Point Details
    Pre-qualification is unverified Estimates rely on self-reported data with no document review or hard credit pull.
    Pre-approval carries more weight Sellers and agents treat pre-approval as proof of financing readiness.
    No credit score impact Pre-qualification skips the hard inquiry, so your score stays intact.
    Accuracy depends on you Inflated income or understated debts produce an estimate that will not survive pre-approval.
    Use it as a starting point Pre-qualification sets your budget; pre-approval is required before making serious offers.

    What I’ve learned after years of watching buyers misread pre-qualification

    Most buyers I work with come in thinking their pre-qualification letter is nearly as good as a loan approval. It is not, and that misunderstanding costs people real opportunities in competitive markets.

    Pre-qualification is a conversation, not a commitment. I have seen buyers tour homes at the top of their pre-qualification range, fall in love with a property, and then discover during pre-approval that their actual qualifying income was lower because of tax write-offs or undisclosed debts. That gap between expectation and reality is painful and avoidable.

    My honest advice: treat pre-qualification as a diagnostic tool. Use it to identify what needs to improve before you apply formally. If your debt-to-income ratio is too high, you now know to pay down a loan. If your credit score range is borderline, you have time to address it. The borrowers who move smoothly from pre-qualification to pre-approval are the ones who used the pre-qualification conversation to ask hard questions, not just collect a number.

    The right time to move from pre-qualification to pre-approval is before you make your first serious offer. Not after you find the house you want. By then, you are racing the clock.

    — Chris Arco, NMLS #1281

    Ready to move from estimate to approval with 1st Nationwide Mortgage?

    Pre-qualification gives you a starting number. 1st Nationwide Mortgage helps you turn that number into a real loan.

    https://1stnwm.com

    Use the mortgage calculators at 1st Nationwide Mortgage to run your own affordability estimates before you speak with a loan officer. When you are ready to take the next step, the team at 1st Nationwide Mortgage reviews your full financial picture and matches you with the right program. Whether you need a conventional loan, a bank statement mortgage for self-employment income, or a DSCR loan for an investment property, 1st Nationwide Mortgage works directly as a lender, not a broker, across 18 licensed states. Explore the full range of loan programs and connect with a loan officer who can walk you from pre-qualification to closing.

    FAQ

    What is mortgage pre-qualification?

    Mortgage pre-qualification is a lender’s informal estimate of how much you may be able to borrow, based on self-reported income, debts, and assets without document verification or a hard credit pull.

    Does pre-qualification hurt your credit score?

    Pre-qualification typically does not affect your credit score because it does not involve a hard credit inquiry. Credit inquiries for mortgage lending grouped within a 45-day window minimize score impact if you later apply with multiple lenders.

    How long does mortgage pre-qualification take?

    Pre-qualification usually takes less than an hour and can be completed online, by phone, or in person. You receive a loan amount estimate the same day in most cases.

    Can I make an offer on a home with only a pre-qualification letter?

    You can submit an offer, but sellers generally prefer pre-approval letters because pre-approval involves verified income and credit. In competitive markets, a pre-qualification letter alone may not be enough to have your offer taken seriously.

    What documents do I need for mortgage pre-qualification?

    Pre-qualification typically requires no official documents. You provide estimated figures for income, monthly debts, and assets. Preparing accurate numbers in advance produces a more reliable estimate and speeds up the move to pre-approval.

  • How Lenders Assess Seasonal Freelance Income

    How Lenders Assess Seasonal Freelance Income

    Lenders assess seasonal freelance income by requiring a minimum two-year documented history, then averaging net profit after specific expense adjustments to determine a stable qualifying figure. This process, formally called self-employed income analysis, goes far beyond simply adding up your deposits. Underwriters apply Fannie Mae guidelines, cash flow worksheets, and expense factors to arrive at a number that reflects what you can reliably repay, not what your best month looked like. If you earn as a photographer, landscaper, tax preparer, or any other seasonal freelancer, knowing this process before you apply changes everything.

    How lenders assess seasonal freelance income: the two-year rule

    The two-year minimum is the single most important threshold in seasonal income underwriting. Without at least 24 months of documented earnings, lenders exclude that income from qualification entirely. This applies across conventional, FHA, VA, and most non-agency loan programs.

    The logic behind this rule is straightforward. A single year of freelance income could be a fluke, a windfall project, or a business that has not yet proven it can survive an off-season. Two years of tax returns show a pattern. They reveal whether your income is growing, shrinking, or holding steady across multiple seasonal cycles.

    What happens if you have less than two years of history? Your options narrow, but they do not disappear:

    • Less than one year: Income is almost always excluded from conventional qualification.
    • One to two years: Some lenders may consider it with strong compensating factors, such as a high credit score, large reserves, or a low debt-to-income ratio.
    • Alternative programs: Bank statement loans analyze 12–24 months of deposits instead of tax returns, making them a practical path for newer freelancers.

    Pro Tip: Start building your paper trail the moment you go freelance. Open a dedicated business bank account, file Schedule C every year, and keep your tax returns organized. Every month of documented history you accumulate now is a month closer to conventional qualification.

    How do lenders calculate qualifying income from seasonal earnings?

    Gross revenue is not qualifying income. Lenders focus on net profit after deductions, then make specific adjustments to reflect your actual cash flow. The calculation follows a defined sequence.

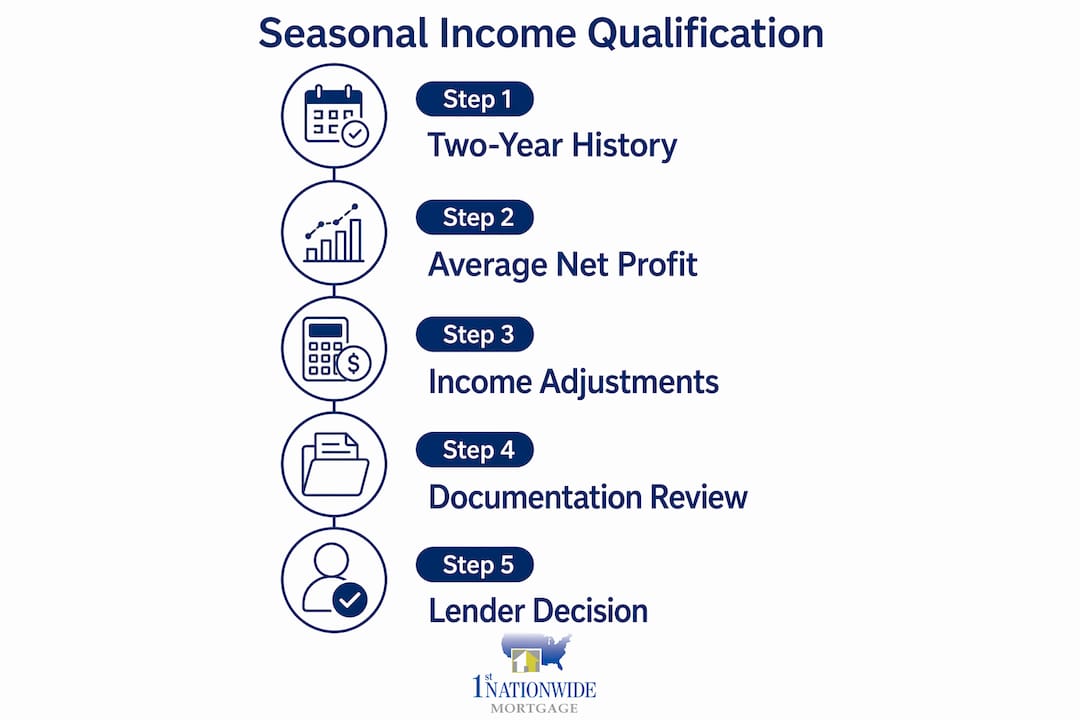
    1. Pull two years of Schedule C (or business tax returns). The underwriter starts with your net profit from IRS Form 1040 Schedule C for each of the past two years.
    2. Add back non-cash deductions. Depreciation and amortization are added back because they reduce taxable income without actually reducing your cash. The same applies to one-time business losses that will not recur.
    3. Subtract non-recurring income. A single large contract that inflated one year’s earnings gets removed. Lenders want income you can replicate.
    4. Average the two years. The adjusted figures from both years are added together and divided by 24 to produce a monthly qualifying income figure.
    5. Apply Fannie Mae Form 1084. This cash flow analysis worksheet standardizes the calculation across conventional loans, reducing underwriter discretion and making the process predictable.

    The result can be significantly lower than your gross deposits, which surprises many freelancers. A photographer who deposited $120,000 last year but wrote off $60,000 in equipment, travel, and software may qualify on only $50,000 or less after the full adjustment process.

    Income type How lenders treat it
    Net profit (Schedule C) Primary qualifying figure after adjustments
    Depreciation Added back to net profit
    Non-recurring income Subtracted from qualifying total
    Gross deposits (bank statement loan) Reduced by 50% expense factor, or 35–40% with CPA-certified P&L

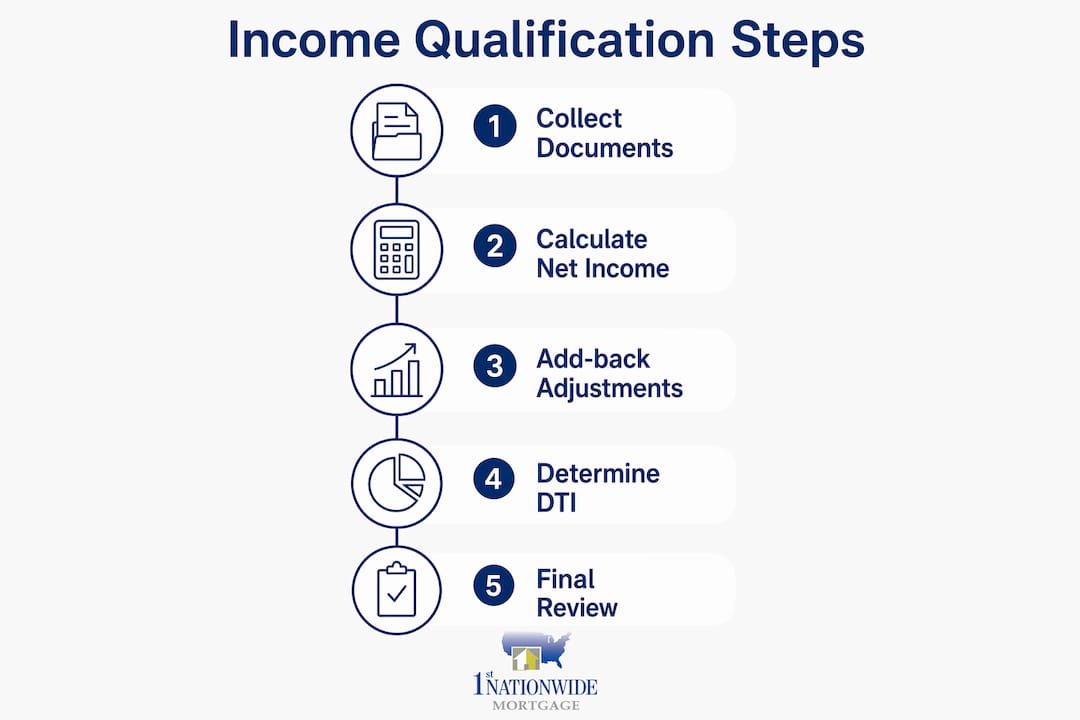
    Infographic showing steps to qualify seasonal freelance income

    Pro Tip: Work with a CPA who understands mortgage qualification before you file your taxes. A CPA-prepared profit and loss statement can lower the expense factor on a bank statement loan from 50% to as low as 35%, which meaningfully increases your qualifying income.

    What income stability signals do lenders look for?

    Stability is the word underwriters use most when evaluating seasonal freelancers. Predictable recurring annual cycles signal a viable business. Sporadic or irregular patterns signal risk.

    Hands pointing at income graphs in client meeting

    The distinction matters in practice. A landscaper who earns $80,000 every spring and summer, then earns little in winter, demonstrates a predictable cycle. An underwriter can see that pattern repeat across two years and treat it as stable. A freelancer who earned $90,000 one year from a single large client, then $30,000 the next, presents a very different picture.

    The most critical stability threshold is the year-over-year income decline rule:

    • An income decline greater than 20% year-over-year may disqualify the borrower entirely, or force the lender to use only the lower year’s income for qualification.
    • A modest decline under 10% is generally acceptable with a written explanation.
    • Increasing income across both years is the strongest possible signal and often allows the lender to use the two-year average without additional scrutiny.

    Underwriters are not just checking whether you made money. They are checking whether your business has a reason to keep making money. A seasonal freelancer who can show consistent clients, recurring contracts, and year-over-year stability gives the underwriter a story they can approve.

    Documentation that supports business viability year-round strengthens your file even during off-season months. Business licenses, client contracts, professional memberships, and a letter from your CPA confirming ongoing operations all help. The loan process for seasonal freelancers requires more thorough cash flow analysis than a standard W-2 review, and the supporting documents you provide shape that analysis directly.

    What documents do lenders require, and what alternatives exist?

    Standard documentation for seasonal freelance income qualification includes:

    • Two years of federal tax returns (personal and business, including all schedules)
    • Year-to-date profit and loss statement, ideally prepared by a CPA
    • Two to three months of business and personal bank statements
    • Business license or proof of self-employment
    • Evidence of seasonal work patterns, such as contracts, invoices, or client letters

    A detailed, accountant-prepared P&L demonstrates off-season cash flow management and reserves, which directly supports income reliability in the underwriter’s eyes. Freelancers who own 25% or more of their business are classified as self-employed under Fannie Mae guidelines and face the full self-employed documentation requirements, not the lighter seasonal employee standards.

    When tax returns show low net income because of aggressive write-offs, bank statement loans offer a practical alternative. These programs analyze 12–24 months of deposits and apply an expense factor to calculate qualifying income, bypassing the tax return entirely.

    Documentation type Conventional loan Bank statement loan
    Tax returns (2 years) Required Not required
    Bank statements (12–24 months) Supplemental Primary income document
    CPA-prepared P&L Helpful Can reduce expense factor to 35–40%
    Business license Required Required
    Year-to-date P&L Required Required

    Bank statement loan programs use a standard 50% expense factor on business account deposits. With a CPA-certified P&L, that factor can drop to 35–40%, which increases qualifying income without changing your actual earnings. For a freelancer with $150,000 in annual deposits, the difference between a 50% and a 35% expense factor is $22,500 in additional qualifying income per year. That gap can determine whether you qualify or not. For a deeper look at how these programs work in 2026, the variable income qualification guide covers current thresholds and documentation requirements in detail.

    My honest read on seasonal income and mortgage qualification

    By Chris Arco, NMLS #1281

    The freelancers who struggle most with mortgage qualification are not the ones with low income. They are the ones with good income that their tax returns do not show. Aggressive write-offs are a smart tax strategy right up until the moment you apply for a mortgage. Then they become a liability.

    The most common mistake I see is freelancers filing taxes to minimize their tax bill for years, then expecting a lender to approve them based on what they actually deposited. Underwriting does not work that way. The qualifying income number comes from your tax returns, not your bank account, unless you specifically choose a bank statement loan program.

    The second mistake is waiting too long to plan. Seasonal freelancers who want to buy a home in the next 12–18 months should be thinking about their tax strategy now, not after they file. A CPA who understands mortgage qualification can help you find the right balance between tax efficiency and qualifying income. That conversation is worth more than any rate negotiation.

    The third thing I would tell any seasonal freelancer: your income pattern matters as much as your income level. Two years of consistent, predictable earnings in your field is a stronger file than three years of erratic numbers. Build the pattern deliberately. Keep your business accounts clean. Document your off-season activity. When you sit down with an underwriter, you want your file to tell a clear, repeatable story.

    — Chris Arco, NMLS #1281

    Seasonal freelancers and 1st Nationwide Mortgage loan programs

    Qualifying for a mortgage with seasonal income is achievable when you work with a lender who understands how self-employed income actually works. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, licensed in 18 states and rated A+ by the BBB.

    https://1stnwm.com

    The bank statement mortgage program at 1st Nationwide Mortgage is built specifically for self-employed borrowers whose tax returns understate their real income. Deposits from 12 or 24 months replace tax returns as the qualifying document, with a minimum 620 credit score and 10–20% down. Use the bank statement income calculator to estimate your qualifying income before you apply. It takes your deposit totals and applies the appropriate expense factor so you know exactly where you stand. Reach out to 1st Nationwide Mortgage directly to discuss which program fits your income structure and timeline.

    Key takeaways

    Lenders qualify seasonal freelancers by averaging two years of adjusted net income, and bank statement loans offer a direct alternative when tax returns understate actual earnings.

    Point Details
    Two-year history is mandatory Without 24 months of documented income, lenders exclude seasonal earnings from qualification.
    Net profit drives the number Gross deposits do not qualify; lenders average adjusted net profit after adding back depreciation and removing one-time income.
    Stability matters as much as income A year-over-year decline greater than 20% can disqualify a borrower or force use of the lower income year.
    CPA-prepared P&L reduces expense factor A certified profit and loss statement can lower the bank statement loan expense factor from 50% to 35–40%, increasing qualifying income.
    Bank statement loans bypass tax returns Freelancers with high write-offs can qualify using 12–24 months of deposits instead of Schedule C net profit.

    FAQ

    How much income history do lenders require for seasonal freelancers?

    Lenders require a minimum of two years of documented income history for seasonal freelance earnings to count toward mortgage qualification. Without it, the income is excluded from the qualifying calculation entirely.

    What is the expense factor on a bank statement loan?

    The standard expense factor is 50% on business account deposits, meaning lenders count half of your total deposits as qualifying income. A CPA-certified profit and loss statement can reduce that factor to 35–40%, increasing your qualifying income.

    Can a year-over-year income decline disqualify a seasonal freelancer?

    A decline greater than 20% year-over-year may disqualify the borrower or require the lender to use only the lower year’s income for qualification. Smaller declines are generally acceptable with a written explanation.

    What documents do seasonal freelancers need to apply for a mortgage?

    The standard package includes two years of federal tax returns, a year-to-date profit and loss statement, two to three months of bank statements, a business license, and evidence of ongoing seasonal work such as contracts or client letters.

    What makes seasonal income different from irregular freelance income?

    Seasonal income follows a predictable annual cycle tied to a specific time of year, such as summer landscaping or holiday retail work. Irregular freelance income lacks that pattern, and underwriters treat unpredictable income as a higher qualification risk.

  • Foreign National Mortgage Qualification Factors Explained

    Foreign National Mortgage Qualification Factors Explained

    Foreign national mortgage qualification factors are the specific criteria lenders use to determine whether a non-citizen can secure financing for a U.S. investment property. These factors cover legal residency status, income verification, credit history, and documentation requirements. Unlike standard U.S. mortgages, foreign national loans fall outside Fannie Mae and Freddie Mac guidelines, which means lenders apply stricter standards and require alternative documentation. Understanding what lenders evaluate before you apply puts you in a much stronger position to close successfully.

    Legal residency status is the first factor every lender evaluates. Your visa type and immigration category determine which loan programs you can access and what documentation you must provide.

    Permanent and non-permanent residents follow different qualification pathways. Permanent residents with a green card generally follow standard U.S. lending guidelines. Non-permanent residents face stricter income and legal verification requirements because lenders must confirm that your right to remain in the country extends far enough to support the loan term.

    Accepted visa types include:

    • H-1B (specialty occupation workers)
    • L-1 (intracompany transferees)
    • E-2 (treaty investors)
    • F-1 (students, who must also provide an I-20 and employment authorization document)
    • O-1 (individuals with extraordinary ability)

    Lenders scrutinize visa expiration dates carefully. If your visa expires within 12 months of the loan closing date, most lenders will require evidence of renewal or a history of prior renewals. USCIS documentation must be current and match the name on all financial records exactly.

    Pro Tip: Get certified copies of all USCIS forms before you start the application. Discrepancies between your visa name and your bank account name are one of the most common causes of processing delays.

    2. What income verification methods do lenders accept for foreign nationals?

    Income verification for foreign nationals requires more documentation than a standard U.S. mortgage. Lenders need to confirm that your income is real, stable, and likely to continue for at least three years after closing.

    Man highlighting foreign income documents in bank

    Stable income for three years post-closing is a common lender requirement for non-permanent residents. That standard exists because lenders are underwriting a long-term obligation and need confidence that your income source will not disappear.

    Accepted income documentation typically includes:

    • Foreign pay stubs (last 30 days, with certified English translations)
    • Two years of foreign tax returns or business tax returns
    • Foreign bank statements showing 12–24 months of deposits
    • Retirement or pension income statements
    • Business income documentation for self-employed borrowers

    All foreign-language documents must be accompanied by certified English translations. Notarized translations carry more weight with underwriters than informal translations. If your income comes from a foreign business, lenders may also request a letter from a licensed accountant confirming the business’s operating status and your ownership percentage.

    Pro Tip: Open a U.S. bank account at least six months before applying. Transferring funds into a domestic account creates a paper trail that simplifies reserve verification and reduces underwriter questions.

    3. How do credit history and international credit reports impact approval chances?

    Most foreign nationals have no U.S. credit score. That is not automatically disqualifying, but it does require you to substitute alternative credit references that lenders can evaluate in place of a FICO score.

    Lenders accept international credit references including bank reference letters, global credit bureau reports, and character references from licensed professionals. The threshold varies by country of origin. Canadian borrowers typically need a credit score of 700 or above, while U.K. borrowers generally need 720 or above with no County Court Judgments on record.

    Here is how lenders typically rank alternative credit evidence:

    1. Official credit bureau report from your home country (strongest option)
    2. Bank reference letter from a major financial institution confirming account standing and payment history
    3. Mortgage payment history from a foreign lender showing on-time payments
    4. Utility and rental payment records spanning 12–24 months
    5. Character reference from a licensed attorney, CPA, or financial professional

    Because foreign national loans do not meet standard guidelines set by Fannie Mae or Freddie Mac, they are classified as non-qualified mortgages. That classification means lenders price in additional risk, which shows up in higher interest rates and stricter underwriting criteria compared to conforming loans.

    Foreign national mortgage applications require a specific set of documents that go beyond what a U.S. citizen would submit. Missing even one item can stall your closing by weeks.

    Standard documentation for a foreign national mortgage application includes a valid government-issued passport, proof of foreign residency such as a utility bill, and certified English translations for all financial records. Processing times for these specialized loans typically run 45–60 days. That timeline is longer than a conventional loan, so planning ahead is critical.

    One legal step that surprises many foreign buyers is LLC formation. Forming a U.S. LLC is often a legal prerequisite for closing on an investment property because it satisfies FIRPTA withholding and tax compliance requirements. LLC formation costs range from $500 to $2,500 depending on the state and legal counsel involved. The LLC must be established during the Letter of Intent phase, not at closing, or you risk delaying the entire transaction.

    Document Purpose
    Valid passport Primary identity verification
    Visa or green card Confirms legal entry and residency status
    Proof of foreign residency Utility bill or bank statement from home country
    Certified income translations Validates foreign pay stubs, tax returns, and bank records
    U.S. LLC formation documents Required for FIRPTA compliance on investment properties

    Pro Tip: Hire a U.S.-licensed real estate attorney before you make an offer. They can set up your LLC, review FIRPTA implications, and coordinate with your lender so nothing falls through the cracks at closing.

    5. Which specialized mortgage programs serve foreign nationals best?

    Most retail banks and credit unions do not offer foreign national loans. These loans are only accessible through specialized wholesale lenders and mortgage bankers who understand the non-QM market and have built programs specifically for international borrowers.

    The two most common program types for foreign nationals are DSCR loans and NONI loans. A DSCR (Debt Service Coverage Ratio) loan qualifies the property based on its rental income rather than your personal income. If the property generates enough rent to cover the mortgage payment, you qualify. This structure works well for investment properties and eliminates the need to document personal income from a foreign employer. DSCR loans also work for LLCs, which aligns with the entity structure most foreign nationals use for FIRPTA compliance.

    A NONI (No Income, No Asset) loan goes one step further. It requires no income documentation and no asset verification. 1st Nationwide Mortgage offers a NONI loan program specifically designed for foreign nationals who cannot document income through traditional channels.

    Key program features to compare when evaluating your options:

    • Down payment: Most foreign national programs require at least 20% down, with some lenders requiring 25–30% for non-permanent residents
    • Interest rates: Expect rates above conforming loan levels, reflecting the non-QM classification and additional compliance requirements
    • Loan limits: Jumbo amounts are available through select wholesale lenders
    • Entity eligibility: DSCR programs typically allow LLC borrowers, which is the preferred structure for foreign nationals

    Working with a mortgage banker who has direct access to wholesale lender channels gives you the widest range of program options. A lender who specializes in investment property financing for foreign nationals can match your residency status and credit profile to the right program from the start.

    Key takeaways

    Foreign national mortgage qualification depends on meeting specific legal, income, credit, and documentation standards that differ significantly from conventional U.S. lending requirements.

    Point Details
    Residency status drives eligibility Permanent residents follow standard guidelines; non-permanent residents face stricter income and visa documentation requirements.
    Income must show three-year stability Lenders require evidence that foreign income will continue for at least three years post-closing.
    Alternative credit references are accepted Bank letters, foreign bureau reports, and payment histories substitute for a U.S. credit score.
    LLC formation is a legal prerequisite Form your U.S. LLC during the Letter of Intent phase to satisfy FIRPTA rules and avoid closing delays.
    Specialized lenders are required Retail banks rarely offer these loans; non-QM wholesale lenders and direct mortgage bankers are the right channel.

    What I have learned from working with foreign national borrowers

    Working with foreign national borrowers has taught me one consistent lesson: the biggest obstacle is almost never the borrower’s financial strength. It is preparation.

    The foreign nationals who close smoothly are the ones who treat the mortgage process like a business project. They gather certified translations before the lender asks. They form their LLC at the Letter of Intent stage, not two weeks before closing. They open a U.S. bank account months in advance so their reserves are easy to verify. The ones who struggle are often just as financially qualified, but they underestimate how much documentation the process requires and how little room there is for last-minute scrambling.

    I also think the non-QM label scares people unnecessarily. Yes, foreign national loans carry higher rates than conforming loans. That is a real cost. But for an investor buying a cash-flowing rental property, the rate is one variable in a larger return calculation. The question is not whether the rate is higher than a 30-year fixed. The question is whether the property generates enough income to make the investment worthwhile. For most of the foreign national borrowers I work with, the answer is yes.

    My strongest advice is to start the legal and documentation work at least 90 days before you plan to make an offer. That window gives you time to form your LLC, gather certified translations, establish U.S. banking history, and connect with a lender who actually understands your situation. Foreign national mortgage qualification is achievable. It just rewards people who plan ahead.

    — Chris Arco, NMLS #1281

    How 1st Nationwide Mortgage helps foreign nationals finance U.S. properties

    1st Nationwide Mortgage is a direct mortgage banker, not a broker, with specialized experience working with foreign national borrowers. The firm offers DSCR loans, NONI loans, and other non-QM programs designed for international investors who cannot qualify through conventional channels.

    https://1stnwm.com

    If you are a foreign national looking to finance a U.S. investment property, the investment property mortgage page outlines the programs and qualification criteria in detail. 1st Nationwide Mortgage works directly with wholesale lender channels to match your residency status, income profile, and property type to the right loan program. Contact 1st Nationwide Mortgage to schedule a consultation and get a clear picture of what you qualify for before you make an offer.

    FAQ

    What is a foreign national mortgage?

    A foreign national mortgage is a loan made to a non-U.S. citizen who lacks a Social Security number or U.S. credit history. These loans are classified as non-qualified mortgages and are only available through specialized lenders.

    How much do foreign nationals need to put down on a U.S. property?

    Most foreign national loan programs require a minimum down payment of 20%, with some lenders requiring 25–30% depending on residency status and credit profile.

    Can a foreign national qualify without a U.S. credit score?

    Yes. Lenders accept alternative credit references including foreign credit bureau reports, bank reference letters, and documented payment histories from foreign lenders or landlords.

    What is a DSCR loan and why does it suit foreign nationals?

    A DSCR loan qualifies the borrower based on the property’s rental income rather than personal income. This structure removes the need to document foreign employment income, making it one of the most practical options for international real estate investors.

    How long does a foreign national mortgage take to close?

    Processing times for foreign national mortgage loans typically run 45–60 days, longer than a conventional loan, due to the additional documentation and compliance requirements involved.

  • Alternative Mortgage Qualification Criteria for Freelancers

    Alternative Mortgage Qualification Criteria for Freelancers

    Alternative mortgage qualification criteria for freelancers are defined as income verification methods that replace traditional W-2 documentation with bank statements, profit-and-loss statements, or other flexible evidence of cash flow. Fannie Mae and Freddie Mac set the two-year self-employment benchmark as the industry standard for self-employed borrowers. Most freelancers fail conventional qualification not because their income is insufficient, but because their tax returns understate it after deductions. The good news: lenders have built entire loan categories around this exact problem. Understanding which path fits your financial profile is the first step toward approval.

    1. What are alternative mortgage qualification criteria for freelancers?

    Alternative mortgage qualification criteria are underwriting standards that accept non-traditional income proof in place of W-2s and tax returns. They exist because conventional loans, which follow Fannie Mae and Freddie Mac guidelines, calculate qualifying income from net profit after deductions. Freelancers who write off legitimate business expenses often show taxable income far below their actual earnings.

    The most common alternative paths include bank statement loans, profit-and-loss statement loans, and 1099-based programs. Each path has its own documentation rules, credit thresholds, and cost structure. Knowing which one fits your situation before you apply saves time and protects your credit score from unnecessary inquiries.

    Hands sorting mortgage financial documents overhead

    2. Bank statement loans: how they work and who qualifies

    Bank statement loans are non-QM mortgage products that calculate your income from 12 to 24 months of bank deposits rather than tax returns. The lender applies an expense factor to your gross deposits to estimate net income. At 1st Nationwide Mortgage, the standard expense factor on business accounts is 50%, which can drop to 35–40% with a CPA-certified profit-and-loss statement.

    Key qualification criteria for bank statement loans include:

    • Bank statements: 12 or 24 months of personal or business account statements
    • Credit score: Minimum 620, though higher scores improve rate pricing
    • Down payment: Typically 10–20% of the purchase price
    • Income calculation: Gross deposits multiplied by the applicable expense factor
    • Consistency: Deposits must show a stable or growing pattern across the statement period

    Non-QM bank statement loans carry higher interest rates and closing costs than conventional loans. That tradeoff is worth it when your tax returns show too little income to qualify conventionally.

    Pro Tip: Avoid large, irregular deposits in the 12–24 months before applying. Underwriters flag unexplained spikes as non-recurring income and exclude them from the calculation.

    3. Using profit-and-loss statements for mortgage qualification

    A profit-and-loss statement, or P&L, is a financial summary showing your revenue, expenses, and net income over a set period. Lenders use it to verify that your cash flow is real and consistent, especially when bank deposits alone do not tell a complete picture. A CPA-prepared P&L carries significantly more weight than a self-prepared one.

    The documents that lenders cross-reference when reviewing a P&L include:

    • Tax returns: Schedule C or business returns for the past one to two years
    • Bank statements: To confirm that deposits match reported revenue
    • Invoices or contracts: To support income claims for ongoing client work
    • Business license or CPA letter: To confirm active self-employment status

    Applicants whose documents tell a consistent story avoid underwriting red flags and additional scrutiny. A P&L that shows $120,000 in revenue while bank statements show $80,000 in deposits will trigger questions. Alignment across all three document types is what moves an application forward.

    Pro Tip: Prepare your P&L before you start shopping for a home. A CPA-certified statement dated within 60 days of application is the most lender-friendly format.

    4. Credit and financial requirements for alternative mortgage paths

    Credit score minimums for non-QM loans sit around 620, though some lenders accept scores as low as 500 with compensating factors such as a larger down payment or significant cash reserves. Lower scores come with higher rates. A score above 700 meaningfully improves your pricing on alternative products.

    Debt-to-income ratios must typically stay below 43% for most alternative mortgage programs. Lenders calculate DTI using the income derived from your bank statements or P&L, not your gross revenue. Irregular income patterns require lenders to average your earnings, which can compress your qualifying DTI.

    Loan type Min. credit score Down payment DTI limit
    Conventional (tax return) 620+ 3–20% 43–45%
    Bank statement loan 620+ 10–20% 43–50%
    P&L-based loan 620+ 10–20% 43–50%
    1099 income loan 620+ 10–20% 43–50%

    Cash reserves matter more for freelancers than for salaried borrowers. Lenders want to see that you can cover several months of mortgage payments if client work slows. Twelve months of reserves strengthens any alternative mortgage application.

    5. How lenders assess self-employment history and income stability

    The two-year self-employment requirement from Fannie Mae and Freddie Mac is the baseline for conventional loans. It signals to lenders that your freelance income is established, not experimental. Alternative loan programs often follow the same standard, though some allow exceptions.

    Lenders look for these signals of income stability:

    • Two-year history: Consistent self-employment for at least 24 months, documented by tax returns and business records
    • Income trend: Flat or growing income year over year. Declining income raises questions even if totals are high
    • Client diversification: Income from multiple clients reduces the risk that losing one contract collapses your cash flow
    • Related field exception: Some lenders allow one year of self-employment if paired with two years of W-2 work in the same field or a relevant degree

    The two-year self-employment mortgage rule is not arbitrary. It gives underwriters two full tax cycles to evaluate income patterns. If you are approaching the two-year mark, waiting a few months before applying can significantly expand your loan options.

    Lenders also weigh client concentration. A freelancer earning $150,000 from one client looks riskier than one earning $150,000 from eight clients. Documenting your client base with contracts or 1099 forms strengthens your application.

    6. Choosing the right alternative mortgage option for your freelance profile

    The best freelance income mortgage documentation strategy starts with tax returns. If your net income after deductions qualifies you conventionally, that is always the lower-cost path. You move to bank statement or P&L-based loans only when tax returns understate your actual earnings.

    Here is how to match your situation to the right loan type:

    • Heavy write-offs, strong deposits: Bank statement loan. Your gross deposits reflect real income that tax returns hide.
    • Clean books, CPA-prepared financials: P&L loan. A certified statement can substitute for or supplement tax returns.
    • 1099 income, limited deductions: 1099 mortgage programs treat your gross 1099 income more favorably than Schedule C.
    • Lower credit score: Look for lenders with compensating factor flexibility. A larger down payment or strong reserves can offset a score below 680.
    • Short self-employment history: Explore lenders who accept one year of self-employment with a related employment background.

    Mortgage products are matched to borrower documentation, not the other way around. Talk to a lender before you decide which documents to gather. An experienced underwriter can identify your qualifying lane in a single conversation and prevent wasted effort.

    The Consumer Financial Protection Bureau notes that non-QM loans do not meet the Ability-to-Repay standards that qualified mortgages must satisfy. That means you carry more responsibility for evaluating affordability when choosing these products. Run the numbers carefully before committing to a higher-rate alternative loan.

    Pro Tip: Reducing business deductions in the 12–24 months before applying raises your qualifying income on conventional and tax-return-based loans. Coordinate with your CPA before making that decision, since it affects your tax liability.

    Key takeaways

    Freelancers qualify for mortgages most effectively by matching their documentation type to the right loan program, whether that is bank statements, a CPA-certified P&L, or 1099-based income verification.

    Point Details
    Two-year history is the baseline Fannie Mae and Freddie Mac require two years of self-employment for conventional qualification.
    Bank statement loans fill the gap 12–24 months of deposits replace tax returns when write-offs reduce reported income.
    Document consistency is critical Tax returns, bank statements, and P&L statements must tell the same income story.
    Credit and reserves both matter A 620+ score and 12 months of cash reserves strengthen any alternative application.
    Match the loan to your documents Tax-return loans cost less; move to non-QM options only when conventional income falls short.

    What I’ve learned about freelancer mortgage applications after years in the field

    Most freelancers come to me frustrated. They have been told “no” by a lender who ran their tax returns and stopped there. What they do not realize is that the “no” was not about their income. It was about which document the lender looked at.

    The single biggest mistake I see is document inconsistency. A freelancer shows me bank statements with $180,000 in annual deposits, a tax return showing $60,000 in net income, and a P&L prepared the week before the application that shows $140,000. Those three numbers do not reconcile. Underwriters do not give the benefit of the doubt. They flag the file and ask for explanations that slow everything down or kill the deal.

    The freelancers who close successfully treat their financial documents like a single, coherent report. They work with their CPA throughout the year, not just at tax time. They know their average monthly deposits. They understand how their expense ratio affects their qualifying income under a bank statement loan. They come to the first conversation with a lender already knowing their numbers.

    My advice: contact a lender at least six months before you plan to buy. That window gives you time to adjust your documentation strategy, reduce unnecessary deductions if needed, and build reserves. The alternative income documentation path is not harder than conventional. It just requires more preparation.

    — Chris Arco, NMLS #1281

    Loan programs at 1st Nationwide Mortgage built for freelancers

    Freelancers with non-traditional income have real options at 1st Nationwide Mortgage. As a direct mortgage banker licensed in 18 states, 1st Nationwide Mortgage underwrites bank statement loans in-house, which means faster decisions and no broker markup. The bank statement program accepts 12 or 24 months of deposits, applies a CPA-adjustable expense factor, and requires a minimum 620 credit score with 10–20% down.

    https://1stnwm.com

    If you are unsure which loan program fits your income documentation, the loan programs overview at 1st Nationwide Mortgage covers every available path, from bank statement and 1099 loans to conventional and FHA options. You can also use the mortgage calculators to estimate your qualifying income and monthly payment before speaking with a loan officer. Reach out directly to get a clear answer on which underwriting lane fits your freelance profile.

    FAQ

    What documents do freelancers need for a mortgage?

    Freelancers typically need 12–24 months of bank statements or tax returns, a CPA-prepared profit-and-loss statement, a business license, and 1099 forms from clients. The exact set depends on which loan program you use.

    What credit score do freelancers need for a mortgage?

    Most alternative mortgage programs require a minimum 620 credit score. Some lenders accept scores as low as 500 with compensating factors such as a larger down payment or strong cash reserves.

    How does a bank statement loan calculate income?

    The lender totals your gross deposits over 12 or 24 months and applies an expense factor, typically 50% on business accounts, to estimate net qualifying income. A CPA-certified P&L can lower that expense factor to 35–40%.

    Can a freelancer qualify with less than two years of self-employment?

    Some lenders allow one year of self-employment if the borrower has two years of W-2 work in the same field or a related degree. The borrower must also show income equal to or greater than their prior employment.

    Are bank statement loans more expensive than conventional loans?

    Bank statement loans carry higher interest rates and closing costs than conventional loans because they are non-QM products not backed by Fannie Mae or Freddie Mac. The cost premium is the tradeoff for qualifying without tax-return income.

  • Bank Statement Loan Lender Examples for Self-Employed Buyers

    Bank Statement Loan Lender Examples for Self-Employed Buyers

    A bank statement loan is defined as a mortgage that uses 12–24 months of bank deposits to calculate qualifying income instead of tax returns or W-2s. This approach exists specifically for self-employed borrowers, freelancers, and business owners whose write-offs reduce their reported income below what conventional lenders will accept. The best bank statement loan lender examples share one trait: they specialize in reading deposit history as a proxy for real earning power. Understanding how these lenders think, what they measure, and where they differ gives you a real advantage when you apply. 1st Nationwide Mortgage is a direct mortgage banker that operates this way across 18 licensed states.

    What makes bank statement loan lender examples different from traditional lenders

    Traditional mortgage lenders rely on tax returns, W-2s, and pay stubs to verify income. Bank statement mortgage lenders take a different path entirely. They average your monthly deposits over 12 or 24 months, then apply an expense factor to deposits to estimate your net qualifying income. That expense factor typically runs between 10% and 50%, depending on your industry and documentation.

    Hands sorting bank statements and tax documents

    The underwriting process is manual, not automated. A human underwriter reviews your statements line by line, looking for patterns, not just totals. Bank statement loans are classified as non-QM loans, meaning Fannie Mae and Freddie Mac do not purchase them. Private lenders set their own rules, which creates real variation in how each lender qualifies you.

    Key features that define this lender category:

    • Income source: Deposits replace tax returns as the income document
    • Expense factor: Applied to gross deposits to estimate net income (commonly 50% on business accounts)
    • Statement period: 12 or 24 months, depending on the lender’s program
    • Account type: Business statements, personal statements, or a blended mix
    • Underwriting: Manual review with a 30–45 day typical timeline
    • Loan type: Non-QM portfolio product, not sold to government-sponsored enterprises

    Pro Tip: Ask any lender upfront whether they accept a CPA-prepared Profit and Loss statement. A certified P&L can drop your expense factor from 50% down to 35–40%, which directly increases your qualifying income without changing your actual deposits.

    1. Self-employed borrowers with consistent business deposits

    The most common borrower profile for this loan type is a self-employed business owner with two or more years of operating history. Lenders in this category look for steady monthly deposits that tell a believable income story. Underwriters prioritize consistency over raw volume. A borrower depositing $15,000 every month is a stronger file than one depositing $5,000 one month and $40,000 the next, even if the annual totals are similar.

    1st Nationwide Mortgage structures its bank statement program around this profile. The minimum credit score is 620, and down payment requirements run from 10% to 20% depending on loan size and credit. Business account deposits carry a standard 50% expense factor, which drops to 35–40% with a CPA-certified P&L.

    2. Freelancers and contractors using personal bank statements

    Freelancers often lack a formal business account. Many bank statement lenders accept personal statements as the primary income document, provided the deposits are clearly tied to client payments rather than transfers or gifts. The lender will ask you to explain any deposit that looks like a transfer from another account you own.

    Personal account programs typically apply a higher expense factor than business account programs, since the lender cannot verify business overhead separately. If you operate as a sole proprietor and run all income through a personal checking account, confirm with the lender whether they accept that structure before you apply.

    3. Real estate investors with rental income complexity

    Real estate investors often have layered income: rental deposits, property management reimbursements, and occasional large inflows from property sales. Bank statement lenders that serve investors know how to separate operating income from one-time events. Lenders accept personal or business statements, sometimes blended, depending on how the investor’s corporate structure is organized.

    For investors who own properties in an LLC, 1st Nationwide Mortgage also offers DSCR loans for investors, where the property’s rental income qualifies the loan rather than the borrower’s personal deposits. That option removes personal income from the equation entirely.

    4. Seasonal business owners with fluctuating deposits

    Restaurant owners, landscapers, tax professionals, and tourism operators all experience income that peaks and drops by season. Borrowers with fluctuating incomes can qualify by providing consistent deposits with written explanations for seasonal or irregular cash flow. The key is that the pattern must match the business type.

    A landscaping company showing low deposits in january and february is expected. An accountant showing low deposits in april is not. Underwriters want the income story to make sense for the industry. Prepare a brief written explanation of your business cycle before you submit your application.

    5. High-expense businesses like restaurants and construction

    Some industries carry overhead so high that even a generous expense factor leaves little qualifying income. Default expense factors can reach 70% for industries like restaurants, where food costs, labor, and rent consume most of gross revenue. Construction companies face similar math.

    The solution is a CPA-prepared P&L that documents actual overhead. Expense factor negotiation can significantly improve qualifying income when a certified accountant shows that real expenses are lower than the lender’s default assumption. This is one of the most underused tools in the bank statement loan application guide.

    6. Borrowers with large or unusual deposits

    Large deposits create underwriting friction. Deposits exceeding 50% of monthly qualifying income are flagged for explanation. The underwriter needs to confirm the deposit is income, not a gift, loan, or transfer. If you recently sold a property or received a large client payment, document it with a contract, closing statement, or invoice before your lender asks.

    Deposit seasoning matters too. Funds that have been in your account for 60 or more days draw far less scrutiny than a large deposit that arrived last week. Plan your application timing around your deposit history, not just your credit score.

    7. Borrowers in California with high property values

    Bank statement loans in California often involve jumbo loan amounts because of the state’s property values. Lenders serving California borrowers need to be comfortable with larger loan balances and higher reserve requirements. 1st Nationwide Mortgage is licensed in California and structures its programs to accommodate the state’s price environment.

    California borrowers should also expect that lenders will scrutinize business account statements more carefully when loan amounts are high. The income calculation must support a debt-to-income ratio that works at the loan size requested.

    8. Texas borrowers with self-employed income

    Texas has no state income tax, which means many self-employed borrowers there run lean on paper income. Bank statement loans in Texas are a natural fit for this population. Lenders licensed in Texas understand the state’s homestead laws and property tax structure, both of which affect the total payment calculation.

    1st Nationwide Mortgage is licensed in Texas and works with self-employed borrowers across the state. The same 620 minimum credit score and 10–20% down payment structure applies.

    9. Portfolio lenders vs. wholesale lenders for bank statement products

    Portfolio lenders hold the loan on their own balance sheet after closing. Wholesale lenders sell the loan to a secondary market investor. For bank statement loans, portfolio lenders offer more flexibility because they set their own underwriting rules. Wholesale lenders must follow investor guidelines, which can be more rigid.

    The trade-off is rate. Portfolio lenders sometimes price slightly higher because they carry the credit risk themselves. Non-QM bank statement loans carry higher rates than conventional loans regardless of lender type. The rate premium is the cost of qualifying without tax returns. For most self-employed borrowers, that trade-off is worth it.

    10. How underwriters verify business expense patterns

    Underwriters check business expense patterns against deposits by looking at payroll, rent, and utility payments. If your deposits suggest a $20,000-per-month business but your statements show no payroll, no rent, and no supply purchases, the underwriter will ask questions. The business activity visible in your statements must match the scale of income you are claiming.

    This is why clean, well-organized bank statements matter. Avoid running personal expenses through your business account during the 12–24 months you plan to use for qualification. Mixing personal and business transactions makes the underwriter’s job harder and your approval slower.

    Key takeaways

    Bank statement loan lenders qualify self-employed borrowers by averaging deposits over 12–24 months and applying an expense factor, making deposit consistency more important than total volume.

    Point Details
    Expense factor drives income A 50% factor on business deposits cuts qualifying income in half; a CPA P&L can reduce it to 35–40%.
    Consistency beats volume Underwriters favor steady monthly deposits over large, irregular inflows that require explanation.
    Large deposits need documentation Any deposit over 50% of monthly qualifying income will be flagged and must be sourced clearly.
    Portfolio lenders offer more flexibility They set their own rules and can accommodate unusual income profiles better than wholesale lenders.
    State licensing matters Confirm your lender is licensed in California, Texas, or your target state before you apply.

    What I’ve learned after years of bank statement underwriting

    Working directly with self-employed borrowers for years, I’ve seen one pattern repeat more than any other: borrowers who prepare their documentation before they apply close faster and with fewer conditions. The borrowers who struggle are the ones who assume the lender will figure out their income story for them.

    The most common mistake I see is mixing personal and business transactions in the same account. When an underwriter sees a business account with grocery store charges, Amazon purchases, and school tuition payments, they question whether the deposits are really business income. That doubt creates conditions, and conditions create delays.

    The second mistake is waiting until the last minute to get a CPA-prepared P&L. That document can meaningfully change your qualifying income, but it takes time to prepare correctly. If your accountant needs two weeks, factor that into your timeline.

    I also want to address the rate question directly. Yes, bank statement loans carry higher rates than conventional mortgages. That is the cost of the program, and it is a fair trade for borrowers who cannot qualify any other way. The goal is to get into the property, build equity, and refinance into a conventional loan when your tax returns reflect your actual income. That path works. I’ve seen it work many times.

    The lenders who serve this market well are the ones who communicate clearly, explain the expense factor calculation upfront, and tell you exactly what documentation they need before you submit. If a lender is vague about how they calculate income, that is a signal to ask more questions.

    — Chris Arco, NMLS #1281

    1st Nationwide Mortgage’s bank statement loan programs

    Self-employed borrowers and real estate investors have real options at 1st Nationwide Mortgage. As a direct mortgage banker licensed in 18 states, 1st Nationwide Mortgage underwrites bank statement loans in-house, which means faster decisions and direct communication with the team reviewing your file.

    https://1stnwm.com

    You can review the full bank statement loan program details, including documentation requirements and qualifying criteria. The bank statement income calculator lets you estimate your qualifying income before you apply, using your actual deposit history and expense factor. For a broader view of available programs, the loan programs overview covers every product 1st Nationwide Mortgage offers, from bank statement loans to DSCR and NONI options for investors and foreign nationals.

    FAQ

    What is a bank statement loan?

    A bank statement loan is a non-QM mortgage that uses 12–24 months of bank deposits to calculate qualifying income instead of tax returns or W-2s. It is designed for self-employed borrowers whose write-offs reduce their reported income below conventional lending thresholds.

    How do lenders calculate income from bank statements?

    Lenders average monthly deposits over the statement period and apply an expense factor, typically 50% on business accounts, to estimate net income. A CPA-prepared P&L can reduce that factor to 35–40%, increasing the qualifying income figure.

    What credit score do I need for a bank statement loan?

    Most bank statement loan lenders require a minimum credit score of 620. Down payment requirements typically range from 10% to 20% depending on loan size and credit profile.

    Can seasonal business owners qualify for bank statement loans?

    Yes. Lenders accept fluctuating deposits when the pattern matches the business type. A written explanation of your business cycle, paired with consistent year-over-year deposit history, satisfies most underwriters.

    Are bank statement loans available in California and Texas?

    Yes. Bank statement loans are available in both states through lenders licensed there, including 1st Nationwide Mortgage. California borrowers often need jumbo loan amounts, while Texas borrowers benefit from the program’s flexibility around self-employed income with no state tax returns to complicate the picture.

  • How Mortgage Lenders Verify Self-Employed Income

    How Mortgage Lenders Verify Self-Employed Income

    Mortgage lenders verify self-employed income through signed federal tax returns, business financial records, and bank statements reviewed together to confirm that your earnings are real, stable, and sufficient to repay a loan. The process is formally called self-employed income verification, and it follows stricter documentation standards than W-2 borrower reviews. Understanding how mortgage lenders verify self-employed income before you apply puts you in control of the outcome. The lender’s goal is not to penalize you for running a business. The goal is to confirm that your income will continue after closing.

    What documentation do lenders require to verify self-employed income?

    Conventional mortgage lenders require two years of signed personal federal tax returns and business tax returns if you own 25% or more of a business. That two-year window gives underwriters a pattern, not just a snapshot. One strong year means little without a second year to confirm the trend.

    The full document list typically includes:

    • Two years of signed personal tax returns with all schedules (Schedule C, Schedule E, Schedule K-1 depending on your business structure)
    • Two years of business tax returns for S-corps, partnerships, or corporations you own at 25% or more
    • Year-to-date profit and loss statement prepared or reviewed by a licensed CPA to reflect current income
    • Business and personal bank statements covering 12–24 months of deposits
    • Business license or registration to confirm the business has been operating for the required period
    • CPA letter or accountant letter confirming you are self-employed and your business is active

    Lenders review P&L statements alongside tax returns because tax returns reflect the prior year while a current P&L shows what your business is earning right now. The two documents together give underwriters a complete picture of past and present income.

    IRS transcripts may serve as an alternative to signed tax returns if they are complete and legible. Some lenders pull transcripts directly from the IRS to confirm that what you submitted matches what was filed. This step protects against income inflation and is standard practice at many institutions.

    Loan officer examining financial paperwork

    Pro Tip: Have your CPA prepare a year-to-date P&L before you apply, not after the lender requests it. A well-organized P&L signals professionalism and speeds up underwriting.

    How do lenders calculate qualifying income from self-employment?

    Income calculation for self-employed borrowers follows a specific method that differs significantly from how W-2 income is counted. Lenders do not use your gross revenue. They use your net business income after expenses, averaged across the documentation period.

    Here is how the calculation typically works:

    1. Start with net income from tax returns. The underwriter pulls your net profit from Schedule C (sole proprietors), Schedule K-1 (partnerships and S-corps), or Form 1120S (S-corp returns).
    2. Add back allowable deductions. Lenders add back deductions like depreciation, depletion, and non-recurring business expenses that reduced your taxable income but did not represent actual cash leaving the business.
    3. Subtract business use of home and meals. These deductions are not added back because they represent real costs of running the business.
    4. Average the two years. The underwriter adds year one and year two adjusted income, then divides by 24 months to get a monthly qualifying figure.
    5. Apply the income trend rule. If income rose from year one to year two, some lenders use only the most recent year’s figure, which benefits you. If income fell, the lender uses the lower figure or may require a written explanation.
    Income Scenario Lender Approach Impact on Qualification
    Stable income (both years similar) 2-year average Neutral
    Rising income May use most recent year only Positive
    Declining income Uses lower year or requires explanation Negative
    Sharp decline May reduce qualifying income or deny Significant risk

    When income shows a downward trend, lenders expect a written explanation and supporting proof that the decline was temporary. Client contracts, signed agreements, or a letter from your accountant can support that explanation.

    Infographic showing steps for income verification

    Pro Tip: If your income rose significantly in the most recent year, ask your loan officer whether the lender’s guidelines allow a one-year average. Not all lenders offer this, but those who do can qualify you at a higher income figure.

    How do lenders verify the legitimacy and stability of your business?

    Lenders treat income verification as an underwrite of business survivability, not just a tax document review. A business that generated strong income last year but shows signs of closing today is a risk no lender will accept.

    Business legitimacy checks typically include:

    • Secretary of state records to confirm the business is registered and in good standing
    • Online presence review including a website, Google Business listing, or professional directory listing that confirms the business is active
    • Accountant or CPA contact where the lender may call or send a written inquiry to confirm your business is operating
    • Business bank account activity reviewed to confirm regular deposits consistent with the income claimed on tax returns
    • Explanation letters for gaps if there are periods of reduced or no business activity, the lender requires a written explanation with supporting documentation

    Business verification checks must confirm the business is active close to the loan closing date. A business found dormant near closing can stall or cancel the loan entirely. This is not a formality. Underwriters take it seriously.

    Consistency of income is the primary metric lenders use when evaluating self-employed borrowers. Fluctuations require credible explanations backed by documentation, not just verbal assurances.

    What challenges do self-employed borrowers face and how can you prepare?

    Self-employed borrowers face documentation hurdles that W-2 employees never encounter. Knowing the common obstacles in advance lets you address them before the underwriter raises them.

    The most frequent challenges include:

    • Tax write-offs that reduce qualifying income. Aggressive deductions lower your taxable income, which is great for taxes but reduces the net income lenders count. A freelancer earning $120,000 gross but claiming $60,000 in deductions qualifies on $60,000, not $120,000.
    • Business debts that affect your personal DTI. Business loans personally guaranteed by you appear in your personal debt-to-income ratio even if the business makes the payments. A business line of credit you signed for personally counts against you.
    • Fluctuating income that triggers scrutiny. A year with significantly lower income requires a documented explanation. Without one, the lender uses the lower figure or declines the file.
    • Incomplete or unreviewed P&L statements. A P&L prepared without CPA review carries less weight with underwriters than one signed by a licensed accountant.

    Preparation steps that improve your approval odds:

    • Work with a CPA familiar with mortgage underwriting who can prepare documentation that meets lender standards, not just IRS standards
    • Gather client contracts, signed agreements, and letters of ongoing work to support income stability claims
    • Review the two-year self-employment requirement before applying so you understand exactly what the documentation window covers
    • Consider alternative income documentation programs if your tax returns understate your actual cash flow

    Pro Tip: If your write-offs are so large that your tax returns cannot support the loan amount you need, a bank statement loan may qualify you on actual deposits instead of net taxable income. 1st Nationwide Mortgage offers bank statement programs using 12–24 months of deposits with a standard expense factor of 50%, which can drop to 35–40% with a CPA-certified P&L.

    Key Takeaways

    Self-employed income verification requires two years of tax returns, add-back calculations, business legitimacy checks, and documented explanations for any income decline before a lender approves your loan.

    Point Details
    Two-year tax return standard Lenders require signed personal and business returns for the past two years to establish an income pattern.
    Net income with add-backs Qualifying income starts with net profit, then adds back depreciation and non-recurring expenses.
    Business legitimacy checks Lenders verify active business status through state records, online presence, and accountant confirmation.
    Business debts count personally Loans you personally guaranteed appear in your debt-to-income ratio even if the business pays them.
    Alternatives exist for write-off-heavy filers Bank statement loans qualify borrowers on actual deposits when tax returns understate real income.

    What I’ve learned from years of self-employed mortgage files

    Working with self-employed borrowers for years, the single biggest mistake I see is waiting until the last minute to organize documentation. A freelance consultant who earns $200,000 a year can lose a loan approval because their CPA prepared a P&L in three days that does not reconcile with the bank statements. Underwriters notice every discrepancy.

    The second mistake is assuming that a high gross revenue number will carry the file. Lenders do not care what you billed. They care what you kept after expenses, and they will calculate that number themselves from your returns. If your write-offs are aggressive, your qualifying income may be a fraction of what you expected.

    What actually works is transparency paired with preparation. Borrowers who come in with organized two-year returns, a clean CPA-reviewed P&L, and a clear explanation for any income variation close faster and with fewer conditions. The lender is not your adversary. The underwriter is trying to build a case that your income is real and sustainable. Your job is to make that case easy to build.

    If your tax returns genuinely cannot support the loan you need, that is not a dead end. Bank statement programs exist specifically for this situation. At 1st Nationwide Mortgage, we work with self-employed borrowers every day who qualify on deposits rather than net taxable income. The path to approval exists. You just need to know which road to take.

    — Chris Arco, NMLS #1281

    Self-employed mortgage options at 1st Nationwide Mortgage

    1st Nationwide Mortgage is a direct mortgage banker, not a broker, licensed in 18 states and rated BBB A+. The team works specifically with self-employed borrowers, freelancers, and contractors who face documentation challenges with conventional loan programs.

    https://1stnwm.com

    For borrowers whose tax returns understate real income, the bank statement loan program uses 12–24 months of deposits to calculate qualifying income. No tax returns required. For real estate investors, DSCR loans qualify on property rental income with no personal income documentation at all. You can review the full range of self-employed loan programs or use the mortgage calculators to estimate what you may qualify for based on your actual income picture.

    FAQ

    What tax returns do lenders require from self-employed borrowers?

    Lenders require two years of signed personal federal tax returns and business tax returns if you own 25% or more of the business. IRS transcripts may be accepted as an alternative when complete and legible.

    How do lenders calculate self-employed qualifying income?

    Lenders average net business income over two years and add back deductions like depreciation and non-recurring expenses. If income is rising, some lenders use only the most recent year’s figure.

    Can a self-employed borrower qualify without tax returns?

    Yes. Bank statement loan programs use 12–24 months of deposit history to derive qualifying income instead of tax returns. These programs are designed for borrowers whose write-offs reduce net taxable income below what conventional underwriting accepts.

    Do business debts affect a self-employed borrower’s mortgage qualification?

    Business debts you personally guaranteed count in your personal debt-to-income ratio, even if the business makes the monthly payments. This can reduce the loan amount you qualify for.

    What happens if my self-employed income declined last year?

    A declining income trend requires a written explanation and supporting documentation such as client contracts or a CPA letter confirming the setback was temporary. Without adequate documentation, the lender uses the lower income figure or may reduce the qualifying amount.

  • Depreciation’s Role in Mortgage Qualification Explained

    Depreciation’s Role in Mortgage Qualification Explained

    Depreciation is defined as a non-cash accounting expense that lenders add back to your reported income when calculating how much mortgage you qualify for. This add-back is the core of the role of depreciation in mortgage qualification: it increases your effective qualifying income without requiring you to earn more money. Self-employed borrowers and rental property investors benefit most from this treatment, because aggressive tax write-offs often push their reported net income far below their actual cash flow. Understanding how lenders apply these adjustments, and how to position your finances accordingly, can meaningfully increase your borrowing capacity.

    How does depreciation affect mortgage qualification for self-employed borrowers?

    Lenders do not take your tax return net income at face value. For self-employed borrowers, underwriters analyze Schedule C and add back non-cash expenses like depreciation, amortization, and depletion to arrive at a more accurate picture of your cash flow. These add-backs can increase monthly qualifying income by $500 to $2,000 depending on your assets and business scale. That range is significant because even a $500 monthly increase can raise your qualifying loan amount by tens of thousands of dollars.

    The standard underwriting process for self-employment income involves two key steps. First, lenders average two years of net profit after adding back non-cash expenses. Second, they exclude non-recurring income that will not continue. This two-year average smooths out volatile income years and gives underwriters a defensible number to work with.

    Here is what lenders typically add back from Schedule C:

    • Depreciation: The most common add-back for business owners with equipment, vehicles, or property.
    • Amortization: Write-offs for intangible assets like patents or goodwill.
    • Depletion: Relevant for borrowers in natural resource industries.
    • Casualty losses: One-time losses from events like fires or floods.
    • Business use of home: Non-cash home expenses added back because they do not represent real cash leaving your account.

    Each of these items reduces your taxable income on paper. None of them reduces the actual cash you have available to make a mortgage payment.

    Pro Tip: If you are self-employed and planning to apply for a mortgage within the next 12 months, ask your CPA to run a projection showing your qualifying income with all add-backs applied. That number, not your net profit, is what the lender will use.

    How rental property income is calculated with depreciation add-backs

    Rental property owners face a similar dynamic, but the mechanics work through Schedule E instead of Schedule C. Lenders calculate net rental income by starting with gross rents and then adding back depreciation, mortgage interest, taxes, and insurance. The result is a cash flow figure that reflects what the property actually generates, not what the tax return shows after depreciation.

    Hands reviewing rental income tax documents

    One important adjustment: lenders typically count only 75% of gross rent. The 25% reduction accounts for vacancies and maintenance costs. Even with that haircut, the depreciation add-back often more than compensates, because rental property depreciation can be substantial on a $300,000 or $400,000 asset.

    Infographic comparing mortgage income with and without depreciation

    The table below shows how depreciation add-backs change the qualifying income calculation on a single rental property:

    Income Component Without Add-Back With Depreciation Add-Back
    Gross monthly rent $2,400 $2,400
    75% vacancy adjustment $1,800 $1,800
    Net income after expenses $400 $400
    Depreciation add-back $0 $700
    Qualifying monthly income $400 $1,100

    The difference between $400 and $1,100 per month in qualifying income is not a rounding error. On a 30-year mortgage at a typical rate, that gap can represent $100,000 or more in additional borrowing capacity. Investors with multiple rental properties see this effect multiply across their entire portfolio.

    Pro Tip: When you own multiple rentals, the combined depreciation add-backs across all Schedule E properties can dramatically shift your debt-to-income ratio. Run the numbers on your full portfolio before assuming you do not qualify.

    Why lenders treat depreciation differently than repairs

    Depreciation and repairs both reduce your taxable income, but lenders treat them in opposite ways. Depreciation is a non-cash expense. Repairs are recurring cash expenditures that you actually pay out of pocket. Because depreciation does not reduce your real cash flow, lenders add it back. Because repairs do reduce your cash flow, lenders leave them as deductions.

    This distinction matters enormously for how you categorize property improvements. Tax consultant Neil Langlois points out that treating expenditures as capital improvements rather than repairs converts them into depreciable assets. That shift generates future add-backs instead of immediate expense deductions, which preserves your qualifying income on paper.

    The practical implications for borrowers:

    • Repairs expensed immediately reduce your net income dollar for dollar and stay as deductions. Lenders count them against you.
    • Capital improvements depreciated over time reduce your taxable income slowly. Lenders add the annual depreciation back, so the net effect on qualifying income is minimal or positive.
    • Bonus depreciation and Section 179 elections can create large one-year deductions that look alarming on a tax return but are fully added back by underwriters who recognize them as non-cash.
    • Expense categorization strategy should be coordinated between your CPA and your mortgage professional before you file, not after.

    The key takeaway is that the same dollar spent on a property can either hurt or help your mortgage qualification depending entirely on how it is categorized. This is not a gray area. It is a documented underwriting principle that rewards borrowers who plan ahead.

    Alternative qualification strategies when depreciation is not enough

    Sometimes depreciation add-backs improve your qualifying income but still leave you short of what you need to qualify for your target loan amount. Three alternative strategies address this gap directly.

    1. Bank Statement Loans. These programs use 12 to 24 months of bank deposits to derive qualifying income instead of tax returns. For self-employed borrowers whose write-offs reduce reported income below what conventional lenders accept, bank statement mortgages bypass the tax return entirely. The standard expense factor is 50% on business accounts, which can drop to 35–40% with a CPA-certified profit and loss statement. This approach captures actual cash flow rather than accounting income.

    2. DSCR Loans. Debt Service Coverage Ratio loans qualify the property, not the borrower. For real estate investors, the rental income from the subject property is the qualifying income. Your personal income, tax returns, and depreciation schedule are irrelevant. This makes DSCR loans particularly useful for investors who have maximized depreciation write-offs across a large portfolio. You can review DSCR loan options to see how rental cash flow alone can support a new acquisition.

    3. Asset depletion loans. These specialized mortgage products convert liquid assets into imputed income. The calculation applies a haircut to your liquid portfolio and divides the result by the loan term in months. Typical haircuts are 60–70% on retirement accounts and 70% on taxable brokerage accounts, with minimum eligible assets starting at $500,000. A borrower with $1,000,000 in a taxable brokerage account could generate roughly $1,944 per month in imputed income on a 360-month loan term after the 70% haircut. That imputed income can be combined with documented income and depreciation add-backs to clear the qualifying threshold.

    The most effective approach combines all available income streams: tax return income with add-backs, bank statement income if applicable, and asset depletion if you hold substantial liquid assets. Each layer adds to your qualifying total.

    Key Takeaways

    Depreciation increases your qualifying income because lenders add it back as a non-cash expense, giving self-employed borrowers and investors access to larger loan amounts than their tax returns alone would suggest.

    Point Details
    Depreciation is added back Lenders add depreciation to net profit, increasing your qualifying income by up to $2,000 per month.
    Rental income benefits too Schedule E add-backs for depreciation can nearly triple qualifying rental income on a single property.
    Repairs are not added back Only non-cash expenses like depreciation are added back; cash expenses like repairs reduce qualifying income.
    Capital improvements beat repairs Categorizing property work as capital improvements creates depreciable assets that preserve qualifying income.
    Alternative loans fill the gap Bank statement loans, DSCR loans, and asset depletion mortgages qualify borrowers when tax return income falls short.

    What I have learned about depreciation and mortgage planning

    Most borrowers I work with at 1st Nationwide Mortgage discover the depreciation add-back benefit too late. They file their taxes, see a low net income number, and assume they cannot qualify for the mortgage they want. By the time they call me, the tax year is closed and the opportunity to optimize is gone.

    The uncomfortable truth is that tax strategy and mortgage strategy are the same conversation, but most people treat them as separate. Your CPA is focused on minimizing your tax bill. That is their job. But minimizing taxable income and maximizing qualifying income are often in direct conflict. A borrower who takes every available deduction may pay less to the IRS and simultaneously disqualify themselves from the mortgage they need.

    My advice is to have a three-way conversation between yourself, your CPA, and your mortgage professional before you file each year. A good mortgage professional can show your CPA exactly which add-backs will be recognized by underwriters and which deductions will hurt your qualification. That conversation, held in october or november rather than april, changes outcomes.

    The other misunderstanding I see constantly is around bonus depreciation. Borrowers take large Section 179 or bonus depreciation elections, see their net income drop to near zero, and panic. Underwriters who know what they are doing add those back completely. The problem is not the depreciation. The problem is working with a lender who does not understand self-employment income. If you want to see how your actual numbers work, the mortgage qualification calculators at 1st Nationwide Mortgage are a good starting point before you sit down with a loan officer.

    — Chris Arco, NMLS #1281

    How 1st Nationwide Mortgage works with depreciation add-backs

    Self-employed borrowers and real estate investors often qualify for more than they expect once depreciation add-backs are properly applied.

    https://1stnwm.com

    1st Nationwide Mortgage is a direct mortgage banker licensed in 18 states, with an A+ rating from the Better Business Bureau. The team specializes in income structures that conventional lenders misread, including Schedule C and Schedule E borrowers with significant depreciation. Use the qualifying income calculators to estimate your adjusted income before you apply. For investors who want to qualify on rental cash flow without personal income documentation, DSCR loan programs are available with no limit on financed properties. For self-employed borrowers, bank statement loan options use 12 to 24 months of deposits instead of tax returns.

    FAQ

    What is the role of depreciation in mortgage qualification?

    Depreciation is a non-cash expense that lenders add back to your net income when calculating qualifying income. This add-back increases the income figure used to determine how large a mortgage you can receive.

    Does depreciation help or hurt your mortgage application?

    Depreciation helps your mortgage application. Because lenders add it back to net profit, it increases your qualifying income rather than reducing it, unlike cash expenses such as repairs.

    How do lenders calculate rental income with depreciation?

    Lenders use Schedule E, add back depreciation, mortgage interest, taxes, and insurance to net rental income, then apply a 75% factor to gross rents to account for vacancies and maintenance.

    Can I qualify for a mortgage if my tax return shows very low income due to depreciation?

    Yes. Lenders add back depreciation and other non-cash expenses to your reported income. If your qualifying income is still insufficient after add-backs, bank statement loans, DSCR loans, or asset depletion mortgages offer alternative qualification paths.

    What is the difference between depreciation and repairs for mortgage purposes?

    Depreciation is a non-cash expense added back by lenders, so it does not reduce your qualifying income. Repairs are cash expenses that lenders count as real costs, which reduces the income available to support your mortgage payment.

  • Self-Employed Mortgage Qualification Explained for Borrowers

    Self-Employed Mortgage Qualification Explained for Borrowers

    Self-employed mortgage qualification is the process lenders use to verify income and financial stability for borrowers without traditional W-2 employment, relying instead on tax returns, bank statements, and business documents. Unlike salaried workers who submit pay stubs, self-employed borrowers must prove their income through a more detailed paper trail. The core challenge is that tax write-offs reduce reported income, which can limit how much you qualify to borrow even when your business generates strong revenue. Understanding how lenders read your financials is the first step toward getting approved on your terms.

    What documentation do lenders require from self-employed borrowers?

    Lenders verify income for self-employed borrowers through a specific set of documents that prove both income level and business continuity. Standard qualification requires at least two years of self-employment history, typically documented through signed tax returns. That two-year threshold exists because lenders want to see that your income is stable, not a one-time spike.

    The documents most lenders request include:

    • Two years of personal tax returns (Form 1040 with all schedules, including Schedule C for sole proprietors, Schedule E for rental or partnership income, and K-1 forms for S-corp or partnership distributions)
    • Business tax returns for the same two years, using Form 1120S for S-corporations or Form 1065 for partnerships
    • Year-to-date profit and loss statement, ideally prepared or reviewed by a CPA
    • 12–24 months of personal and business bank statements to verify actual cash deposits
    • CPA letter or accountant verification confirming your business is active and ongoing
    • Proof of business ownership, such as a business license, articles of incorporation, or DBA registration

    Each document serves a specific purpose. Tax returns with schedules show your income history, while bank statements confirm that money is actually flowing into your accounts. The CPA letter adds a third-party confirmation that your business is real and operating. Together, these documents give the lender a complete picture of your financial life.

    Pro Tip: If your business is structured as an S-corp or partnership, your personal return alone will not tell the full story. Make sure your CPA prepares clean business returns every year, even if your accountant says you do not legally need them.

    Mortgage officer reviewing income verification with clients

    How do lenders calculate qualifying income for self-employed borrowers?

    Qualifying income for self-employed borrowers is not the same as taxable income. Lenders focus on your actual cash flow, and aggressive tax deductions can significantly reduce the income figure lenders use to qualify you. A business generating $300,000 in revenue might show only $120,000 in net profit after deductions. That $120,000 is what the lender works with, not the $300,000.

    To recover some of that lost income, underwriters apply a process called “add-backs.” Lenders add back certain deductions like depreciation, depletion, and one-time non-recurring expenses to your Schedule C net profit. This increases your qualifying income without changing your tax liability. Common add-backs include:

    • Depreciation on business assets
    • Home office deductions
    • Business use of a vehicle (mileage or actual expenses)
    • One-time losses or extraordinary expenses that will not repeat

    After calculating your qualifying income, lenders apply the debt-to-income ratio, or DTI. DTI is often the most limiting factor for self-employed borrowers because qualifying income is frequently lower than actual cash flow. Most conventional loan programs cap DTI at 43–45%.

    When automated underwriting systems flag a file as too complex, manual underwriting allows a human underwriter to review the full picture. This process takes longer, but it gives borrowers with unusual income patterns, one-time losses, or new client contracts a real chance at approval. Manual underwriting is not a red flag. For self-employed borrowers, it is often the path to a fair decision.

    Infographic showing mortgage income qualification steps

    Pro Tip: Before you apply, ask your CPA to run a “mortgage income analysis.” This is a calculation of what your qualifying income looks like after add-backs, using the same method lenders use. Knowing your number in advance prevents surprises at underwriting.

    What alternative mortgage programs exist for self-employed borrowers?

    When tax returns produce a qualifying income that is too low, alternative mortgage programs fill the gap. The most widely used option is the bank statement loan, a type of non-QM (non-qualified mortgage) product designed specifically for borrowers whose tax returns do not reflect their true earning power.

    Bank statement loans use 12–24 months of deposits to estimate income instead of tax returns. The lender averages your monthly deposits and applies an expense factor to arrive at qualifying income. At 1st Nationwide Mortgage, the standard expense factor on business accounts is 50%, meaning half of your average monthly deposits count as income. That factor can drop to 35–40% if you provide a CPA-certified profit and loss statement, which directly increases your qualifying income. You can use the bank statement income calculator to estimate your number before you apply.

    Here is how bank statement loans compare to conventional loans on key qualification criteria:

    Criteria Conventional loan Bank statement loan
    Income verification Tax returns, W-2s 12–24 months of bank deposits
    Minimum credit score Typically 620+ Typically 620+
    Down payment 3–20% 10–20%
    Self-employment history 2 years required Flexible, often 1–2 years
    DTI calculation Based on tax return income Based on deposit-derived income

    Real estate investors have a separate option: DSCR loans. A DSCR loan qualifies the property based on its rental income, not the borrower’s personal income. If the rent covers the mortgage payment, the loan can be approved without any personal income documentation. This makes DSCR loans particularly useful for landlords and investors who hold properties in LLCs.

    Pro Tip: If you have been self-employed for less than two years but have prior W-2 income in the same field, some lenders will make an exception. A borrower who spent eight years as a salaried graphic designer and then went freelance 14 months ago has a strong case for a conventional loan with the right lender.

    What steps can self-employed borrowers take to improve approval chances?

    Preparation is the single biggest factor in mortgage approval for self-employed borrowers. Starting 12–24 months before you apply gives you time to fix the issues that most commonly derail applications.

    1. Consult a loan officer and CPA together. Talking to a loan officer at least 12 months before applying lets you balance tax savings with the income you need to qualify. Your CPA minimizes taxes. Your loan officer maximizes qualifying income. These goals sometimes conflict, and you need both perspectives before filing your next return.

    2. Balance your deductions. Aggressive write-offs lower your tax bill but also lower your qualifying income. Decide which matters more in the year before you apply. You can always take more deductions after you close.

    3. Pay down existing debts. Reducing your debt load before applying directly improves your DTI. Pay off credit cards, auto loans, or any installment debt you can eliminate without draining your reserves.

    4. Keep your business and personal accounts separate. Commingled accounts create confusion for underwriters. Clean, separate bank statements are much easier to document and verify.

    5. Maintain consistent business performance. A sharp drop in revenue between year one and year two raises underwriting concerns. Lenders average the two years, but a declining trend can trigger additional scrutiny or a denial.

    6. Build your credit score. Most loan programs require a minimum score of 620, but a score above 700 opens better pricing and more program options. Pay all accounts on time and keep credit card balances below 30% of your limit.

    7. Save for reserves. Many lenders require 3–6 months of mortgage payments in savings after closing. Self-employed borrowers with variable income often need to show more. Start building that cushion now.

    For freelancers and 1099 contractors, the 1099 contractor mortgage guide covers additional nuances specific to your income type.

    Key Takeaways

    Self-employed mortgage qualification depends on documenting stable cash flow through tax returns, bank statements, or alternative programs, not on business revenue alone.

    Point Details
    Two-year history is standard Most lenders require two years of self-employment documented through signed tax returns.
    Add-backs increase qualifying income Depreciation and one-time expenses can be added back to net profit to raise your qualifying figure.
    DTI is the most common barrier Paying down debts before applying directly improves your debt-to-income ratio and approval odds.
    Bank statement loans bypass tax returns These non-QM products use 12–24 months of deposits to calculate income, ideal for high-write-off borrowers.
    Early preparation changes outcomes Starting 12–24 months ahead lets you align your tax strategy with your mortgage qualification goals.

    What I have learned after years of working with self-employed borrowers

    The most common mistake I see is borrowers who come in after filing two years of very aggressive returns and then wonder why they cannot qualify for the loan they need. They did everything right from a tax perspective and everything wrong from a mortgage perspective. These two goals require coordination, and most people do not realize that until it is too late to fix it for that tax year.

    The second thing I see constantly is a misunderstanding of the add-back process. Borrowers assume their net profit is their qualifying income. It is not. A good loan officer walks through your Schedule C line by line and recovers income that the tax return buried. That conversation alone can change your qualifying amount by tens of thousands of dollars.

    Manual underwriting gets a bad reputation because it sounds like a problem. It is not. For self-employed borrowers with complex financials, a human underwriter who can read context is often better than an automated system that just sees a number. If your file goes to manual underwriting, that is not a sign you are being rejected. It is a sign someone is actually looking at your situation.

    My honest advice: treat your mortgage application like a two-year project, not a two-week process. The borrowers who qualify smoothly are the ones who planned ahead, kept clean records, and talked to a loan officer before they filed their taxes, not after.

    — Chris Arco, NMLS #1281

    How 1st Nationwide Mortgage helps self-employed borrowers qualify

    Self-employed borrowers have more options than most realize. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, which means faster decisions and direct control over the underwriting process.

    https://1stnwm.com

    For borrowers whose tax returns show too little income, bank statement loans use 12–24 months of deposits to calculate qualifying income instead. For real estate investors, DSCR loans qualify the property on rental income alone, with no personal income documentation required. 1st Nationwide Mortgage is licensed in 18 states and holds a BBB A+ rating. Whether you are a freelancer, a business owner, or a landlord building a portfolio, the right loan program exists for your situation. Contact a loan officer to review your documents and identify the best path forward.

    FAQ

    How long do you need to be self-employed to get a mortgage?

    Most lenders require at least two years of self-employment history, documented through signed tax returns. Exceptions exist for borrowers with prior W-2 income in the same field.

    Can high tax write-offs prevent mortgage approval?

    Yes. Aggressive deductions reduce the net income lenders use to calculate your qualifying amount, which can lower your maximum loan size even when your business revenue is strong.

    What is a bank statement loan and who qualifies?

    A bank statement loan uses 12–24 months of bank deposits to estimate income instead of tax returns. Self-employed borrowers with a minimum 620 credit score and 10–20% down payment typically qualify.

    What is the add-back process in mortgage underwriting?

    Add-backs are deductions from your tax return, such as depreciation or one-time expenses, that lenders add back to your net profit to increase your qualifying income. This process can meaningfully raise the loan amount you qualify for.

    How does a DSCR loan work for self-employed real estate investors?

    A DSCR loan qualifies based on the rental income of the property being financed, not the borrower’s personal income. If the property’s rent covers the mortgage payment, approval is possible without any personal income documentation.