Author: Christopher Arco

  • Depreciation’s Role in Mortgage Qualification Explained

    Depreciation’s Role in Mortgage Qualification Explained

    Depreciation is defined as a non-cash accounting expense that lenders add back to your reported income when calculating how much mortgage you qualify for. This add-back is the core of the role of depreciation in mortgage qualification: it increases your effective qualifying income without requiring you to earn more money. Self-employed borrowers and rental property investors benefit most from this treatment, because aggressive tax write-offs often push their reported net income far below their actual cash flow. Understanding how lenders apply these adjustments, and how to position your finances accordingly, can meaningfully increase your borrowing capacity.

    How does depreciation affect mortgage qualification for self-employed borrowers?

    Lenders do not take your tax return net income at face value. For self-employed borrowers, underwriters analyze Schedule C and add back non-cash expenses like depreciation, amortization, and depletion to arrive at a more accurate picture of your cash flow. These add-backs can increase monthly qualifying income by $500 to $2,000 depending on your assets and business scale. That range is significant because even a $500 monthly increase can raise your qualifying loan amount by tens of thousands of dollars.

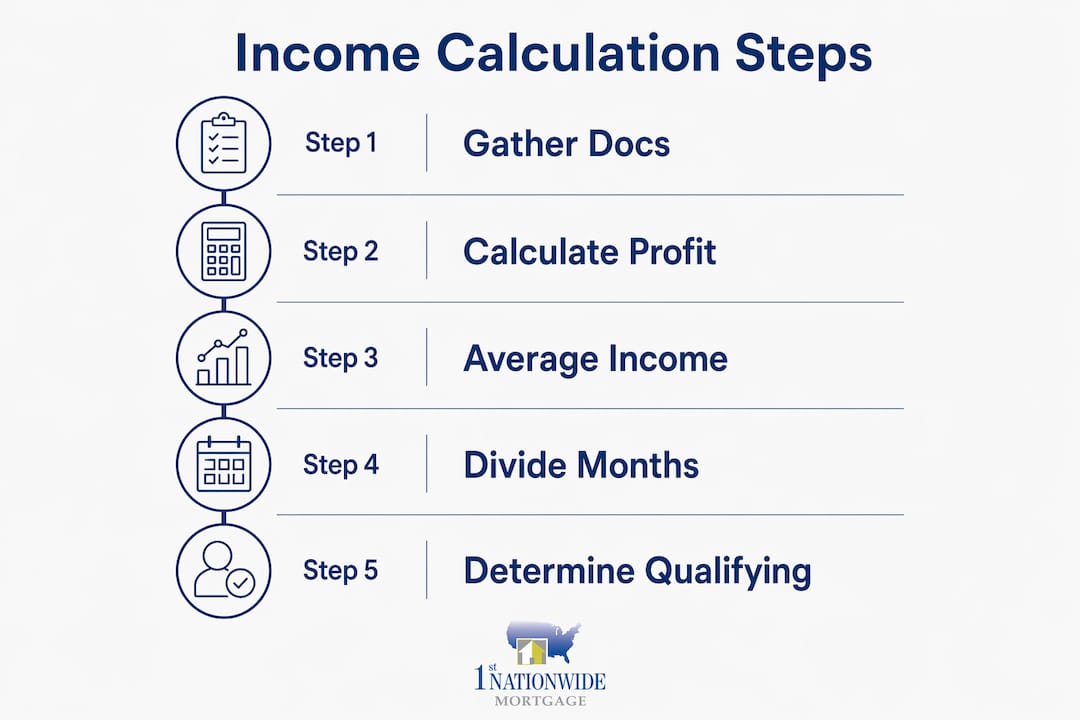
    The standard underwriting process for self-employment income involves two key steps. First, lenders average two years of net profit after adding back non-cash expenses. Second, they exclude non-recurring income that will not continue. This two-year average smooths out volatile income years and gives underwriters a defensible number to work with.

    Here is what lenders typically add back from Schedule C:

    • Depreciation: The most common add-back for business owners with equipment, vehicles, or property.
    • Amortization: Write-offs for intangible assets like patents or goodwill.
    • Depletion: Relevant for borrowers in natural resource industries.
    • Casualty losses: One-time losses from events like fires or floods.
    • Business use of home: Non-cash home expenses added back because they do not represent real cash leaving your account.

    Each of these items reduces your taxable income on paper. None of them reduces the actual cash you have available to make a mortgage payment.

    Pro Tip: If you are self-employed and planning to apply for a mortgage within the next 12 months, ask your CPA to run a projection showing your qualifying income with all add-backs applied. That number, not your net profit, is what the lender will use.

    How rental property income is calculated with depreciation add-backs

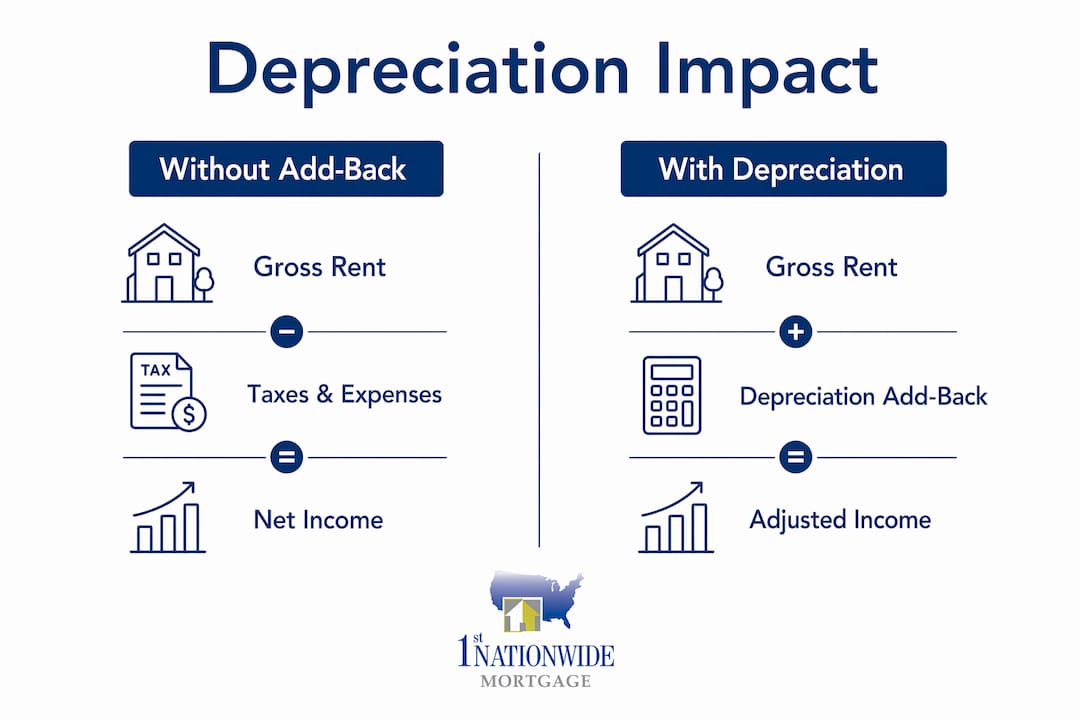
    Rental property owners face a similar dynamic, but the mechanics work through Schedule E instead of Schedule C. Lenders calculate net rental income by starting with gross rents and then adding back depreciation, mortgage interest, taxes, and insurance. The result is a cash flow figure that reflects what the property actually generates, not what the tax return shows after depreciation.

    Hands reviewing rental income tax documents

    One important adjustment: lenders typically count only 75% of gross rent. The 25% reduction accounts for vacancies and maintenance costs. Even with that haircut, the depreciation add-back often more than compensates, because rental property depreciation can be substantial on a $300,000 or $400,000 asset.

    Infographic comparing mortgage income with and without depreciation

    The table below shows how depreciation add-backs change the qualifying income calculation on a single rental property:

    Income Component Without Add-Back With Depreciation Add-Back
    Gross monthly rent $2,400 $2,400
    75% vacancy adjustment $1,800 $1,800
    Net income after expenses $400 $400
    Depreciation add-back $0 $700
    Qualifying monthly income $400 $1,100

    The difference between $400 and $1,100 per month in qualifying income is not a rounding error. On a 30-year mortgage at a typical rate, that gap can represent $100,000 or more in additional borrowing capacity. Investors with multiple rental properties see this effect multiply across their entire portfolio.

    Pro Tip: When you own multiple rentals, the combined depreciation add-backs across all Schedule E properties can dramatically shift your debt-to-income ratio. Run the numbers on your full portfolio before assuming you do not qualify.

    Why lenders treat depreciation differently than repairs

    Depreciation and repairs both reduce your taxable income, but lenders treat them in opposite ways. Depreciation is a non-cash expense. Repairs are recurring cash expenditures that you actually pay out of pocket. Because depreciation does not reduce your real cash flow, lenders add it back. Because repairs do reduce your cash flow, lenders leave them as deductions.

    This distinction matters enormously for how you categorize property improvements. Tax consultant Neil Langlois points out that treating expenditures as capital improvements rather than repairs converts them into depreciable assets. That shift generates future add-backs instead of immediate expense deductions, which preserves your qualifying income on paper.

    The practical implications for borrowers:

    • Repairs expensed immediately reduce your net income dollar for dollar and stay as deductions. Lenders count them against you.
    • Capital improvements depreciated over time reduce your taxable income slowly. Lenders add the annual depreciation back, so the net effect on qualifying income is minimal or positive.
    • Bonus depreciation and Section 179 elections can create large one-year deductions that look alarming on a tax return but are fully added back by underwriters who recognize them as non-cash.
    • Expense categorization strategy should be coordinated between your CPA and your mortgage professional before you file, not after.

    The key takeaway is that the same dollar spent on a property can either hurt or help your mortgage qualification depending entirely on how it is categorized. This is not a gray area. It is a documented underwriting principle that rewards borrowers who plan ahead.

    Alternative qualification strategies when depreciation is not enough

    Sometimes depreciation add-backs improve your qualifying income but still leave you short of what you need to qualify for your target loan amount. Three alternative strategies address this gap directly.

    1. Bank Statement Loans. These programs use 12 to 24 months of bank deposits to derive qualifying income instead of tax returns. For self-employed borrowers whose write-offs reduce reported income below what conventional lenders accept, bank statement mortgages bypass the tax return entirely. The standard expense factor is 50% on business accounts, which can drop to 35–40% with a CPA-certified profit and loss statement. This approach captures actual cash flow rather than accounting income.

    2. DSCR Loans. Debt Service Coverage Ratio loans qualify the property, not the borrower. For real estate investors, the rental income from the subject property is the qualifying income. Your personal income, tax returns, and depreciation schedule are irrelevant. This makes DSCR loans particularly useful for investors who have maximized depreciation write-offs across a large portfolio. You can review DSCR loan options to see how rental cash flow alone can support a new acquisition.

    3. Asset depletion loans. These specialized mortgage products convert liquid assets into imputed income. The calculation applies a haircut to your liquid portfolio and divides the result by the loan term in months. Typical haircuts are 60–70% on retirement accounts and 70% on taxable brokerage accounts, with minimum eligible assets starting at $500,000. A borrower with $1,000,000 in a taxable brokerage account could generate roughly $1,944 per month in imputed income on a 360-month loan term after the 70% haircut. That imputed income can be combined with documented income and depreciation add-backs to clear the qualifying threshold.

    The most effective approach combines all available income streams: tax return income with add-backs, bank statement income if applicable, and asset depletion if you hold substantial liquid assets. Each layer adds to your qualifying total.

    Key Takeaways

    Depreciation increases your qualifying income because lenders add it back as a non-cash expense, giving self-employed borrowers and investors access to larger loan amounts than their tax returns alone would suggest.

    Point Details
    Depreciation is added back Lenders add depreciation to net profit, increasing your qualifying income by up to $2,000 per month.
    Rental income benefits too Schedule E add-backs for depreciation can nearly triple qualifying rental income on a single property.
    Repairs are not added back Only non-cash expenses like depreciation are added back; cash expenses like repairs reduce qualifying income.
    Capital improvements beat repairs Categorizing property work as capital improvements creates depreciable assets that preserve qualifying income.
    Alternative loans fill the gap Bank statement loans, DSCR loans, and asset depletion mortgages qualify borrowers when tax return income falls short.

    What I have learned about depreciation and mortgage planning

    Most borrowers I work with at 1st Nationwide Mortgage discover the depreciation add-back benefit too late. They file their taxes, see a low net income number, and assume they cannot qualify for the mortgage they want. By the time they call me, the tax year is closed and the opportunity to optimize is gone.

    The uncomfortable truth is that tax strategy and mortgage strategy are the same conversation, but most people treat them as separate. Your CPA is focused on minimizing your tax bill. That is their job. But minimizing taxable income and maximizing qualifying income are often in direct conflict. A borrower who takes every available deduction may pay less to the IRS and simultaneously disqualify themselves from the mortgage they need.

    My advice is to have a three-way conversation between yourself, your CPA, and your mortgage professional before you file each year. A good mortgage professional can show your CPA exactly which add-backs will be recognized by underwriters and which deductions will hurt your qualification. That conversation, held in october or november rather than april, changes outcomes.

    The other misunderstanding I see constantly is around bonus depreciation. Borrowers take large Section 179 or bonus depreciation elections, see their net income drop to near zero, and panic. Underwriters who know what they are doing add those back completely. The problem is not the depreciation. The problem is working with a lender who does not understand self-employment income. If you want to see how your actual numbers work, the mortgage qualification calculators at 1st Nationwide Mortgage are a good starting point before you sit down with a loan officer.

    — Chris Arco, NMLS #1281

    How 1st Nationwide Mortgage works with depreciation add-backs

    Self-employed borrowers and real estate investors often qualify for more than they expect once depreciation add-backs are properly applied.

    https://1stnwm.com

    1st Nationwide Mortgage is a direct mortgage banker licensed in 18 states, with an A+ rating from the Better Business Bureau. The team specializes in income structures that conventional lenders misread, including Schedule C and Schedule E borrowers with significant depreciation. Use the qualifying income calculators to estimate your adjusted income before you apply. For investors who want to qualify on rental cash flow without personal income documentation, DSCR loan programs are available with no limit on financed properties. For self-employed borrowers, bank statement loan options use 12 to 24 months of deposits instead of tax returns.

    FAQ

    What is the role of depreciation in mortgage qualification?

    Depreciation is a non-cash expense that lenders add back to your net income when calculating qualifying income. This add-back increases the income figure used to determine how large a mortgage you can receive.

    Does depreciation help or hurt your mortgage application?

    Depreciation helps your mortgage application. Because lenders add it back to net profit, it increases your qualifying income rather than reducing it, unlike cash expenses such as repairs.

    How do lenders calculate rental income with depreciation?

    Lenders use Schedule E, add back depreciation, mortgage interest, taxes, and insurance to net rental income, then apply a 75% factor to gross rents to account for vacancies and maintenance.

    Can I qualify for a mortgage if my tax return shows very low income due to depreciation?

    Yes. Lenders add back depreciation and other non-cash expenses to your reported income. If your qualifying income is still insufficient after add-backs, bank statement loans, DSCR loans, or asset depletion mortgages offer alternative qualification paths.

    What is the difference between depreciation and repairs for mortgage purposes?

    Depreciation is a non-cash expense added back by lenders, so it does not reduce your qualifying income. Repairs are cash expenses that lenders count as real costs, which reduces the income available to support your mortgage payment.

  • Self-Employed Mortgage Qualification Explained for Borrowers

    Self-Employed Mortgage Qualification Explained for Borrowers

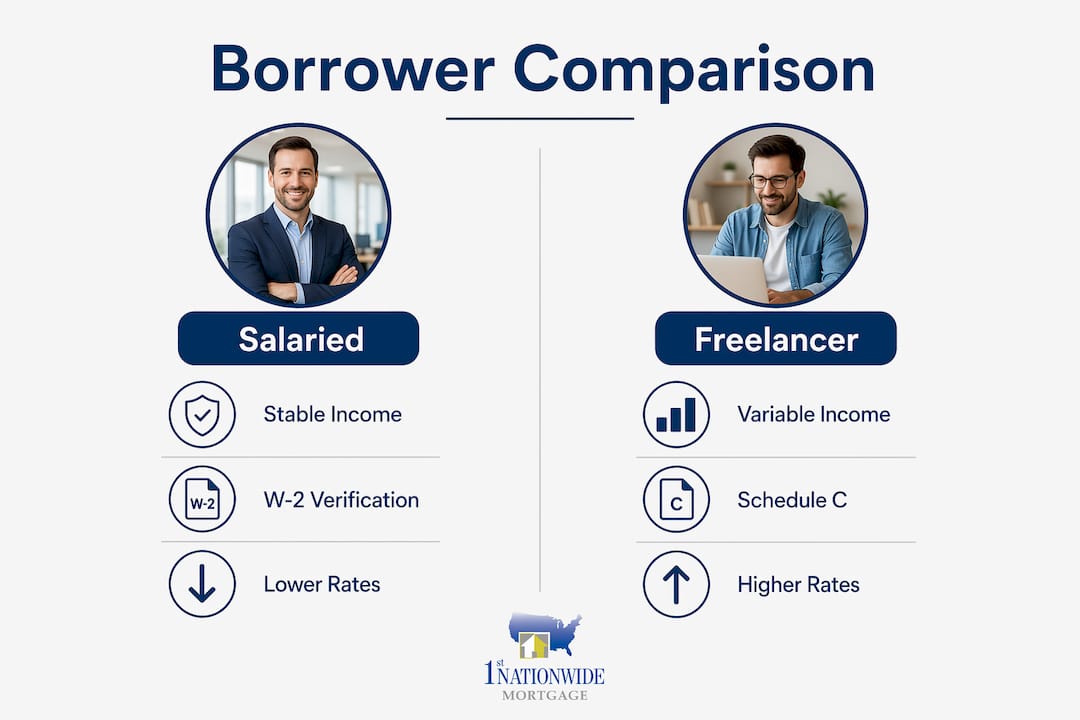
    Self-employed mortgage qualification is the process lenders use to verify income and financial stability for borrowers without traditional W-2 employment, relying instead on tax returns, bank statements, and business documents. Unlike salaried workers who submit pay stubs, self-employed borrowers must prove their income through a more detailed paper trail. The core challenge is that tax write-offs reduce reported income, which can limit how much you qualify to borrow even when your business generates strong revenue. Understanding how lenders read your financials is the first step toward getting approved on your terms.

    What documentation do lenders require from self-employed borrowers?

    Lenders verify income for self-employed borrowers through a specific set of documents that prove both income level and business continuity. Standard qualification requires at least two years of self-employment history, typically documented through signed tax returns. That two-year threshold exists because lenders want to see that your income is stable, not a one-time spike.

    The documents most lenders request include:

    • Two years of personal tax returns (Form 1040 with all schedules, including Schedule C for sole proprietors, Schedule E for rental or partnership income, and K-1 forms for S-corp or partnership distributions)
    • Business tax returns for the same two years, using Form 1120S for S-corporations or Form 1065 for partnerships
    • Year-to-date profit and loss statement, ideally prepared or reviewed by a CPA
    • 12–24 months of personal and business bank statements to verify actual cash deposits
    • CPA letter or accountant verification confirming your business is active and ongoing
    • Proof of business ownership, such as a business license, articles of incorporation, or DBA registration

    Each document serves a specific purpose. Tax returns with schedules show your income history, while bank statements confirm that money is actually flowing into your accounts. The CPA letter adds a third-party confirmation that your business is real and operating. Together, these documents give the lender a complete picture of your financial life.

    Pro Tip: If your business is structured as an S-corp or partnership, your personal return alone will not tell the full story. Make sure your CPA prepares clean business returns every year, even if your accountant says you do not legally need them.

    Mortgage officer reviewing income verification with clients

    How do lenders calculate qualifying income for self-employed borrowers?

    Qualifying income for self-employed borrowers is not the same as taxable income. Lenders focus on your actual cash flow, and aggressive tax deductions can significantly reduce the income figure lenders use to qualify you. A business generating $300,000 in revenue might show only $120,000 in net profit after deductions. That $120,000 is what the lender works with, not the $300,000.

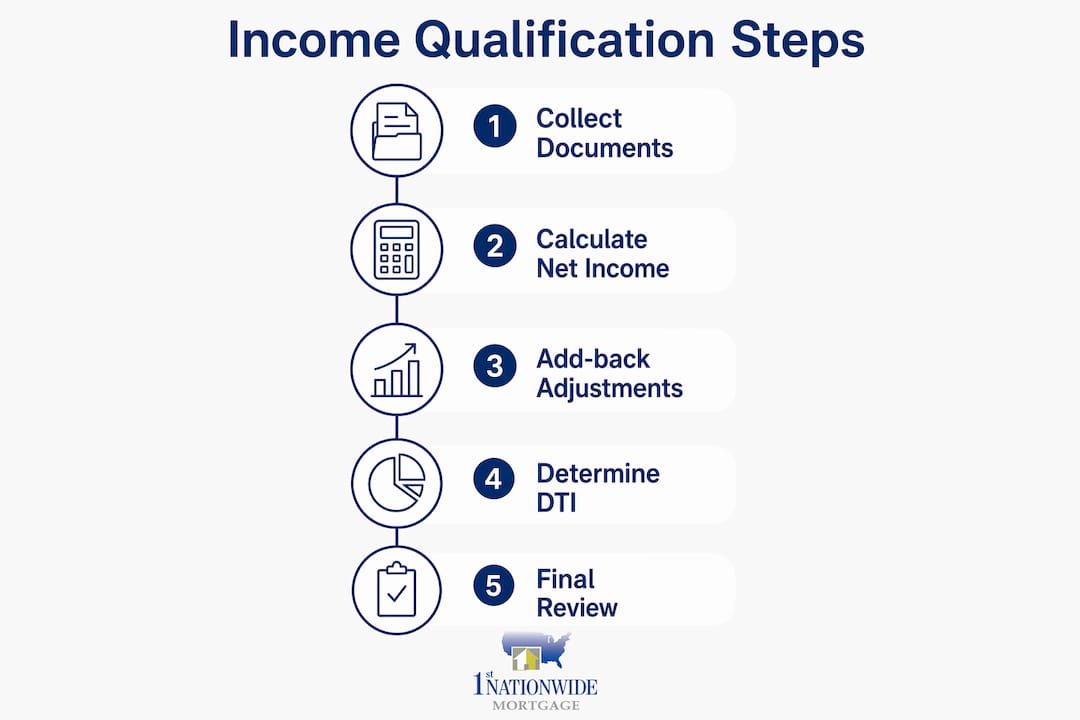
    To recover some of that lost income, underwriters apply a process called “add-backs.” Lenders add back certain deductions like depreciation, depletion, and one-time non-recurring expenses to your Schedule C net profit. This increases your qualifying income without changing your tax liability. Common add-backs include:

    • Depreciation on business assets
    • Home office deductions
    • Business use of a vehicle (mileage or actual expenses)
    • One-time losses or extraordinary expenses that will not repeat

    After calculating your qualifying income, lenders apply the debt-to-income ratio, or DTI. DTI is often the most limiting factor for self-employed borrowers because qualifying income is frequently lower than actual cash flow. Most conventional loan programs cap DTI at 43–45%.

    When automated underwriting systems flag a file as too complex, manual underwriting allows a human underwriter to review the full picture. This process takes longer, but it gives borrowers with unusual income patterns, one-time losses, or new client contracts a real chance at approval. Manual underwriting is not a red flag. For self-employed borrowers, it is often the path to a fair decision.

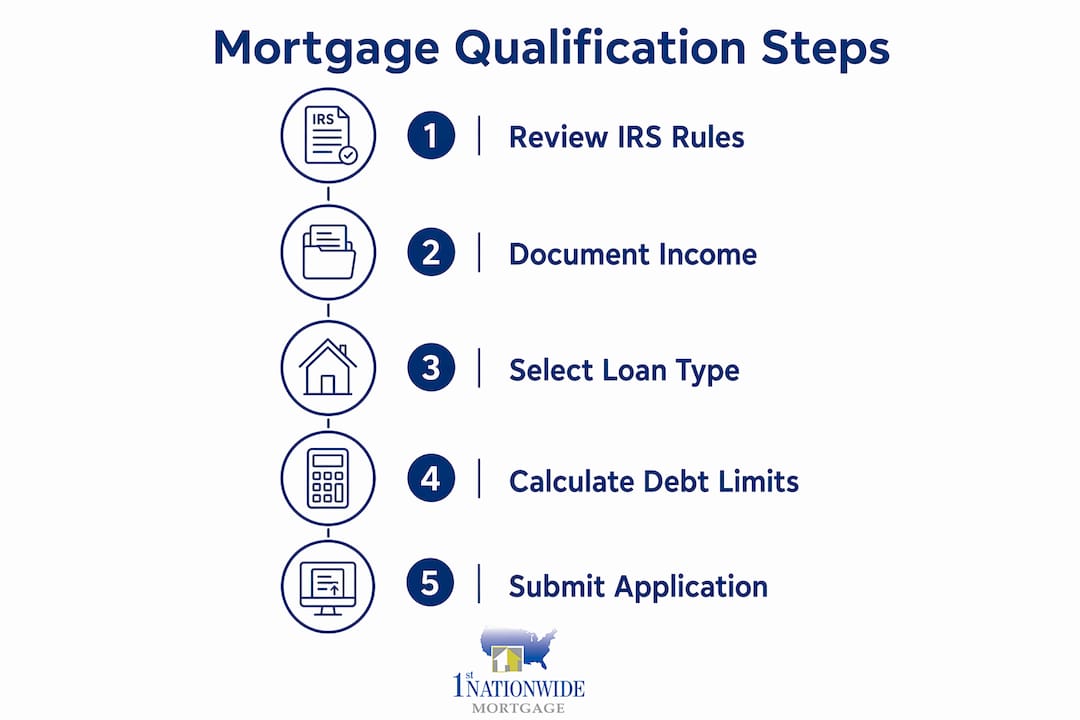
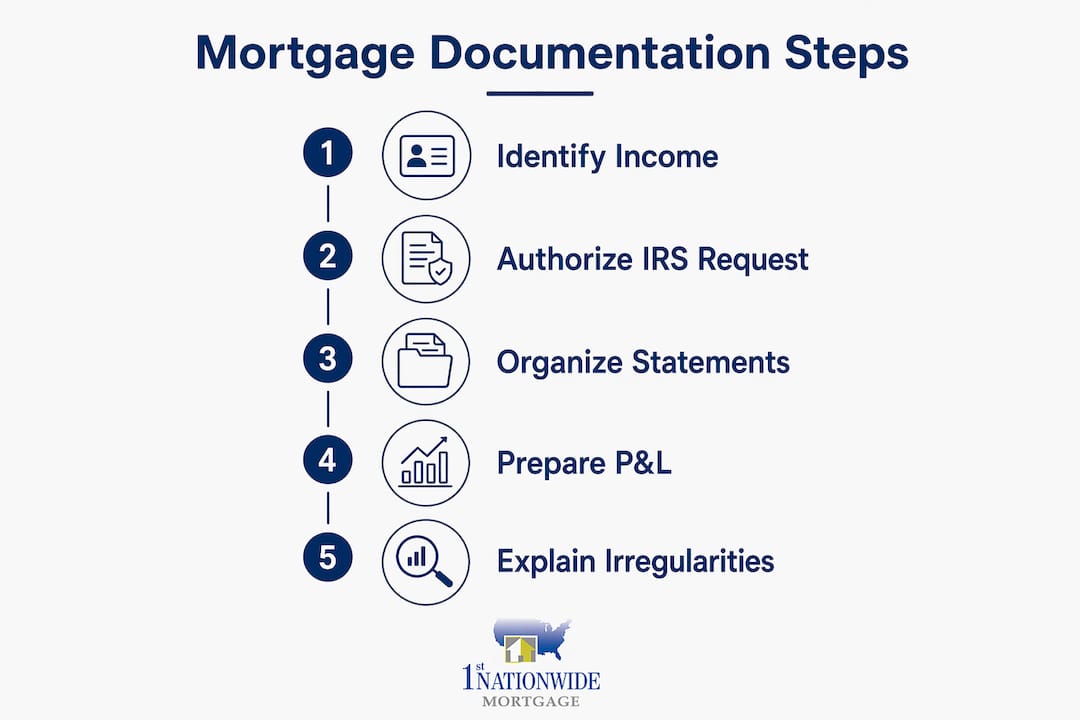
    Infographic showing mortgage income qualification steps

    Pro Tip: Before you apply, ask your CPA to run a “mortgage income analysis.” This is a calculation of what your qualifying income looks like after add-backs, using the same method lenders use. Knowing your number in advance prevents surprises at underwriting.

    What alternative mortgage programs exist for self-employed borrowers?

    When tax returns produce a qualifying income that is too low, alternative mortgage programs fill the gap. The most widely used option is the bank statement loan, a type of non-QM (non-qualified mortgage) product designed specifically for borrowers whose tax returns do not reflect their true earning power.

    Bank statement loans use 12–24 months of deposits to estimate income instead of tax returns. The lender averages your monthly deposits and applies an expense factor to arrive at qualifying income. At 1st Nationwide Mortgage, the standard expense factor on business accounts is 50%, meaning half of your average monthly deposits count as income. That factor can drop to 35–40% if you provide a CPA-certified profit and loss statement, which directly increases your qualifying income. You can use the bank statement income calculator to estimate your number before you apply.

    Here is how bank statement loans compare to conventional loans on key qualification criteria:

    Criteria Conventional loan Bank statement loan
    Income verification Tax returns, W-2s 12–24 months of bank deposits
    Minimum credit score Typically 620+ Typically 620+
    Down payment 3–20% 10–20%
    Self-employment history 2 years required Flexible, often 1–2 years
    DTI calculation Based on tax return income Based on deposit-derived income

    Real estate investors have a separate option: DSCR loans. A DSCR loan qualifies the property based on its rental income, not the borrower’s personal income. If the rent covers the mortgage payment, the loan can be approved without any personal income documentation. This makes DSCR loans particularly useful for landlords and investors who hold properties in LLCs.

    Pro Tip: If you have been self-employed for less than two years but have prior W-2 income in the same field, some lenders will make an exception. A borrower who spent eight years as a salaried graphic designer and then went freelance 14 months ago has a strong case for a conventional loan with the right lender.

    What steps can self-employed borrowers take to improve approval chances?

    Preparation is the single biggest factor in mortgage approval for self-employed borrowers. Starting 12–24 months before you apply gives you time to fix the issues that most commonly derail applications.

    1. Consult a loan officer and CPA together. Talking to a loan officer at least 12 months before applying lets you balance tax savings with the income you need to qualify. Your CPA minimizes taxes. Your loan officer maximizes qualifying income. These goals sometimes conflict, and you need both perspectives before filing your next return.

    2. Balance your deductions. Aggressive write-offs lower your tax bill but also lower your qualifying income. Decide which matters more in the year before you apply. You can always take more deductions after you close.

    3. Pay down existing debts. Reducing your debt load before applying directly improves your DTI. Pay off credit cards, auto loans, or any installment debt you can eliminate without draining your reserves.

    4. Keep your business and personal accounts separate. Commingled accounts create confusion for underwriters. Clean, separate bank statements are much easier to document and verify.

    5. Maintain consistent business performance. A sharp drop in revenue between year one and year two raises underwriting concerns. Lenders average the two years, but a declining trend can trigger additional scrutiny or a denial.

    6. Build your credit score. Most loan programs require a minimum score of 620, but a score above 700 opens better pricing and more program options. Pay all accounts on time and keep credit card balances below 30% of your limit.

    7. Save for reserves. Many lenders require 3–6 months of mortgage payments in savings after closing. Self-employed borrowers with variable income often need to show more. Start building that cushion now.

    For freelancers and 1099 contractors, the 1099 contractor mortgage guide covers additional nuances specific to your income type.

    Key Takeaways

    Self-employed mortgage qualification depends on documenting stable cash flow through tax returns, bank statements, or alternative programs, not on business revenue alone.

    Point Details
    Two-year history is standard Most lenders require two years of self-employment documented through signed tax returns.
    Add-backs increase qualifying income Depreciation and one-time expenses can be added back to net profit to raise your qualifying figure.
    DTI is the most common barrier Paying down debts before applying directly improves your debt-to-income ratio and approval odds.
    Bank statement loans bypass tax returns These non-QM products use 12–24 months of deposits to calculate income, ideal for high-write-off borrowers.
    Early preparation changes outcomes Starting 12–24 months ahead lets you align your tax strategy with your mortgage qualification goals.

    What I have learned after years of working with self-employed borrowers

    The most common mistake I see is borrowers who come in after filing two years of very aggressive returns and then wonder why they cannot qualify for the loan they need. They did everything right from a tax perspective and everything wrong from a mortgage perspective. These two goals require coordination, and most people do not realize that until it is too late to fix it for that tax year.

    The second thing I see constantly is a misunderstanding of the add-back process. Borrowers assume their net profit is their qualifying income. It is not. A good loan officer walks through your Schedule C line by line and recovers income that the tax return buried. That conversation alone can change your qualifying amount by tens of thousands of dollars.

    Manual underwriting gets a bad reputation because it sounds like a problem. It is not. For self-employed borrowers with complex financials, a human underwriter who can read context is often better than an automated system that just sees a number. If your file goes to manual underwriting, that is not a sign you are being rejected. It is a sign someone is actually looking at your situation.

    My honest advice: treat your mortgage application like a two-year project, not a two-week process. The borrowers who qualify smoothly are the ones who planned ahead, kept clean records, and talked to a loan officer before they filed their taxes, not after.

    — Chris Arco, NMLS #1281

    How 1st Nationwide Mortgage helps self-employed borrowers qualify

    Self-employed borrowers have more options than most realize. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, which means faster decisions and direct control over the underwriting process.

    https://1stnwm.com

    For borrowers whose tax returns show too little income, bank statement loans use 12–24 months of deposits to calculate qualifying income instead. For real estate investors, DSCR loans qualify the property on rental income alone, with no personal income documentation required. 1st Nationwide Mortgage is licensed in 18 states and holds a BBB A+ rating. Whether you are a freelancer, a business owner, or a landlord building a portfolio, the right loan program exists for your situation. Contact a loan officer to review your documents and identify the best path forward.

    FAQ

    How long do you need to be self-employed to get a mortgage?

    Most lenders require at least two years of self-employment history, documented through signed tax returns. Exceptions exist for borrowers with prior W-2 income in the same field.

    Can high tax write-offs prevent mortgage approval?

    Yes. Aggressive deductions reduce the net income lenders use to calculate your qualifying amount, which can lower your maximum loan size even when your business revenue is strong.

    What is a bank statement loan and who qualifies?

    A bank statement loan uses 12–24 months of bank deposits to estimate income instead of tax returns. Self-employed borrowers with a minimum 620 credit score and 10–20% down payment typically qualify.

    What is the add-back process in mortgage underwriting?

    Add-backs are deductions from your tax return, such as depreciation or one-time expenses, that lenders add back to your net profit to increase your qualifying income. This process can meaningfully raise the loan amount you qualify for.

    How does a DSCR loan work for self-employed real estate investors?

    A DSCR loan qualifies based on the rental income of the property being financed, not the borrower’s personal income. If the property’s rent covers the mortgage payment, approval is possible without any personal income documentation.

  • Non-QM Loans for Real Estate Investors: 2026 Guide

    Non-QM Loans for Real Estate Investors: 2026 Guide

    Non-QM loans are specialized mortgage products that fall outside the qualified mortgage rules set by the Consumer Financial Protection Bureau, and they are exactly why real estate investors need non-QM loans to grow portfolios that conventional financing cannot reach. Traditional lenders rely on W-2s and debt-to-income ratios that penalize investors with complex tax returns, multiple properties, or self-employment income. Non-QM loans replace those rigid requirements with flexible alternatives: bank statements, rental cash flow, and asset-based income. The result is a financing path built for how investors actually earn money, not how a salaried employee does.

    Why real estate investors need non-QM loans

    Non-QM loans are defined as mortgages that do not meet the Consumer Financial Protection Bureau’s qualified mortgage standards. Those standards require lenders to verify a borrower’s ability to repay using strict documentation, typically W-2s and tax returns. Investors who write off significant expenses often show taxable income far below their actual cash flow, which disqualifies them under conventional rules.

    The core advantage is flexibility in income verification. Non-QM programs accommodate borrowers with unconventional income by using bank statements, property cash flow analysis, and 1099 earnings instead of tax returns. That flexibility is not a workaround. It is a recognition that real estate investors operate differently from salaried borrowers.

    Investor and banker discussing non-QM loans

    Self-employed investors face a specific problem: aggressive tax deductions reduce reported income, which tanks their debt-to-income ratio. A self-employed borrower can qualify for more than $100,000 above what a traditional tax return assessment would allow through non-QM programs. That gap represents real deals that would otherwise fall apart at the underwriting stage.

    What are the key features and requirements of non-QM loans?

    Non-QM loans carry distinct underwriting criteria that differ from conventional mortgages in three main areas: income documentation, credit requirements, and down payment expectations.

    Income documentation methods

    Bank statement loans use 12–24 months of deposits to calculate qualifying income. DSCR loans skip personal income entirely and qualify the borrower based on the property’s rental income relative to its debt obligations. Asset-based income programs count liquid assets as a proxy for monthly earnings. Each method targets a different investor profile.

    Credit score and down payment requirements

    Credit score requirements for non-QM loans are more flexible than conventional mortgages but still matter. A minimum score of 620 is typical for programs like bank statement loans at 1st Nationwide Mortgage. Down payments generally run higher. Non-QM loans typically require down payments of 15%–30%, compared to the median 23% seen for repeat buyers in 2025. That higher upfront requirement reflects the lender’s increased risk exposure.

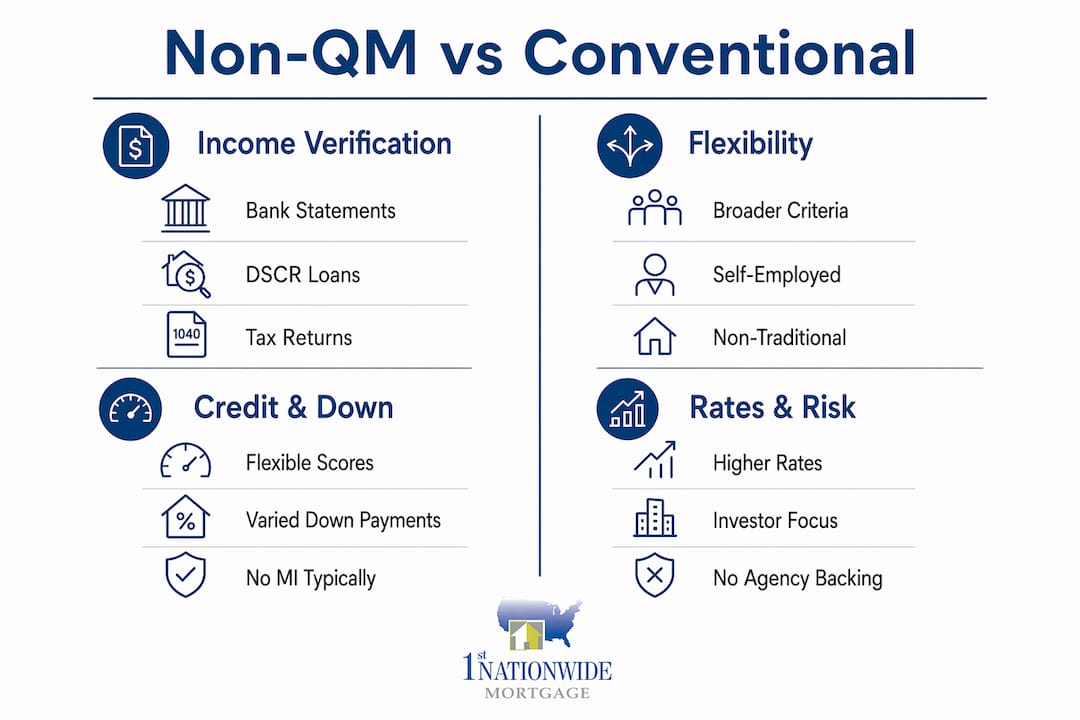
    Infographic comparing Non-QM and Conventional loans

    Interest rates and risk profile

    Non-QM loans are not backed by government agencies such as Fannie Mae or Freddie Mac. That absence of agency backing places underwriting risk directly on the lender, which drives rates higher. Investors should expect rates approximately 1%–2% above conventional mortgage rates. That premium is the cost of qualifying without traditional income documentation.

    Pro Tip: Use a mortgage calculator to model the impact of a 1%–2% rate premium on your projected rental yield before committing to a non-QM loan. The math often still works in your favor when the alternative is no financing at all.

    Feature Non-QM Loans Conventional Loans
    Income verification Bank statements, DSCR, assets W-2s and tax returns
    Down payment 15%–30% 3%–20%
    Interest rate 1%–2% above conventional Standard market rate
    Agency backing None Fannie Mae or Freddie Mac
    Credit minimum Typically 620+ Typically 620–640+

    How do non-QM loan types differ for investors?

    The major non-QM loan types include Bank Statement Loans, DSCR Loans, 1099 Loans, and NONI Loans. Each one solves a different income documentation problem.

    Bank Statement Loans use 12–24 months of business or personal bank deposits to calculate qualifying income. A standard expense factor of 50% applies to business accounts, which can drop to 35%–40% with a CPA-certified profit and loss statement. These loans work best for self-employed investors whose write-offs reduce their taxable income well below actual earnings.

    DSCR Loans are built specifically for real estate investors. The lender measures the property’s debt service coverage ratio, which compares rental income to the monthly mortgage payment. Qualifying based on property cash flow means your personal income never enters the equation. DSCR loans also work for LLCs and carry no limit on the number of financed properties, which makes them ideal for portfolio growth.

    1099 Loans serve independent contractors and freelancers who receive 1099 income rather than W-2s. The lender uses one to two years of 1099 forms to calculate qualifying income. This product directly addresses what a non-QM loan for contractors looks like in practice: income verification without requiring tax returns that show heavy deductions.

    NONI Loans (No Income, No Asset) serve foreign nationals and borrowers with no documentable income. NONI programs can reach up to $3.5 million, making them viable for high-value investment acquisitions where traditional documentation simply does not exist.

    • Bank Statement Loans: best for self-employed investors with high write-offs
    • DSCR Loans: best for qualifying on rental income with no personal income docs
    • 1099 Loans: best for contractors and freelancers with 1099 earnings
    • NONI Loans: best for foreign nationals or borrowers with no documentable income

    Why do real estate investors specifically benefit from non-QM loans?

    The benefits of non-QM loans for investors go beyond just qualifying. They change what deals are possible and how fast you can move on them.

    1. Qualify on property income, not personal income. DSCR loans let the rental property carry its own weight. If the property generates enough cash flow to cover the mortgage, you qualify. This removes the ceiling that personal debt-to-income ratios impose on active investors.

    2. Grow your portfolio without hitting a loan limit. Conventional financing caps the number of financed properties at ten. Non-QM loans carry no such restriction. Investors can finance multiple properties simultaneously, which directly supports portfolio expansion strategies.

    3. Close faster on time-sensitive deals. Non-QM lenders work with alternative documentation from the start, which reduces back-and-forth during underwriting. Faster processing means you can act on off-market deals or competitive listings before other buyers.

    4. Protect your personal financial profile. Qualifying through DSCR or bank statements keeps your personal tax returns and W-2 history out of the equation. That separation is valuable for investors who want to keep their business and personal finances distinct.

    5. Access higher loan amounts as a self-employed borrower. Because non-QM programs use actual deposits or rental income rather than taxable income, the qualifying loan amount more accurately reflects your real financial position.

    Pro Tip: If you invest in Texas, non-QM loan programs in Texas include both bank statement and DSCR options through 1st Nationwide Mortgage, which is licensed in the state and operates as a direct lender, not a broker.

    What are the costs and risks of non-QM loans for investors?

    Non-QM loans carry real trade-offs that every investor should weigh before committing.

    • Higher interest rates reduce monthly cash flow. A 1%–2% rate premium on a $500,000 loan adds $5,000–$10,000 per year in interest costs. That affects your net operating income and cap rate calculations.
    • Larger down payments increase upfront capital requirements. Higher down payments of 15%–30% tie up more equity per property, which can slow portfolio expansion if capital is limited.
    • No agency backing means lenders set their own underwriting standards. Those standards vary across lenders, and terms can shift based on market conditions or the lender’s risk appetite.
    • Mortgage insurance is generally not required for non-QM loans the way it is for conventional loans with less than 20% down. Lenders manage risk through higher rates and larger down payments instead. That distinction matters when you are calculating total loan costs.
    • Variable lender quality is a real risk. Because non-QM loans are not standardized by agency guidelines, the quality of underwriting and loan terms depends heavily on the lender you choose.

    The best way to manage these risks is to work with a direct lender, not a broker, and to run your numbers on projected rental income before applying. A deal that pencils out at a conventional rate may still work at a non-QM rate if the property cash flow is strong enough.

    Key Takeaways

    Non-QM loans are the most practical financing path for real estate investors who cannot qualify under conventional income documentation rules, and DSCR loans are the single most investor-specific tool in that category.

    Point Details
    Non-QM definition Mortgages outside CFPB qualified mortgage rules, using alternative income verification.
    DSCR loans qualify on cash flow Property rental income replaces personal income docs, with no cap on financed properties.
    Higher costs are the trade-off Expect rates 1%–2% above conventional and down payments of 15%–30%.
    Multiple loan types serve different needs Bank Statement, DSCR, 1099, and NONI loans each target a distinct investor profile.
    No agency backing shifts risk Lenders set their own standards, so lender quality and terms vary significantly.

    What I’ve learned after years of non-QM lending

    I have worked with real estate investors long enough to see a clear pattern. The investors who struggle with non-QM financing are almost always the ones who approach it like a conventional loan with looser rules. It is not that. It is a fundamentally different underwriting philosophy.

    The biggest mistake I see is investors applying for a DSCR loan on a property with weak rental income projections, assuming the flexible documentation will compensate. It will not. The property still has to carry the debt. If the rent does not cover the payment at a reasonable coverage ratio, the loan does not close. Flexibility in documentation does not mean flexibility in math.

    The second mistake is ignoring the rate premium until it is too late. A 1%–2% higher rate sounds manageable in the abstract, but on a $700,000 investment property, that is real money every month. Run the numbers before you apply, not after you are under contract.

    What I find genuinely encouraging about the non-QM market in 2026 is that lender competition has improved product quality. Investors today have access to cleaner loan structures, more transparent terms, and faster closings than they did five years ago. The market has matured. That is good news for anyone building a portfolio through alternative financing.

    My honest advice: use non-QM financing as a deliberate tool, not a fallback. If DSCR fits your deal, use it because it fits, not because you ran out of conventional options.

    — Chris Arco, NMLS #1281

    Non-QM financing options at 1st Nationwide Mortgage

    Real estate investors who need flexible financing have direct access to non-QM programs through 1st Nationwide Mortgage, a direct mortgage banker licensed in 18 states and rated BBB A+.

    https://1stnwm.com

    1st Nationwide Mortgage offers DSCR loans for investors that qualify on rental income with no personal income documentation required, and bank statement loan programs that use 12–24 months of deposits for self-employed borrowers. Both programs work for LLCs and carry no limit on financed properties. If you are ready to run the numbers on your next acquisition, the investment property mortgage page at 1st Nationwide Mortgage is the right starting point. Speak directly with a licensed loan officer who understands how investors qualify, not just how salaried borrowers do.

    FAQ

    What is a non-QM loan?

    A non-QM loan is a mortgage that does not meet the Consumer Financial Protection Bureau’s qualified mortgage standards. It uses alternative income verification methods such as bank statements, rental cash flow, or 1099 earnings instead of W-2s and tax returns.

    What is the role of credit score in non-QM loans?

    Credit score still matters in non-QM underwriting, with most programs requiring a minimum score of 620. A higher score can improve your rate, but non-QM lenders weigh income documentation and property cash flow alongside credit history.

    Do non-QM loans require mortgage insurance?

    Non-QM loans generally do not require mortgage insurance the way conventional loans do for borrowers with less than 20% down. Lenders manage their risk through higher interest rates and larger down payment requirements instead.

    What is a non-QM loan for contractors?

    A non-QM loan for contractors is typically a 1099 loan that uses one to two years of 1099 income forms to calculate qualifying income. It eliminates the need for tax returns that often show deductions reducing a contractor’s apparent income below what lenders would accept.

    Are non-QM loans available in Texas?

    Yes, non-QM loans including bank statement and DSCR programs are available in Texas through lenders like 1st Nationwide Mortgage, which is licensed in the state and operates as a direct lender.

  • Top 5 Enrichloans.com Alternatives Providers 2026

    Top 5 Enrichloans.com Alternatives Providers 2026

    Finding a non-QM mortgage lender that approves complex income profiles without vague eligibility requirements creates delays and wasted applications. Most alternatives require traditional tax return verification or only publish opaque pricing without clear qualification tools. This guide compares five non-QM mortgage lenders on product range, approval process, and eligibility so brokers and loan officers can match a provider to their client’s needs without guesswork.

    Table of Contents

    1st Nationwide Mortgage

    https://1stnwm.com

    At a Glance

    The vendor advertises serving 41+ states for DSCR loans and 49+ states for NONI loans. The vendor states it has operated since 2005 and focuses on personalized service for self-employed borrowers and investors. The vendor also advertises fast closing timelines, often 21–30 days.

    Core Features

    1st Nationwide Mortgage centers on non‑QM and investor mortgage programs and supports a wide mix of conventional and alternative products. Offerings include bank statement loans, DSCR loans, NONI loans, bridge and commercial loans, FHA, VA, USDA, jumbo, reverse mortgages, and HELOCs. The lender pairs these product options with dedicated loan officers and claims quicker-than-average closing timelines for qualified files.

    Key Differentiator

    The firm’s clearest distinction is its focus on non‑QM and investor underwriting while covering most U.S. states for investor and foreign national programs. It emphasizes bank statement and DSCR qualification flows that avoid traditional tax return income measures. That combination targets self‑employed borrowers and real estate investors who need alternative income verification.

    Pros

    The vendor states over 20 years of specialized mortgage lending experience, which supports its non‑QM expertise. The team understands bank statement underwriting and DSCR math, so borrowers with heavy write offs or complex rental cash flows get tailored qualification paths. Licensing across many states and dedicated loan officers make the process more hands on than a large retail bank.

    Cons

    • Rates typically run slightly above conventional mortgages because of the non‑QM product mix.

    Who It’s For

    Self‑employed borrowers who cannot show qualifying income on tax returns will find the bank statement paths relevant. Real estate investors who prefer DSCR underwriting and LLC financing will benefit from the investor focus. Foreign nationals without U.S. income documentation can also access NONI programs where licensing permits.

    Unique Value Proposition

    Bank statement loans that calculate qualifying income from 12–24 months of deposits let applicants show cash flow instead of reported taxable income. The program applies a standard expense factor of 50% on business accounts, and that factor can drop to 35–40% with a CPA‑certified profit and loss statement. Minimum credit requirements and down payment expectations are explicit, with borrowers often needing at least a 620 score and 10–20% down depending on program details.

    Real World Use Case

    A freelance consultant with large deductions and low reported taxable income can use 12–24 months of bank deposits to document qualifying income. That approach lets the consultant secure a purchase mortgage that a conventional processor would likely decline. A small investor can qualify a rental property using DSCR underwriting without including personal wages.

    Pricing

    Pricing is not publicly specified on the site. The firm positions rates as generally competitive, though they usually run slightly higher than traditional lenders because non‑QM and investor products carry additional risk pricing.

    Website: https://1stnwm.com

    Angel Oak Mortgage Solutions

    https://angeloakms.com

    At a Glance

    A full stack broker approval and closing platform sits alongside quick qualification tools and educational content. Angel Oak targets brokers who place borrowers with complex income, credit, or property profiles into non QM programs. The platform pairs toolsets for fast prequalification with training resources for brokers expanding their product mix.

    Core Features

    The platform combines non QM loan programs with a broker portal that handles approval and closing workflows. It includes quick qualification and eligibility calculators, webinars for continuing education, and rate and LTV mortgage calculators for underwriting scenarios. These elements work together to help brokers assess eligibility and move cases toward closing.

    Key Differentiator

    The main distinction is the broker-centric toolset that couples instant qualification aids with ongoing education. Angel Oak packages underwriting resources, calculators, and regular webinars inside a single broker-facing environment. That mix aims to reduce back and forth between originator and investor while keeping brokers updated on program changes.

    Pros

    Specialization in flexible non QM lending makes the platform useful when conventional documentation fails. The broker resources include approval workflows, calculators, and educational webinars that shorten the learning curve for less familiar loan products. Market experience with underserved borrower types and alternative property situations gives brokers program options they may not find at mainstream banks.

    Cons

    • No detailed public pricing for programs or broker fees.
    • Limited public detail on specific loan terms and published rates.
    • Some programs may require complex documentation or underwriting steps for certain borrower profiles.

    Who It’s For

    Mortgage brokers and lending professionals focused on self employed, non standard income, or credit challenged borrowers will find relevant options. Brokers who need a centralized approval and closing workflow for non QM files will get the most value. Real estate professionals handling investment properties will also benefit from the product mix.

    Real World Use Case

    A broker uses the portal to run a quick qualification for a self employed borrower using bank statement analysis and then routes the file through the platform for approval. The broker streams calculator outputs and webinar insights to the loan officer handling the file. The result is a single place to prequalify and progress a non QM mortgage case toward closing.

    Pricing

    Not applicable — informational only. Angel Oak does not publish detailed program pricing on the website. Brokers should contact their Angel Oak sales or broker support representative for fee schedules and program costs.

    Website: https://angeloakms.com

    LendSure

    https://lendsure.com

    At a Glance

    LendSure reports a pre-underwriting process that delivers approvals and pricing within 24 hours. This claim targets mortgage brokers who need faster non-QM responses than typical wholesale channels. The quick turn time supports faster lock decisions and earlier borrower communications.

    Core Features

    LendSure focuses on a broad suite of non-QM loan programs, including bank statement loans, asset depletion, foreign national, fix-and-flip, and jumbo options. The company pairs that product range with a formal pre-underwriting workflow, broker education resources, and calculators plus white papers for training. In-house underwriting and support aim to help brokers place complex files with fewer follow-ups.

    Key Differentiator

    The standout element is the pre-underwriting workflow that claims approvals and pricing in one business day. That rapid quote process reduces uncertainty for loan officers managing self-employed or investor borrowers. Brokers who need fast conditional pricing will find this workflow central to LendSure’s offering.

    Pros

    LendSure centers on the non-QM niche and builds an extensive product suite around those needs. The firm supports brokers with training programs, onboarding webinars, and management trainee options that shorten the learning curve. Fast pre-approval and funding times, combined with in-house underwriting, reduce back-and-forth on unusual income profiles.

    Cons

    • Not suitable for borrowers who require traditional conforming loans. LendSure focuses on non-QM pathways only.

    • Geographic coverage specifics are not listed publicly. Brokers must contact LendSure to confirm licensing in their state.

    • Pricing and interest rate details are not posted on the website. Rates and fees require direct outreach for a quote.

    When It May Not Fit

    If you place mostly conventional conforming loans, LendSure will not match that workflow. Brokers who rely on transparent online rate sheets may find the lack of public pricing cumbersome. Small teams that cannot invest time in training or onboarding programs could prefer a provider with more public documentation. For lenders needing nationwide licensing details on the website, the limited public information requires phone or email follow up.

    Who It’s For

    Mortgage brokers and loan officers focused on self-employed borrowers, real estate investors, and foreign nationals will get the most value. Professionals who place bank statement loans or fix-and-flip financing and who need flexible underwriting should evaluate LendSure. It suits brokers who prefer partner training and a hands-on underwriting relationship.

    Real World Use Case

    A mortgage broker places a bank statement loan for a self-employed borrower who has low reported taxable income. The broker submits deposits and supporting documents into LendSure’s pre-underwriting queue. The broker receives conditional pricing and approval quickly and communicates a firm plan to the borrower, allowing a faster close timeline.

    Pricing

    LendSure does not publish pricing on the public site. Loan officers must contact the team to get rate and fee quotes for specific products and states. Pricing is provided case by case during the pre-underwriting or quoting process.

    Website: https://lendsure.com

    NewPoint Mortgage LLC

    https://newpointmortgage.com

    At a Glance

    Loan amounts up to $3.5 million and LTVs up to 90% on select programs. NewPoint targets non-QM paths such as bank statement, DSCR, ITIN, and P&L only loans for complex borrower profiles. The vendor advertises some programs can close within 10 days. The platform is built to help brokers place cases that standard underwriting will not accept.

    Core Features

    NewPoint’s platform lists bank statement, DSCR, and ITIN workflows along with P&L only options in one product menu. It covers purchase and refinance for investment, owner occupied, and second home property types and accepts mixed use properties. The company pairs larger loan sizes with state licensing and resources for brokers and loan officers.

    Key Differentiator

    NewPoint concentrates on alternative qualification paths for underserved borrowers while keeping decision timelines focused and predictable. The program mix aligns with investors, foreign nationals, and self employed borrowers who cannot use conventional tax return income. That timeline for fast approvals helps brokers convert complex files into clear submission options.

    Pros

    A broad catalog of non standard workflows lets brokers match documentation to client income realities. Fast decisioning and the vendor cited quick closings let originators offer time sensitive commitments when clients need speed. Multi state licensing and broker resources reduce friction for teams placing specialty loans across jurisdictions.

    Cons

    • Limited to non QM loan solutions rather than standard conforming products.
    • Some programs require minimum credit scores, often in the 620 to 680 range.
    • Interest rates and fees can be higher than conventional loans for comparable credit profiles.
    • Availability varies by state licensing and borrower credit profile, which can block certain cases.

    When It May Not Fit

    If you need conventional conforming products this platform is not a match. Rate sensitive borrowers seeking the lowest possible interest will likely prefer traditional lenders. Teams that operate only in states where NewPoint is not licensed will face coverage gaps for placement.

    Who It’s For

    Mortgage brokers and loan officers serving self employed clients, foreign nationals, and real estate investors will find the platform useful. Originators who package non standard files for underwriting and need a roster of alternative programs will use it to expand placement options. The ideal user understands specialty documentation workflows.

    Real World Use Case

    A self employed borrower with minimal tax return income qualified under bank statement rules to purchase an investment property. The broker collected 12 to 24 months of deposits and matched the file to NewPoint’s documentation checklist. That timeline let the file move from submission to conditional approval quickly, allowing a timely closing.

    Pricing

    Not applicable for public pricing. The site lists program details but does not publish standard pricing or rate sheets, so brokers must request pricing on a case by case basis.

    Website: https://newpointmortgage.com

    SoFi

    https://sofi.com

    At a Glance

    Members can earn crypto match promotions and lottery style bonus rewards, a distinct perk tied to account activity. The platform combines banking, loans, investing, insurance, and crypto trading within a single platform. SoFi Plus members receive tiered interest yields and reward boosts that create clear cost and return differences between basic and paid membership.

    Core Features

    SoFi bundles deposit accounts, personal and student loans, mortgages, investing, insurance, and crypto trading behind a single account and dashboard. The platform pairs member perks with personalized financial advice and rewards programs that include cash back, crypto matches, and lottery style bonus promotions. Modular product access means you can open accounts, refinance debt, and invest without separate vendors.

    Key Differentiator

    SoFi’s defining angle is its membership tier model. SoFi Plus layers tiered savings yields, enhanced rewards, and event access on top of the basic product set. That membership structure ties return enhancement directly to recurring engagement across banking, lending, and investing products.

    Pros

    SoFi brings many financial services under one login, which reduces the number of vendors you manage and centralizes statements and tools. Its rewards programs increase value for active members who hold products across accounts and who enroll in SoFi Plus. Flexible loan terms and lack of prepayment penalties simplify payoff planning for borrowers. The platform also offers accessible financial planning and coaching resources that help members set goals and act on them.

    Cons

    • Complexity of many products can overwhelm new members during onboarding, especially when choosing between similar loan and account options.
    • Several top rewards and higher yields require SoFi Plus membership or other eligibility criteria.
    • Promotional offers and specific rates change frequently and can carry renewal conditions.
    • Physical branch presence is limited, so people who prefer face to face banking will rely on online support only.

    When It May Not Fit

    If you need in-person branch service for complex transactions, this primarily digital platform will not meet that need. If you want consistently high rates without a membership requirement, the tiered model will feel restrictive. Businesses or highly specialized investors who require institutional accounts or advanced trading tools will find SoFi’s retail focus limiting.

    Who It’s For

    Tech savvy consumers who prefer a single vendor for banking, lending, and investing and who value rewards and member perks. It fits borrowers who want flexible loan terms and savers who can justify a membership for higher yields. It also suits people who want integrated crypto access alongside traditional accounts.

    Real World Use Case

    A young professional consolidates student loans, opens a savings account, and sets up regular stock and crypto investments within the same dashboard. They enroll in SoFi Plus to boost savings yields and earn extra rewards on recurring deposits and credit card activity.

    Pricing

    Access to the platform is free. Individual products carry their own rates, fees, and eligibility rules, and SoFi Plus is offered as a paid tier that unlocks higher yields, rewards boosts, and select member perks.

    Website: https://sofi.com

    Comparison of alternatives

    In evaluating leading providers in the non-QM mortgage lending field, several dimensions of distinction emerge based on their services and targeted audiences. While each firm caters to specific niches within the alternative mortgage landscape, their individual strengths provide varied options for borrowers, brokers, and investors.

    Distinctions in state coverage and lender expertise

    1st Nationwide Mortgage stands out prominently for its extensive state licensing, particularly covering 49+ states for NONI loans. This coverage makes it a versatile option for borrowers residing across various jurisdictions. Furthermore, its specialized expertise in managing unconventional income verification, such as DSCR and bank statement qualifications, underscores its appeal to self-employed borrowers or investors with unique financial circumstances. By comparison, while other providers might cater to similar clients, their ability to serve across as many states varies, often requiring further inquiry into licensing specifics.

    Resources and speed aiding brokers

    Angel Oak Mortgage Solutions shines with its broker-centric platform that not only enables fast qualification calculators but also provides educational tools like webinars for continued professional growth. This makes them highly attractive to mortgage brokers managing non-QM files. LendSure claims a competitive edge concerning speed, offering pricing and approvals within one business day through its pre-underwriting process. Brokers needing rapid decision timelines will find this feature beneficial.

    Best fit

    • Borrowers seeking broad state coverage of NONI programs and tailored underwriting will find 1st Nationwide Mortgage’s extensive reach and expertise aligned with their needs.
    • Brokers requiring centralized tools and resources for managing non-QM files will benefit from Angel Oak Mortgage Solutions’ dedicated broker platform.
    • Brokers needing rapid conditional approvals paired with ongoing training should consider LendSure’s expedited pre-underwriting capabilities.

    Our pick

    For borrowers prioritizing state access and experienced non-QM underwriting, 1st Nationwide Mortgage emerges as the choice. Its ability to handle unconventional income verification with broad NONI loan availability makes it an resource for self-employed individuals or real estate investors. However, other alternatives like Angel Oak Mortgage Solutions and LendSure provide substantial benefits tailored to mortgage brokers and those prioritizing speed over geographical coverage.

    To assist in selecting the most appropriate non-QM mortgage lender, here is a comparison of leading providers based on their primary strengths and attributes:

    Provider Core Feature Key Differentiator Best For Notable Limitation
    1st Nationwide Mortgage Comprehensive non-QM loan offerings Network covering most U.S. states Self-employed borrowers needing alternative income verification Slightly higher rates than conventional lenders
    Angel Oak Mortgage Solutions Broker-centric approval tools Broker education and training resources Brokers handling complex borrower profiles No public pricing or detailed loan terms
    LendSure Quick pre-underwriting approvals 24-hour pricing and approval workflows Brokers needing fast non-QM responses Focuses exclusively on non-QM loans
    NewPoint Mortgage LLC Loan options with high LTV and large balances Fast approval and timeline predictability Real estate investors and self-employed clients Not ideal for borrowers needing conforming loans
    SoFi Integrated financial services platform Comprehensive membership reward system Tech-savvy individuals seeking diverse financial tools Limited physical branch presence

    Challenges with Income Verification for Self-Employed Borrowers and Investors

    Qualifying for a mortgage can be difficult when traditional tax returns do not reflect your actual income. This situation often affects self-employed borrowers and real estate investors who write off many expenses or rely on rental income reported under different entities. These challenges make conventional underwriting models difficult to satisfy, limiting loan options.

    1st Nationwide Mortgage offers tailored solutions that use bank statement loans with 12 to 24 months of deposits, DSCR loans that focus on property rental income, and NONI loans for foreign nationals without standard income documents. These programs consider your true cash flow rather than just reported taxable income, providing more flexible qualification paths.

    Learn more about these specialized loan options and the benefits of working with a direct lender at 1st Nationwide Mortgage. See how alternative documentation methods can help you qualify without relying solely on tax returns or traditional income verification.

    FAQ

    What is the benefit of using 1st Nationwide Mortgage for self-employed borrowers?

    1st Nationwide Mortgage offers bank statement loans that assess qualifying income from 12–24 months of deposits. This approach supports self-employed borrowers who struggle to meet traditional tax return requirements, allowing them to secure financing based on actual cash flow.

    How does 1st Nationwide Mortgage compare to LendSure for non-QM loans?

    LendSure provides a fast pre-underwriting process that delivers approvals and pricing within 24 hours, which can be ideal for brokers needing quick responses. In contrast, 1st Nationwide Mortgage focuses on personalized service for self-employed borrowers and real estate investors, providing customized qualification paths tailored to their unique income situations.

    What unique feature does 1st Nationwide Mortgage have for foreign nationals?

    1st Nationwide Mortgage’s NONI loan program allows foreign nationals without U.S. income documentation to qualify, as long as licensing permits. This makes it a viable option for non-residents seeking financing in the U.S.

    Can borrowers expect lower interest rates with 1st Nationwide Mortgage?

    Borrowers may find that rates with 1st Nationwide Mortgage typically run slightly above conventional mortgages. This is due to the non-QM product mix, which often carries added risk pricing.

    What is the minimum credit score required by 1st Nationwide Mortgage?

    1st Nationwide Mortgage generally requires a minimum credit score of 620 for most of its programs. This requirement can vary depending on specific loan details, so borrowers should verify their eligibility based on their situation.

  • Top 3 fhahandbook.com Alternatives for Income Verification 2026

    Top 3 fhahandbook.com Alternatives for Income Verification 2026

    Verifying income without standard tax documentation often leads to denied mortgage options for self-employed professionals and real estate investors. Many non QM lenders require additional paperwork, lack digital workflows, or do not offer accurate upfront rate or fee information. This comparison shows which bank statement or DSCR loan provider matches your documentation and process needs for a non-qualified mortgage.

    Table of Contents

    1st Nationwide Mortgage

    https://1stnwm.com

    At a Glance

    Qualifies borrowers using 12–24 months of bank deposits instead of tax returns. 1st Nationwide Mortgage reports this method as its standard for bank statement loans. That approach helps self employed borrowers whose tax returns understate cash flow.

    Core Features

    1st Nationwide Mortgage is a direct mortgage banker, not a broker, founded and operated by Christopher Arco, NMLS #1281. The company reports it is licensed in 18 states and holds a BBB A+ rating. Loan programs include bank statement loans, DSCR investor loans, NONI, FHA, VA, USDA, conventional, and jumbo options.

    Key Differentiator

    The firm focuses exclusively on non QM and investor loans and underwrites income from deposits and property cash flow. That specialty lets underwriters accept bank deposits and rental cash flow instead of standard tax based income. The vendor reports over 20 years of industry experience supporting this underwriting approach.

    Pros

    Flexible qualification methods work for self employed borrowers who lack conventional tax documentation. Investor borrowers can use DSCR loans where rental income qualifies the loan without personal income verification. The vendor advertises lending in 41+ states for investor and DSCR loans, and it offers many government and jumbo programs.

    Cons

    • Higher interest rates for non QM and investor programs compared with conventional mortgages.

    Who It’s For

    You are a self employed professional with large business write offs who cannot show adequate taxable income. You are a real estate investor who needs DSCR financing or wants loans for LLC owned properties. You are a foreign national or someone without traditional income documentation seeking mortgage options.

    Unique Value Proposition

    According to the company, standard bank statement underwriting applies a 50% expense factor on business accounts. It can drop to 35–40% with a CPA certified profit and loss statement. That math raises qualifying income for borrowers whose tax returns show low net profit. For investors, DSCR underwriting relies on property cash flow instead of the borrower’s personal income, which simplifies qualification for rental portfolios.

    Real World Use Case

    A photographer with large business deductions provided 12 months of deposits to prove steady monthly cash flow. That evidence replaced tax based income and produced a mortgage approval where conventional underwriting declined. Loan terms required a down payment and underwriting review specific to bank statement files.

    Pricing

    Pricing varies by program. Non QM and investor loans generally have higher rates and fees than conventional products. Exact rates and lender fees require a direct quote and underwriting review.

    Website: https://1stnwm.com

    NewPoint Mortgage

    https://newpointmortgage.com

    At a Glance

    The site combines a broad menu of non QM product links with a broker resource library and unexpected travel and lifestyle posts. That mix makes it a repository for loan officers who need quick product references and printable broker materials. Individual borrowers will find less direct guidance.

    Core Features

    NewPoint Mortgage lists multiple non QM programs including P&L Only, Bank Statement, DSCR, foreign national, ITIN, stand alone second lien, and multi family options. The site also hosts broker tools such as how TOS, flyers, matrices, forms, and a company directory, plus dedicated contact channels for scenario questions, locks, appraisals, and funding. It includes travel and lifestyle blog content that does not relate to mortgage products.

    Key Differentiator

    NewPoint Mortgage centers on broker enablement. The site groups many alternative qualifying programs in one place and pairs those product links with downloadable broker resources and direct contact points for underwriting or funding questions. That focus makes it faster for brokers to match unusual borrower profiles to potential non QM paths.

    Pros

    The product set covers the common non QM categories brokers request, so you can find P&L only and bank statement options in one place. The resource library supplies matrices, forms, and printable flyers that save time when preparing client packages. Multiple contact channels for scenarios, locks, and appraisals reduce back and forth by directing questions to the correct team.

    Cons

    • Limited product detail: many program pages link to general descriptions without full eligibility rules or sample loan scenarios.
    • Broker focus: the site is organized for loan officers and brokers rather than direct consumer shopping or application flows.
    • Distracting content: travel and lifestyle posts appear alongside broker tools and can make navigation feel unfocused.

    When It May Not Fit

    If you are an individual borrower who wants step by step application instructions and consumer facing disclosures, this site will not serve that need well. If you prefer an online portal that accepts consumer applications and returns automated preapprovals, this site lacks that workflow. If you need fully documented product matrices with pricing and fee schedules, those specifics are not consistently available on the site.

    Who It’s For

    Mortgage brokers and loan officers searching for alternative qualifying options will find this resource useful. Sales teams assembling pitch materials and brokers building case files for self employed or foreign national borrowers will benefit from the matrices and contact points. Individual borrowers should work through a broker to access these programs.

    Real World Use Case

    A broker has a self employed client who cannot use tax returns to show income. The broker reviews the bank statement and P&L links on NewPoint Mortgage, downloads the matrix, and calls the designated scenario channel to confirm a documentation checklist. That process shortens the path to an underwriter conversation.

    Pricing

    Pricing and compensation details are not published on the website and appear to be set per scenario. Brokers should contact NewPoint Mortgage directly to request product pricing, fee schedules, and lock desk procedures before submitting a file.

    Website: https://newpointmortgage.com

    Griffin Funding

    https://griffinfunding.com

    At a Glance

    Griffin Funding reports over $3.6 billion funded. The company focuses on digital mortgage workflows for self-employed borrowers, real estate investors, and veterans. It emphasizes fast closings and tailored underwriting for complex income profiles.

    Core Features

    Griffin Funding combines a range of mortgage products including bank statement loans, DSCR loans, home equity loans, and VA mortgages into a single digital application. The lender uses in-house underwriting supported by AI-driven tools to process applications and pull documentation faster. Nationwide servicing across multiple states keeps the product accessible to remote investors and self-employed borrowers.

    Key Differentiator

    The vendor advertises an AI-driven in-house underwriting platform that targets non-traditional borrower profiles and complex loan cases. That tech is paired with flexible manual overlays from dedicated underwriters so files that fail automated rules can still move forward. The combined approach prioritizes speed without discarding human review for edge cases.

    Pros

    Underwriting rules are designed for borrowers with nonstandard documentation, which helps self-employed applicants whose tax returns understate cash flow. A fully digital application and dedicated loan officers reduce back-and-forth and often shorten the time to pre-approval and closing. Specialized programs for investors and veterans mean the product set matches several common financing needs for rental purchases, cash-out equity, and VA refinancing.

    Cons

    • Limited public detail on interest rates and fees makes cost comparisons difficult when shopping multiple lenders.
    • Brand recognition is lower than large national banks, which may affect borrower comfort with long-term servicing or secondary market perceptions.
    • Marketing material does not include explicit side-by-side rate comparisons with competitors, so price transparency depends on requesting a quote.

    When It May Not Fit

    Borrowers who prefer a traditional bank relationship and local branch access will likely find Griffin Funding less familiar. If you want immediate published rate sheets or fee schedules, this lender may not meet that need. Applicants who require heavy counseling on loan features might prefer a lender with larger retail footprint.

    Who It’s For

    Self-employed professionals who lack standard W2 documentation and need bank statement or alternative income underwriting. Real estate investors who qualify on property cash flow rather than personal income. Veterans and active military personnel seeking VA mortgage options through a digitally managed process.

    Real World Use Case

    A self-employed consultant uses Griffin Funding to apply with 12 months of business bank statements instead of tax returns. The file moves through the digital portal, then through AI-assisted underwriting, and receives a tailored loan recommendation. The borrower closes with financing appropriate for a rental property purchase without traditional income verification.

    Pricing

    Pricing is not specified in the available materials and likely varies by loan program, credit profile, and property type. Expect to request a personalized loan estimate to get exact rates, fees, and closing cost details.

    Website: https://griffinfunding.com

    Comparing Non-Qualified Mortgage Lenders

    Explore your options in non-qualified mortgage lending by evaluating their loan programs, expertise, and suitability for specific needs.

    Product Name Offered Programs Key Differentiator Best For Pricing Notable Limitation
    1st Nationwide Mortgage Bank Statement, DSCR, Government, Jumbo Deposit and Property Cash Flow Underwriting Self-employed professionals and real estate investors Price not published Higher rates compared to conventional mortgages
    NewPoint Mortgage P&L Only, Bank Statement, DSCR, Multi-Family Broker-oriented tools and resources Mortgage brokers seeking alternative qualification options Price not published Geared towards brokers, limited direct consumer application support
    Griffin Funding Bank Statement, DSCR, VA, Equity Loans AI-driven in-house underwriting Self-employed and veteran borrowers Price not published Limited rate transparency, requiring direct quotes for comparison

    When Traditional Income Verification Limits Your Mortgage Options

    Many self-employed professionals and real estate investors find conventional tax return requirements do not reflect their true cash flow. This issue often results in lower qualifying income that keeps you from securing the mortgage you need. Underwriting that assesses 12 to 24 months of bank deposits instead of tax returns offers a more accurate picture of your income, especially when business write-offs reduce reported profits.

    1st Nationwide Mortgage specializes in bank statement and DSCR loans that validate income using your actual bank deposits and rental property cash flow. This approach helps self-employed borrowers and investors who struggle with traditional documentation requirements. Whether you are a self-employed professional, a real estate investor, or a foreign national without conventional income proof, their loan programs offer tailored solutions across 18 states. Learn more about their offerings at 1st Nationwide Mortgage.

    Take the next step by reviewing how income based on bank deposits could increase your qualifying income and open doors to more mortgage options with 1st Nationwide Mortgage. Get clear guidance on programs designed for your unique financial profile and advance your home financing with confidence.

    https://1stnwm.com

    FAQ

    What features make 1st Nationwide Mortgage ideal for self-employed borrowers?

    1st Nationwide Mortgage uses a bank statement loan approach, allowing self-employed borrowers to qualify using 12–24 months of bank deposits instead of tax returns. This method is designed specifically for borrowers whose tax returns may understate their actual cash flow. If you’re self-employed and struggling to provide traditional documentation, this approach can simplify your mortgage application process.

    How does 1st Nationwide Mortgage compare to Griffin Funding for income verification?

    Griffin Funding focuses on digital mortgage workflows and offers tailored underwriting for complex income profiles. In contrast, 1st Nationwide Mortgage specifically targets self-employed borrowers by allowing them to qualify based on bank statements, which can be more beneficial if you cannot meet standard income documentation requirements. Each choice presents unique advantages depending on your specific financial situation.

    Can 1st Nationwide Mortgage help if I have low net profit on my tax returns?

    Yes, 1st Nationwide Mortgage can accommodate borrowers with low net profit by applying a 50% expense factor on business accounts. This may drop to 35–40% with a CPA certified profit and loss statement. This flexibility allows you to demonstrate more qualifying income than what your tax returns alone may show.

    What are the costs associated with 1st Nationwide Mortgage products?

    Pricing for 1st Nationwide Mortgage varies widely by program, particularly for non QM and investor loans, which generally have higher rates compared to conventional mortgages. To get an exact quote that suits your needs, direct communication with the lender will be necessary.

    How accessible are 1st Nationwide Mortgage’s services across different states?

    1st Nationwide Mortgage offers lending services in 41+ states, making it accessible to a broad range of borrowers, including both self-employed individuals and real estate investors. This extensive coverage means you can find options tailored to your needs regardless of your location.

  • Top 6 nmbnow.com Alternatives for Mortgage Providers 2026

    Top 6 nmbnow.com Alternatives for Mortgage Providers 2026

    Finding a direct mortgage lender that reliably qualifies self-employed borrowers and investors without relying on tax returns or rigid W-2 income is still difficult. Many well-known lenders use only standard documentation, lock unconventional borrowers out, or hide program and pricing specifics until late in the process. This list highlights six direct alternatives to nmbnow.com, so mortgage brokers and non-QM lenders can match the right lender to each borrower’s complexity.

    Table of Contents

    1st Nationwide Mortgage
    https://1stnwm.com

    At a Glance

    The lender qualifies self-employed borrowers using 12–24 months of bank deposits instead of tax returns. That method lets people with large tax write-offs show qualifying cash flow. 1st Nationwide Mortgage operates as a direct mortgage banker and focuses on non-QM and investor programs.

    Core Features

    1st Nationwide Mortgage supports Bank Statement Loans, DSCR Loans, and NONI investment programs alongside FHA, VA, USDA, conventional, and jumbo options. The company details a standard expense factor of 50% on business accounts and notes the factor can drop to 35–40% with a CPA-certified profit and loss. The firm is founded and operated by Christopher Arco, NMLS #1281, and it reports licensing for investor products in 41+ states while holding retail licenses in 18 states and a BBB A+ rating.

    Key Differentiator

    The clearest distinction is the focus on alternative qualifying methods for self-employed borrowers and investors after more than 20 years in mortgage lending. That depth shows up in underwriting that accepts deposit-based income, rental cash flow calculations, and foreign national pathways for borrowers with no documentable income. The underwriting approach reduces reliance on W-2 or tax return income when alternative documentation better reflects a borrower’s ability to repay.

    Pros

    The team brings long experience handling complex files for self-employed borrowers and investors, which shortens the back-and-forth on documentation. Their bank statement product accepts 12–24 months of deposits and offers an expense-factor path tied to CPA documentation, which can materially increase qualifying income for some applicants. They support investors with DSCR underwriting that uses property rental income and works with LLC structures, reducing the need to show personal income for qualification.

    Cons

    • Higher interest rates than conventional loans because programs sit outside standard QM guidelines.

    Who It’s For

    You should consider this if you are self-employed and your tax returns understate your cash flow. Real estate investors who need DSCR underwriting or want to finance multiple properties will find the product suite relevant. Foreign nationals and borrowers without traditional paperwork also fit the target profile.

    Unique Value Proposition

    The underwriting rule that uses a 50% standard expense factor on business accounts, which can fall to 35–40% with a CPA-certified P&L, makes income calculation predictable for complex files. That rule changes the payment-to-income math and often raises effective qualifying income for borrowers with many write-offs. For brokers and loan officers, that predictability means fewer last-minute surprises during underwriting.

    Real World Use Case

    A self-employed consultant with high business deductions provides 24 months of bank statements and a CPA-certified P&L. Under the bank statement method, the expense factor drops to 35%, raising qualifying income enough to approve a mortgage. The borrower closes without needing to increase down payment or alter business accounting substantially.

    Pricing

    Pricing is not published online because this offering is informational only and rates vary by product, credit, and loan-to-value. Loan pricing depends on program choice, credit score, down payment, and property type. Contact a loan officer for a tailored loan estimate and program quote.

    Website: https://1stnwm.com

    Origin Mortgage
    https://origin-mortgage.com

    At a Glance

    In house underwriting and deep non QM expertise drive faster decisions on complex loan files. Origin Mortgage reports operating since 1998 and serving retail and wholesale partners across all 50 states. The lender emphasizes quick turn times and hands-on structuring for self employed borrowers and investors. That focus makes it a frequent choice when standard underwriting fails.

    Core Features

    Origin Mortgage underwrites a wide set of non QM programs, including bank statement and P&L options, asset depletion, 1099, and foreign national loans. The product lineup also includes DSCR loans for investor financing, plus traditional FHA, VA, and conventional pathways and reverse mortgages for seniors. Wholesale partner programs provide in house underwriting and rapid turn times for brokers.

    Key Differentiator

    The single distinguishing feature is the lender’s in house underwriting team paired with non QM depth. That pairing lets origin structure deals other lenders reject and move documentation through underwriting faster. The model favors brokers who need discretionary decisions and bespoke income calculations. It trades off scale for underwriting flexibility.

    Pros

    Origin Mortgage offers clear strengths for brokers and complex borrowers. Its non QM expertise supports cases where tax returns understate viable income, and that expertise often converts declined applicants into funded loans. Fast turnaround is a common advantage, backed by dedicated teams and senior staff access. Nationwide licensing gives brokers reach across all states when the borrower location matters.

    Cons

    • Third party reviews report overlay strictness that can produce last minute conditions.

    • The range of in house product options can feel complex for brokers new to non QM lending.

    • Speed and flexibility depend on documentation quality and case complexity, so results vary.

    When It May Not Fit

    Origin Mortgage may not fit borrowers who need plain conforming loans with standard documentation. It also may be a poor match in regions with strict local regulatory constraints or layered investor overlays. Brokers who prefer automated pricing and a single product workflow will likely find the variety cumbersome.

    Who It’s For

    Mortgage brokers and non QM lenders seeking a partner for fast, flexible alternative mortgage programs will gain the most. Real estate investors needing rental income based financing and self employed borrowers with complex cash flow also align well. Wholesale partners who require in house underwriting and case by case structuring benefit most.

    Real World Use Case

    A self employed borrower with substantial deposits but low taxable income uses the bank statement program to qualify. Origin’s underwriting accepts deposit based qualifying and issues a loan approval after targeted documentation. The result lets the borrower close when conventional lenders had declined.

    Pricing

    Pricing is not publicly listed. Origin Mortgage issues loan pricing through broker channels and wholesale rate sheets and quotes. Contact a broker or the company directly for case specific fees and rates.

    Website: https://origin-mortgage.com

    AD Mortgage
    https://admortgage.com

    At a Glance

    AD Mortgage reports a network of over 9,000 brokerage partners across 49 states and 20 years of industry experience. The firm positions itself as a wholesale lender concentrating on Non-QM and other programs. That scale supports broad distribution and rapid market reach for brokers.

    Core Features

    AD Mortgage offers a wide set of loan programs, including Non-QM, conventional, FHA, VA, and jumbo products, and portfolio options for real estate investors. The platform includes technology tools such as Quick Pricer, AD Studio, and AIM Portal, plus an automated guideline search to speed decisioning. The vendor advertises underwriting turnarounds as quick as 24 to 48 hours and provides account support, training, and industry guides.

    Key Differentiator

    Speed of execution and tailored support set AD Mortgage apart for brokers facing complex borrower profiles. The combination of rapid underwriting and loan options aimed at unconventional income sources reduces time to close. Dedicated training and a partner-focused portal aim to keep brokers informed and operationally efficient.

    Pros

    The team is described as highly responsive and professional, which helps smooth difficult deals and preserve borrower confidence. AD Mortgage reports over 1,300 positive reviews and a 4.8 star rating, which suggests consistent partner satisfaction. Robust tech tools shorten underwriting cycles and the lender supports a wide set of flexible loan structures for nontraditional income and investor needs.

    Cons

    • Specific limits exist on business purpose loans, which may exclude some niche commercial funding needs.
    • Borrowers with highly complex credit or extreme file quirks can require extra underwriting steps and manual approvals.
    • Several users report the interface is improving but still needs refinement to match automation elsewhere.

    When It May Not Fit

    If you require full retail-style consumer disclosures for every loan scenario, AD Mortgage’s wholesale model may not match your workflow. Brokers needing fully automated decisioning for every edge case will find manual approvals more frequent. Teams focused exclusively on small-scale consumer retail lending may prefer a different channel.

    Notable Integrations

    • ADwise guideline search
    • Partner Portal AIM
    • Loan Calculator Quick Pricer
    • AD Appraisal Center
    • Partner Support

    Who It’s For

    Mortgage brokers, lenders, and loan officers who handle unconventional income and investor deals will find AD Mortgage useful. Professionals who value fast turnarounds and a partner support model gain the most. Brokers closing complex or portfolio loans will see the platform fit their needs.

    Real World Use Case

    A broker used AD Mortgage to place a Non-QM loan for a self-employed borrower with irregular deposits and multiple income streams. Rapid underwriting and targeted product choice allowed closing in about 30 days. The broker relied on portal tools and account support to document qualifications.

    Pricing

    Pricing is not publicly specified and typically follows broker-specific models that vary by scenario. Expect pricing and overlays to depend on loan program, borrower profile, and wholesale relationship terms. Discuss pricing directly with an account representative for firm quotes.

    Website: https://admortgage.com

    Enrich Loans
    https://enrichloans.com

    At a Glance

    Approvals can close in as little as 30 days, according to Enrich Loans’ marketing materials. They target nonqualified mortgage borrowing for investors, entrepreneurs, and LLC owners. The company operates in nearly 30 states and plans to add HELOC and international solutions.

    Core Features

    Enrich Loans centers on non-QM and alternative documentation programs that let property cash flow serve as the qualifying income. The product set includes DSCR loans that accept rental income instead of personal payroll, plus programs that support LLC ownership and multiple property types. The underwriting emphasizes a faster approval process and flexible qualification criteria tied to the asset rather than borrower W2s or tax returns.

    Key Differentiator

    The firm qualifies loans primarily on property cash flow rather than the borrower’s personal income. That focus lets investors scale without producing conventional income documentation. This approach narrows the audience to investor-grade financing rather than primary residence lending.

    Pros

    No personal income verification is a clear strength for borrowers whose tax returns underreport cash flow. The lender advertises a quick turnaround, and that timeline helps investors close time-sensitive deals. Programs support LLC ownership and multiple property types, which simplifies portfolio growth. Underwriting that weights property cash flow over personal income reduces reliance on traditional debt to income calculations.

    Cons

    • Higher down payment requirements of 20–25% make early leverage more expensive for some buyers.
    • Interest rates may run higher than conventional products, increasing holding costs for marginal deals.
    • Product set is limited to investment and non-owner occupied properties, not primary residences.
    • Not suitable for borrowers who need conventional owner-occupied financing or second home loans.

    When It May Not Fit

    Borrowers seeking purchase or refinance on a primary residence should look elsewhere. Borrowers with thin or negative property cash flow will have difficulty getting approval. The offering is also restricted by state licensing, so geography matters for availability.

    Who It’s For

    Serious real estate investors, entrepreneurs, and LLC owners who rely on rental income to qualify make the best fit. You should have established properties or clear rental projections and the capital for larger down payments. This product suits people who prioritize speed and flexible documentation over the cheapest long term rate.

    Real World Use Case

    An investor uses rental income to qualify for financing on multiple single family homes, avoiding time spent compiling years of personal tax documentation. They lock deals quickly using the advertised approval speed so they can close before competing bids move prices. The property cash flow underwriting lets the investor finance assets held in LLCs without personal income layering.

    Pricing

    No public pricing table appears; pricing is not listed and is informational only. Expect loan-level pricing that varies by state, property cash flow, and borrower profile. Contact the lender for a personalized rate quote and program terms.

    Website: https://enrichloans.com

    Rocket Mortgage
    https://rocketmortgage.com

    At a Glance

    Rocket Mortgage reports closing over 9 million mortgages. The platform emphasizes a largely online application and fast rate visibility for U.S. residential borrowers. Its marketing highlights special offers with partners such as Redfin and lender credits aimed at lowering closing costs.

    Core Features

    The site offers an online mortgage application and pre-qualification flow that moves applicants from estimate to submission without in-person paperwork. It provides rate alerts and real-time rate updates alongside mortgage calculators for payment estimation. The product covers purchase loans, refinancing, VA loans, and options for debt consolidation using home equity.

    Key Differentiator

    Rocket Mortgage centers on a highly digital borrower experience that keeps rate data live and visible during the application process. That live rate focus, combined with partner offers, shortens the time you spend hunting for comparable lender credits and promotions. This emphasis on continuous rate visibility is the clearest difference versus more traditional lender workflows.

    Pros

    The online process reduces several common friction points in mortgage applications and keeps documents and messages in one interface. Multiple program types, including VA loans and first time buyer options, broaden who can qualify through the platform. Special offers and lender credit features can lower closing costs when paired correctly with a property transaction.

    Cons

    • Page content shows broken or missing detailed feature and pricing pages, limiting how deeply a borrower can research specific product terms.
    • The scraped data provides limited specifics on adjustable features, exact loan terms, or underwriting nuances for complex income profiles.
    • Third party reviews were not included in the dataset, so independent customer experience depth is not available here.

    When It May Not Fit

    If you lack reliable internet access or prefer in person meetings, the platform could be harder to use because the experience depends on digital access. Borrowers needing unusually customized loan structures or hyperlocal underwriting exceptions may find the public feature set thin. People outside supported geographic areas could face product or licensing limits based on location and borrower profile.

    Who It’s For

    This platform suits U.S. homebuyers and homeowners who want a largely online mortgage experience and clear rate visibility. It fits first time buyers, veterans seeking VA loans, and owners looking to refinance or consolidate debt through home equity. If you prefer phone and branch interaction over web driven steps, this may not match your preferred workflow.

    Real World Use Case

    A veteran compares VA loan options, watches live rate alerts, and completes the online application with a digital upload of service documents. A homeowner with equity runs payment estimates, sees lender credit offers with a partner, and submits a refinance application to lower monthly outlay. In both examples, the continuous rate updates speed decision making.

    Pricing

    The site lists pricing as not applicable for informational content and does not publish uniform lender fees on public pages. Loan pricing depends on individual loan terms, credit profile, and market rates at application. Expect final costs to come from a formal loan estimate after application and underwriting.

    Website: https://rocketmortgage.com

    loanDepot
    https://loandepot.com

    At a Glance

    loanDepot reports a consistent 90%+ customer survey rating. That figure signals strong reported satisfaction with loan officers and the digital experience. The company combines a digital mortgage workflow with a broad set of loan products for purchase and refinance.

    Core Features

    The platform centers on the digital platform “mello”, which handles online application, document upload, and real time status updates. Loan choices include fixed rate, adjustable rate, FHA, VA, jumbo, and rehab loans, plus programs for builders and real estate partners. Proprietary tooling aims to speed processing while keeping borrowers informed during underwriting and closing.

    Key Differentiator

    The single most distinguishing feature is “mello”. It provides a fully digital application and loan management experience across devices, with status transparency and document handling built in. That focus on an end to end digital workflow sets loanDepot apart from lenders that still rely on paper and manual status calls.

    Pros

    Reported customer satisfaction is high, and that rating suggests many borrowers have good experiences with service and communication. The digital workflow reduces back and forth. The product set covers common borrower needs, from FHA programs for low down payment buyers to jumbo loans for higher value purchases. Builder and realtor programs make loanDepot a practical choice when new construction finance must align with sales and closing schedules.

    Cons

    • Some detailed product and application information sits behind a paywall on the website, which makes initial comparison harder.
    • A few reviews describe the process as complex for borrowers without mortgage experience, so guidance may be needed.
    • Physical branch presence is limited, so borrowers who prefer face to face meetings may find the support model less convenient.

    When It May Not Fit

    If you prefer in person meetings for financial decisions, loanDepot may feel remote because it relies on digital processes and phone based support. Borrowers with unusually complex financing needs might need more hands on, localized underwriting. Small builders or agents who require local branch relationships could find the partnership model less helpful.

    Who It’s For

    You should consider loanDepot if you want a modern, digital mortgage workflow and a broad menu of loan products. It fits first time and experienced homebuyers who are comfortable managing much of the process online. It also fits builders and agents who need partnership programs and joint venture options.

    Real World Use Case

    A first time buyer compares rates, completes an application, and uploads bank statements through the platform. The borrower receives timely status updates and document requests via the portal. The digital handoff to underwriting and closing keeps the timeline predictable and reduces surprise requests.

    Pricing

    Not applicable. The site presents product and eligibility information rather than a per user or license pricing model, because loanDepot is a mortgage lender rather than software sold by subscription.

    Website: https://loandepot.com

    Comparison of alternatives

    Among mortgage lenders, 1stnwm.com excels in tailoring solutions for self-employed borrowers through its specialized application processes and adjustable expense norms based on CPA documentation. Here, we compare the offerings of other notable lenders to highlight strengths and contexts where they shine.

    Application process and underwriting speed

    Origin Mortgage distinguishes itself by offering in-house underwriting and fast decision-making on complex files, giving brokers a consistent edge in rapid case handling. While other competitors provide platforms, Origin Mortgage’s hands-on approach allows for discretionary decisions that multiply approval possibilities for intricate borrower profiles.

    Supporting tools and geographic flexibility

    AD Mortgage leverages an extensive broker support network, technological tools like automated pricing systems, and accessible services across 49 states. This infrastructure aids brokers focusing on unconventional loans, though its geographic integration still falls short of full nationwide licensing. loanDepot emphasizes a highly digital workflow via its “mello” platform, facilitating a streamlined application journey for tech-savvy clients accustomed to web-based systems.

    Best fit

    • Self-employed borrowers prioritizing adjustable income qualification models will benefit most from 1stnwm.com’s specialized programs.
    • Brokers requiring rapid underwriting decisions and customizable loan structuring should engage Origin Mortgage’s services.
    • Real estate investors seeking financing based on property cash flow find Enrich Loans well-suited to their needs.
    • Borrowers focused on an online-first workflow blended with transparent document handling gravitate towards loanDepot.
    • Teams valuing responsive support paired with versatile programs can securely use AD Mortgage.

    Our pick

    1stnwm.com provides a unique capability by catering directly to self-employed borrowers needing income qualification through detailed bank statements and CPA-driven expense analysis. However, prospective clients prioritizing geographically exhaustive services or seeking purely automated underwriting processing might find other options more aligned with their preferences.

    1st Nationwide Mortgage provides unique underwriting strategies tailored to individuals with unconventional income documentation, making it stand out among its alternatives.

    Product Core Features Target Audience Pricing Notable Limitation
    1st Nationwide Mortgage Bank Statement Loans, DSCR Loans, NONI Investment Programs Self-employed borrowers and real estate investors Price not published Higher interest rates than conventional loans
    Origin Mortgage In-house underwriting, flexible documentation options Mortgage brokers and self-employed borrowers Price not published Potential overlay strictness causing additional conditions
    AD Mortgage Non-QM loans, advanced broker tools, rapid turnaround Brokers focused on unconventional income and investor loans Price not published Interface improvements are ongoing
    Enrich Loans Non-QM programs qualifying on property cash flow Real estate investors and entrepreneurs Price not published Higher down payment requirements
    Rocket Mortgage Digital application process, VA and refinance loans Homebuyers preferring online workflows Price not published Limited details on adjustable loan features

    Challenges With Conventional Mortgage Qualification for Self-Employed Borrowers and Investors

    Qualifying for a mortgage often depends heavily on tax returns and traditional income documents. For self-employed borrowers and real estate investors, this approach can obscure true cash flow due to deductible expenses and complex ownership structures. This mismatch leads to underreported income, stricter debt-to-income calculations, and limited loan options.

    1st Nationwide Mortgage offers solutions addressing these challenges. Their bank statement loans use 12 to 24 months of bank deposits to measure real income instead of tax returns. With a CPA-certified profit and loss statement, the standard 50% expense factor on business accounts can adjust down to 35 to 40%, allowing more accurate income qualification. Investor borrowers benefit from DSCR Loans, where rental income—not personal income—determines eligibility, including for LLC-held properties.

    Learn more about 1st Nationwide Mortgage’s loan programs.

    Take the next step toward clearer income qualification by reviewing how bank statement documentation and DSCR underwriting can affect your loan estimate with 1st Nationwide Mortgage.

    FAQ

    How does 1st Nationwide Mortgage support self-employed borrowers?

    1st Nationwide Mortgage primarily qualifies self-employed borrowers using 12–24 months of bank deposits instead of tax returns. This approach allows applicants with high tax write-offs to demonstrate qualifying cash flow effectively. If you are self-employed and your tax returns do not reflect your income, 1st Nationwide Mortgage could provide a viable alternative for securing a mortgage.

    What is the difference between 1st Nationwide Mortgage and Origin Mortgage?

    Origin Mortgage is recognized for its in-house underwriting and deep non-QM expertise, which drives faster decisions on complex loan files. 1st Nationwide Mortgage shines when borrowers need alternative qualifying methods, such as bank statement loans, where tax returns may not accurately show income. Consider what fits your specific needs as a borrower to choose between the two.

    Can I use bank statement loans with 1st Nationwide Mortgage?

    Yes, 1st Nationwide Mortgage offers bank statement loans that accept 12–24 months of deposits for qualifying income. This feature significantly benefits self-employed individuals whose tax returns understate their actual cash flow. If traditional documentation isn’t an option for you, exploring 1st Nationwide Mortgage’s bank statement loans could be a great starting point.

    How quickly can I expect the underwriting process with 1st Nationwide Mortgage?

    While specific timeframes weren’t detailed in the article, 1st Nationwide Mortgage’s focus on alternative income documentation typically allows for a streamlined qualification process. If you’re looking for faster approvals, 1st Nationwide Mortgage may serve as an effective choice compared to traditional lenders.

    What are the interest rates like with 1st Nationwide Mortgage?

    The article notes that 1st Nationwide Mortgage offers higher interest rates than conventional loans due to their non-QM program structure. Keep in mind that while their rates may be higher, their flexible qualifying criteria can meet unique borrower needs effectively. It’s worth evaluating your budget against these rates to determine if it meets your financing goals.

  • Two-Year Self-Employment Mortgage Requirement Explained

    Two-Year Self-Employment Mortgage Requirement Explained

    The two-year self-employment mortgage requirement is the standard lenders use to verify that your income is stable enough to support a home loan. Most conventional and government-backed programs, including those governed by Fannie Mae and Freddie Mac guidelines, require at least two full years of self-employment history before they will count your income toward qualification. If you own 25% or more of a business, work as a sole proprietor, or earn income as an independent contractor, this rule applies to you. Understanding exactly what lenders want, and how to prepare for it, is the fastest path to approval.

    What documents prove the two-year self-employment mortgage requirement?

    Lenders do not offer a separate “self-employed mortgage.” They use standard mortgage programs with specialized income verification layered on top. The goal is proving that your income is real, consistent, and likely to continue.

    For a conventional or government-backed loan, you will typically need:

    • Two years of personal tax returns (IRS Form 1040) with all schedules attached
    • Two years of business tax returns (Form 1120S for S-corps, Form 1065 for partnerships, or Schedule C for sole proprietors)
    • A year-to-date profit and loss (P&L) statement, prepared or reviewed by a CPA
    • 12–24 months of business bank statements to confirm deposit activity
    • Evidence of business ownership, such as a business license, articles of incorporation, or a CPA letter

    Lenders require this documentation to verify both the existence of your business and the sustainability of your income. A single profitable year is not enough. Underwriters want to see a pattern.

    Bank statement loans work differently. Instead of tax returns, bank statement loans use 12–24 months of deposit history to calculate qualifying income. This approach is built for self-employed borrowers whose tax write-offs reduce their reported net income below what conventional underwriting accepts. The lender applies an expense factor, typically 50% on business accounts, to arrive at a usable income figure. A CPA-certified P&L can lower that expense factor to 35–40%, which increases your qualifying income.

    Hands pointing at self-employment income documents

    Pro Tip: Keep your personal and business bank accounts completely separate. Commingled accounts create confusion during underwriting and can delay or derail your approval.

    Lenders also look at whether your income documentation is professionally prepared. Accounts finalized by a qualified accountant carry more weight than self-prepared spreadsheets. That credibility matters when an underwriter is deciding whether to approve your file.

    Are there exceptions to the two-year requirement for new self-employed borrowers?

    The two-year benchmark is a guideline, not an absolute wall. Fannie Mae guidelines allow lenders to qualify a borrower with just one year of self-employment income under specific conditions. Income stability takes priority over the exact date your business started.

    To qualify with one year of self-employment, you generally need to meet all of the following:

    • Prior W-2 employment in the same field as your current self-employment
    • A documented transition from employee to self-employed, showing the work is the same type
    • Strong supporting financials, including a healthy credit score and reserves
    • A lender willing to accept the exception, since not all lenders apply this flexibility

    The key word is “same field.” A graphic designer who spent five years at an agency and then went freelance has a credible case. Someone who left a corporate finance role to open a restaurant does not. Underwriters look for continuity of skill and income source, not just continuity of employment.

    Income from self-employment under one year cannot be used for qualification on government-backed loans without that accompanying employment history. If you are under the one-year mark entirely, alternative loan products are your only path. Options like mortgage without tax returns programs or asset-based lending may apply depending on your financial profile.

    How do lenders calculate qualifying income from self-employment?

    Lenders calculate your qualifying income by averaging your net profit across the two-year period, then dividing by 24 to get a monthly figure. Fannie Mae’s income calculation method also allows adjustments for nonrecurring expenses and losses that appear on your returns but do not reflect your ongoing earning capacity.

    Infographic showing steps to calculate qualifying self-employment income

    The table below shows how income averaging works in practice:

    Scenario Year 1 Net Profit Year 2 Net Profit Monthly Qualifying Income
    Stable growth $80,000 $100,000 $7,500
    Declining income $100,000 $80,000 $7,500
    Sharp decline $120,000 $60,000 $7,500
    Single year only N/A $90,000 $7,500

    The math looks identical in the first three rows, but the underwriting outcome is not. A declining income trend raises a red flag even when the average looks acceptable. Underwriters are trained to ask whether the lower year represents a new normal. If year two is significantly lower than year one, many lenders will cap qualifying income at the lower year’s figure rather than use the average.

    Lenders average income over two years to assess sustainability, not just current earning power. That distinction matters when you are planning your application timeline. If your income dipped in one year due to a one-time expense or a slow quarter, having your CPA document that clearly in a letter can prevent the underwriter from treating it as a trend.

    Variable income borrowers should also review variable income qualification tips before applying. Seasonal businesses, project-based work, and commission-heavy income all require extra documentation to show the pattern is predictable.

    What are common mistakes to avoid when applying under the two-year rule?

    Most self-employed mortgage denials come down to preparation, not eligibility. The income is there. The documentation is not. Avoiding these mistakes puts you in a much stronger position before you ever submit an application.

    • Submitting incomplete tax returns. Missing schedules, unsigned returns, or returns that do not match your IRS transcripts will stop your file cold. Lenders order IRS transcripts directly and compare them to what you submit.
    • Mixing personal and business finances. Lenders classify self-employed borrowers as those owning 20–25% or more in a business and expect clean financial separation. Commingled accounts make income harder to verify and raise questions about business viability.
    • Applying right after a big income spike. Sudden income increases just before applying raise lender concerns about sustainability. A year with unusually high revenue looks great on paper but can actually hurt you if the underwriter cannot confirm it will continue.
    • Waiting too long to consult a mortgage professional. Many self-employed borrowers apply and get denied, then learn they could have qualified if they had structured their finances differently 12 months earlier.

    Pro Tip: Talk to a mortgage professional at least one year before you plan to buy. They can review your tax returns, flag documentation gaps, and tell you exactly what your qualifying income looks like before you fall in love with a property.

    Self-employed borrowers who work with a 1099 contractor mortgage specialist also tend to move through underwriting faster. A lender who regularly works with self-employed files knows what documentation to request upfront and how to present your income clearly to an underwriter.

    Key Takeaways

    Meeting the two-year self-employment mortgage requirement depends on consistent income documentation, clean financial records, and choosing the right loan program for your situation.

    Point Details
    Two-year standard Most conventional and government-backed loans require two full years of self-employment income history.
    Documentation matters Tax returns, P&L statements, and 12–24 months of bank statements are the core verification tools.
    One-year exception exists One year of self-employment may qualify if prior W-2 work in the same field is documented.
    Income averaging is key Lenders average net profit over two years; a declining trend can cap your qualifying income at the lower figure.
    Bank statement loans offer an alternative Self-employed borrowers with high write-offs can use deposit history instead of tax returns to qualify.

    What I have learned helping self-employed borrowers qualify

    After working with hundreds of self-employed borrowers, the pattern is clear. The ones who struggle are not struggling because their income is too low. They struggle because their documentation does not tell a clean story.

    Tax write-offs are a legitimate and smart financial tool. But they create a gap between what you actually earn and what a conventional underwriter sees on paper. That gap is the core challenge of self-employed mortgage qualification, and it is entirely solvable with the right preparation.

    The biggest misunderstanding I see is that borrowers assume their accountant has already optimized their returns for mortgage qualification. Accountants optimize for tax savings. Mortgage qualification requires a different lens. Those two goals often pull in opposite directions. A CPA who understands mortgage underwriting is worth every dollar.

    Lender variability is also real. Not every lender applies the one-year exception. Not every lender offers bank statement programs. Working with a direct lender who actively underwrites self-employed files, rather than routing your application through a broker who sends it wherever it fits, gives you a clearer picture of what is actually possible for your specific situation.

    Preparation and transparency are not just good habits. They are the difference between a smooth approval and a 60-day delay.

    — Chris Arco, NMLS #1281

    Self-employed borrowers and 1st Nationwide Mortgage

    Self-employed borrowers who have been turned away by conventional lenders often find that the right loan program was available all along. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, which means your file is underwritten in-house by a team that works with self-employed income every day.

    https://1stnwm.com

    For borrowers who cannot qualify using tax returns, bank statement mortgage programs use 12–24 months of deposits to calculate income directly. For those who meet the two-year standard, conventional loan options are available in 18 licensed states. Use the mortgage calculators to estimate your qualifying income before you apply, or speak directly with Chris Arco, NMLS #1281, to review your documentation and identify the right path forward.

    FAQ

    What is the two-year self-employment mortgage requirement?

    The two-year self-employment mortgage requirement is the standard used by most conventional and government-backed lenders, including those following Fannie Mae guidelines, to verify that a self-employed borrower’s income is stable and sustainable before approving a loan.

    Can I qualify with less than two years of self-employment?

    Yes, in limited cases. Fannie Mae allows one year of self-employment income to qualify if the borrower has prior W-2 employment in the same industry. Less than one year of self-employment cannot be used for qualification on standard loan programs.

    What documents do I need for a self-employed home loan?

    You typically need two years of personal and business tax returns, a year-to-date P&L statement, 12–24 months of bank statements, and evidence of business ownership such as a business license or CPA letter.

    How does a bank statement loan differ from a conventional mortgage?

    A bank statement loan uses 12–24 months of deposit history instead of tax returns to calculate qualifying income. This option works well for self-employed borrowers whose write-offs reduce their reported net income below conventional underwriting thresholds.

    Does a declining income trend hurt my mortgage application?

    Yes. Lenders average net profit over two years, but a significant decline from year one to year two often leads underwriters to cap qualifying income at the lower figure rather than use the average.

  • Why Freelancers Are Considered High-Risk Borrowers

    Why Freelancers Are Considered High-Risk Borrowers

    Freelancers are classified as high-risk borrowers because their income is irregular, variable, and difficult for traditional lenders to verify reliably. In the mortgage and lending world, the standard term for this classification is “non-traditional income borrower,” though lenders still apply high-risk underwriting criteria to this group. 38% of the U.S. workforce freelanced in 2023, yet 30% of self-employed borrowers report that legacy credit model requirements like 2–3 years of audited returns create major financing barriers. That gap between workforce size and credit access defines the core problem. Understanding why freelancers are considered high-risk borrowers is the first step toward doing something about it.

    Why are freelancers considered high-risk borrowers by lenders?

    The root cause is how lenders measure income reliability. Traditional underwriting was built around W-2 employees, where income is verified in real time through employer records and pay stubs. Lending algorithms favor W-2 income because it is predictable and instantly verifiable. Freelancers, by contrast, submit 1099 forms and Schedule C tax returns, which show net income after deductions rather than gross earnings. That distinction alone can cut a freelancer’s qualifying income in half.

    Mortgage officer reviewing freelancer income documents

    Lenders use a two-year average of Schedule C net income to calculate debt-to-income (DTI) ratios. If your net income was $80,000 in year one and $60,000 in year two, your qualifying income is $70,000, not $80,000. This backward-looking average penalizes freelancers who are growing their business. It also ignores the fact that 68% of gig workers carry prime or better credit, which is a strong indicator of financial responsibility.

    The documentation burden compounds the problem. Lenders typically require two years of personal and business tax returns, a year-to-date profit and loss statement, and sometimes a CPA letter confirming self-employment. A salaried employee provides two pay stubs and a W-2. That asymmetry is not just inconvenient. It signals to the lender that your income is harder to trust, even when your actual cash flow is strong.

    • W-2 income: Verified in real time, stable, and predictable
    • 1099 income: Verified through tax returns, averaged over two years, and reduced by deductions
    • Schedule C net income: The figure lenders actually use for DTI calculations
    • Bank statement analysis: An emerging alternative that uses 12–24 months of deposits to derive qualifying income

    Pro Tip: Start organizing your income documentation 12 months before you plan to apply for a loan. Lenders want to see consistency, not just totals. Monthly deposits that are steady carry more weight than a few large irregular payments.

    Common challenges freelancers face in loan applications

    Freelancer borrowing risks go beyond paperwork. The structural mismatch between how freelancers earn and how lenders evaluate income creates several specific hurdles.

    1. Income volatility signals risk. Lenders interpret month-to-month swings in deposits as instability, even when annual totals are strong. A freelancer earning $120,000 per year with uneven monthly deposits looks riskier than a salaried employee earning $90,000 per year with identical monthly paychecks.

    2. Gross revenue does not equal borrowing power. Lenders focus on net taxable income, not gross receipts. A freelancer billing $200,000 per year but deducting $80,000 in business expenses qualifies on $120,000, not $200,000. Many freelancers are surprised by this when they first apply.

    3. Tax deductions reduce loan eligibility. Aggressive tax planning is smart for minimizing your IRS bill. It is counterproductive when you need a mortgage. Every dollar you deduct lowers your net income, which directly lowers your qualifying loan amount. This is one of the most overlooked conflicts in freelance financial planning.

    4. Client concentration raises red flags. If 70% of your revenue comes from one client, lenders see a single point of failure. Losing that client would eliminate most of your income. Lenders model this as elevated default risk, even if your credit score is excellent.

    5. Fixed loan payments clash with variable income. Loan payments are fixed, but client payments vary with 30–60 day billing cycles. That timing gap creates cash flow stress and can push freelancers into high-interest revolving debt to cover a single missed payment.

    Pro Tip: Talk to a CPA before tax season if you plan to apply for a loan within the next two years. Balancing deductions against qualifying income is a real tradeoff. Taking every possible deduction this year could cost you more in loan terms than you saved on taxes.

    How interest rates and loan terms reflect the freelancer risk profile

    Infographic comparing salaried and freelancer borrowers

    The financial cost of being classified as a high-risk borrower is concrete. Gig workers pay 3–7% more in effective interest rates than salaried employees. That premium exists because lenders price income unpredictability into the rate. It is not a penalty for bad credit. It is a charge for uncertainty.

    That rate difference has a real dollar impact. On a $400,000 mortgage, a 3% rate premium adds roughly $700 per month in payments and over $250,000 in total interest over a 30-year term. Conservative underwriting also compresses the loan amount itself. Lenders apply stricter DTI limits and may require larger down payments, typically 10–20%, compared to the 3–5% available to W-2 borrowers through conventional programs.

    Factor Salaried W-2 borrower Freelancer or 1099 borrower
    Income verification Pay stubs and W-2 Two years of tax returns, Schedule C
    Qualifying income basis Gross salary Net income after deductions
    DTI calculation Straightforward Two-year average, often compressed
    Typical down payment 3–5% (conventional) 10–20% (non-QM programs)
    Rate premium Standard market rate 3–7% higher for non-QM products
    Documentation burden Low High

    Loan-to-value requirements also tighten for freelancers. A lower LTV means more cash out of pocket at closing. For a freelancer who has been reinvesting in their business rather than accumulating liquid savings, that requirement alone can delay homeownership by years.

    Strategies to improve your loan approval odds as a freelancer

    Freelancers and self-employed borrowers have real options. The key is preparing before you apply, not after a lender declines you.

    • Build a consistent income floor. A steady monthly deposit pattern over 12–24 months is one of the strongest signals you can send to a lender. Aim for predictable monthly deposits rather than irregular large payments. If you invoice clients monthly instead of quarterly, your bank statements will reflect that consistency.

    • Maintain a cash reserve separate from business capital. A dedicated reserve account that covers 3–6 months of loan payments protects you from the timing gap between client payments and loan due dates. It also demonstrates financial discipline to underwriters reviewing your application.

    • Use bank statements actively. Open banking and real-time bank statement analysis are now accepted by a growing number of lenders. Programs like bank statement loans use 12–24 months of deposits to calculate qualifying income, bypassing the Schedule C problem entirely. At 1st Nationwide Mortgage, the bank statement loan program applies a standard 50% expense factor to business account deposits, which can drop to 35–40% with a CPA-certified profit and loss statement.

    • Consult a tax professional before applying. The balance between tax efficiency and qualifying income is a nuanced decision. A CPA who understands mortgage qualification can help you structure deductions to preserve enough net income for the loan amount you need.

    • Explore 1099 mortgage programs designed for your income type. These programs evaluate your gross 1099 income rather than Schedule C net income, which can significantly increase your qualifying amount. They exist specifically because the conventional model fails non-traditional income borrowers.

    Pro Tip: Keep personal and business bank accounts separate. Lenders reviewing mixed accounts have a harder time calculating your true income, and that ambiguity works against you. Clean account separation also makes the documentation process faster.

    Key Takeaways

    Freelancers face higher borrowing costs and stricter loan terms because conventional underwriting penalizes income variability and tax deductions, but bank statement loans and consistent income documentation can materially improve approval odds.

    Point Details
    Net income drives qualification Lenders use Schedule C net income, not gross revenue, so deductions directly reduce your borrowing power.
    Rate premium is real Gig workers pay 3–7% more in effective interest rates due to income unpredictability in lender risk models.
    Consistency beats volume Steady monthly deposits over 12–24 months improve lender confidence more than large irregular payments.
    Bank statement loans bypass the problem These programs use deposit history instead of tax returns, helping freelancers qualify on actual cash flow.
    Tax strategy affects loan eligibility Aggressive deductions lower net income and loan qualification amounts, requiring careful planning before applying.

    The reliability gap is real, but it is not permanent

    I have worked with hundreds of self-employed borrowers over the years, and the single most common frustration I hear is this: “My business is doing well. Why won’t a lender believe me?” The honest answer is that conventional underwriting was designed in a different era. It assumes that a W-2 paycheck is the only reliable measure of income. That assumption is increasingly wrong.

    What I have seen work, time and again, is preparation that starts well before the loan application. Freelancers who treat their bank statements like a financial resume, who keep their accounts clean, and who work with a CPA to balance deductions against qualifying income, get approved. The ones who walk in with two years of heavily deducted tax returns and no reserves often do not, even when their actual cash flow is strong.

    The lending industry is moving toward cash-flow-based evaluation. Real-time bank data and open banking integrations are changing what lenders can see and verify. That shift benefits freelancers directly. But the transition is slow, and most conventional lenders have not caught up. The practical advice I give every self-employed borrower is this: do not wait for the system to change. Use the programs that already exist for your income type, document your income consistently, and apply with a lender who understands how self-employment actually works.

    — Chris Arco, NMLS #1281

    Loan programs built for self-employed borrowers at 1st Nationwide Mortgage

    Freelancers and self-employed borrowers do not have to fit into a conventional lending box. 1st Nationwide Mortgage offers bank statement mortgage programs that use 12–24 months of deposit history to calculate qualifying income, bypassing the Schedule C problem that trips up so many self-employed applicants.

    https://1stnwm.com

    The full range of loan programs for self-employed borrowers at 1st Nationwide Mortgage includes options for variable income, 1099 contractors, and real estate investors. Minimum credit score requirements start at 620, and down payments range from 10–20% depending on the program. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, licensed in 18 states with a BBB A+ rating. You work directly with an underwriter who understands non-traditional income from the first conversation.

    FAQ

    Why are freelancers classified as high-risk borrowers?

    Lenders classify freelancers as high-risk because their income is variable, harder to verify, and reported on Schedule C tax returns after deductions, which reduces the net income figure used for debt-to-income calculations.

    Does good credit help freelancers get better loan terms?

    Good credit helps, but it does not offset income verification challenges. 68% of gig workers carry prime or better credit, yet they still face higher rates and stricter documentation requirements because lenders price income unpredictability separately from credit risk.

    What is a bank statement loan and how does it help freelancers?

    A bank statement loan uses 12–24 months of deposit history to calculate qualifying income instead of tax returns, allowing freelancers to qualify based on actual cash flow rather than net taxable income after deductions.

    How much more do freelancers pay in interest compared to salaried borrowers?

    Gig workers pay 3–7% more in effective interest rates than salaried employees, a premium that reflects lender risk models built around income unpredictability rather than creditworthiness alone.

    Can freelancers qualify for a mortgage with variable income in 2026?

    Yes. Programs like bank statement loans and 1099 mortgage options are specifically designed for variable income borrowers. Consistent deposit history over 12–24 months and a minimum 620 credit score are the primary qualifying factors for these programs.

  • High Write-Off Mortgage Qualification Guide for Investors

    High Write-Off Mortgage Qualification Guide for Investors

    High write-off mortgage qualification is the process of meeting IRS deduction rules and lender income standards to maximize deductible mortgage interest while still securing loan approval. Self-employed borrowers and real estate investors face a specific challenge: the same tax write-offs that reduce their IRS bill also shrink the income figure lenders use to approve loans. This guide covers the IRS debt limits that govern deductions, the alternative documentation methods that solve the income gap, and the loan programs built for borrowers with complex tax situations. Understanding all three gives you a real path forward.

    What are the IRS rules on mortgage interest deductions?

    The IRS mortgage interest deduction is the foundation of any high write-off mortgage qualification guide. Knowing the exact limits prevents costly mistakes at tax time and during underwriting.

    Debt limits that control your deduction

    For mortgage debt originated after december 15, 2017, the IRS caps deductible interest at the first $750,000 of combined mortgage debt. Debt originated before that date carries a higher limit of $1,000,000. If your total mortgage balance exceeds the applicable limit, only the proportional share of interest qualifies for the deduction.

    These limits apply across your primary residence and one secondary home combined. A $900,000 mortgage originated in 2023 means you can only deduct interest on $750,000 of that balance. The remaining $150,000 generates interest that produces no tax benefit.

    What counts as a qualified home

    The deduction applies only to loans secured by a qualified home used as your primary or secondary residence. Qualified homes include houses, condominiums, cooperatives, mobile homes with sleeping and bathroom facilities, and houseboats. A loan secured by a property you use purely for investment does not qualify for the personal mortgage interest deduction.

    Loan proceeds must also be used to buy, build, or substantially improve the home. The IRS disqualifies interest on home equity loans used for unrelated purposes such as paying off credit cards or funding a business. This distinction matters for real estate investors who pull equity from one property to fund another.

    Itemizing versus taking the standard deduction

    Over 90% of U.S. tax filers claim the standard deduction since 2018, when the Tax Cuts and Jobs Act nearly doubled standard deduction amounts. That shift means most homeowners no longer benefit from the mortgage interest deduction at all. Self-employed borrowers and investors with large loan balances, significant business deductions, and multiple properties are the group most likely to clear the itemization threshold.

    Infographic showing mortgage qualification steps

    Filing Status 2025 Standard Deduction Mortgage Interest Needed to Benefit from Itemizing
    Single $15,000 More than $15,000 in total itemized deductions
    Married Filing Jointly $30,000 More than $30,000 in total itemized deductions
    Head of Household $22,500 More than $22,500 in total itemized deductions

    Rental and business use of a property changes the tax form you use. Itemizing personal deductions requires Schedule A on Form 1040. Rental income and expenses go on Schedule E. Business use of a home goes on Schedule C. Getting the form right determines whether the deduction survives an audit.

    How can self-employed borrowers document income for mortgage qualification?

    Self-employed borrowers and real estate investors face a documentation problem that conventional underwriting was not designed to solve. Tax returns show taxable income after write-offs, which is often far below actual cash flow. The solution is alternative income documentation.

    Bank statements as proof of income

    Bank statement loans use 12–24 months of business or personal bank deposits to calculate qualifying income instead of tax returns. The lender applies an expense factor to the gross deposits to estimate net income. At 1st Nationwide Mortgage, the standard expense factor on business accounts is 50%. That means $20,000 per month in deposits produces $10,000 in qualifying income. With a CPA-certified profit and loss statement, that expense factor can drop to 35–40%, which meaningfully increases the qualifying income figure.

    Hands holding bank statement over table

    This approach works because it reflects actual cash flow rather than the taxable income number your accountant minimized. A freelance consultant depositing $180,000 per year might show $40,000 in taxable income after write-offs. A bank statement loan sees the $180,000 and works from there.

    Pro Tip: Ask your CPA to prepare a certified profit and loss statement before you apply. That single document can reduce your expense factor by 10–15 percentage points and increase your qualifying income significantly.

    1099 forms and profit and loss statements

    1099 mortgage loans use contractor income forms instead of W-2s or tax returns. Lenders average two years of 1099 income and apply their own expense ratio to arrive at qualifying income. This works well for independent contractors, consultants, and gig workers who receive consistent 1099 income but write off substantial business expenses.

    Key documentation lenders typically require for alternative income qualification:

    • 12–24 months of business or personal bank statements
    • A CPA-certified profit and loss statement (current year and prior year)
    • 1099 forms for the past two years if applicable
    • Business license or proof of self-employment for at least two years
    • A minimum 620 credit score for most alternative loan programs
    • 10–20% down payment depending on the loan program and property type

    Business write-offs do not automatically disqualify a self-employed borrower. Careful documentation is what separates a declined application from an approved one. The goal is to show a lender your real cash flow, not the number your tax return was designed to minimize.

    What mortgage types best support high write-off qualifications?

    Not every loan program handles complex income the same way. The right loan type depends on your income source, property type, and how you hold title.

    Bank statement loans

    Bank statement loans are the primary tool for self-employed borrowers who maximize write-offs. They replace tax return income with deposit-based income. At 1st Nationwide Mortgage, these loans require a minimum 620 credit score and 10–20% down. They are available for primary residences, second homes, and investment properties. A bank statement mortgage is the most direct solution for a borrower whose Schedule C shows minimal taxable income.

    DSCR loans for real estate investors

    Debt Service Coverage Ratio loans qualify the property, not the borrower. The lender compares the property’s rental income to its monthly mortgage payment. If the rent covers the debt service, the loan qualifies. The borrower’s personal income, tax returns, and write-offs are not part of the equation. DSCR loans at 1st Nationwide Mortgage work for LLCs and carry no limit on the number of financed properties. This makes them the best write-off mortgage strategy for investors building a portfolio.

    Mortgage without tax returns

    A mortgage without tax returns covers several program types beyond bank statement and DSCR loans. These include asset depletion loans, which calculate income from liquid assets, and NONI programs for borrowers with no documentable income. Foreign nationals and borrowers with offshore income structures often use these programs.

    Loan Type Qualifying Income Source Best For
    Bank Statement Loan 12–24 months of deposits Self-employed with high write-offs
    DSCR Loan Property rental income Real estate investors, LLCs
    1099 Loan Contractor income forms Freelancers, consultants
    Mortgage Without Tax Returns Assets or alternative docs Complex income, foreign nationals
    Conventional Loan Tax return income (2-year average) W-2 earners with stable income

    Rental property mortgage interest is deductible as a rental expense on Schedule E, separate from the personal mortgage interest deduction. A second home rented out must meet personal use tests to qualify for the personal deduction. If you rent it out more than 14 days per year and do not use it personally for the required number of days, it becomes a rental property for tax purposes.

    Step-by-step process to qualify for a high write-off mortgage

    A successful application requires preparation before you contact any lender. Rushing the process without the right documents is the most common reason self-employed borrowers get declined.

    1. Assess your income documentation. Determine whether your tax returns show enough income to qualify conventionally. If your adjusted gross income after write-offs is too low, identify whether bank statements, 1099 forms, or a CPA-certified P&L will better represent your cash flow.

    2. Pull and review your credit report. Most alternative loan programs require a minimum 620 credit score. Review your report at least 60 days before applying so you have time to correct errors or pay down balances that affect your score.

    3. Gather 12–24 months of bank statements. Separate business and personal accounts. Lenders will flag large irregular deposits, so prepare explanations for any non-recurring income. Consistent monthly deposits strengthen your file.

    4. Get a CPA-certified profit and loss statement. This document is not optional if you want the lower expense factor. It must be prepared and signed by a licensed CPA, not self-generated. A lower expense factor means higher qualifying income.

    5. Shop multiple lenders and compare APRs. Comparing APRs from multiple lenders is the most effective way to secure a mortgage that balances rate, tax strategy, and monthly payment. No single lender consistently offers the lowest rate for alternative income borrowers.

    6. Decide whether to itemize on your tax return. If your mortgage interest, state and local taxes, and charitable contributions exceed your standard deduction, file Schedule A. Work with your CPA to confirm this before filing, since the decision affects your after-tax cost of the mortgage.

    7. Time your write-offs carefully. If you are planning to apply for a mortgage in the next 12–24 months, discuss with your CPA whether maximizing write-offs in the current tax year will hurt your qualifying income. Bank statement loans reduce this tension, but conventional and jumbo loans still use tax return income.

    Pro Tip: If you are close to the $750,000 debt limit, consider structuring a purchase with a larger down payment to keep the deductible balance below the cap. That keeps 100% of your interest deductible.

    Key takeaways

    Self-employed borrowers and real estate investors qualify for mortgages by using alternative income documentation, choosing the right loan program, and understanding IRS deduction limits before they apply.

    Point Details
    IRS debt limit is $750,000 Mortgage interest is only deductible on the first $750,000 of debt for loans originated after december 15, 2017.
    Bank statement loans solve the write-off gap Lenders use 12–24 months of deposits instead of tax returns, making write-offs irrelevant to qualification.
    DSCR loans ignore personal income Real estate investors qualify based on rental income alone, with no limit on financed properties.
    Itemizing is required to claim the deduction You must file Schedule A to deduct mortgage interest; over 90% of filers now take the standard deduction instead.
    Shop at least 3–5 lenders No single lender consistently offers the best rate for alternative income borrowers; comparing APRs is non-negotiable.

    What I’ve learned after years of working with high write-off borrowers

    The biggest mistake I see is borrowers treating their tax strategy and their mortgage strategy as two separate conversations. They are not. Your CPA is optimizing for the lowest possible tax bill. That is exactly the right goal for April 15. But that same optimization can make your income look too low for a conventional lender in October when you want to buy a property.

    The fix is not to stop taking write-offs. The fix is to choose a loan program that does not penalize you for them. Bank statement loans and DSCR loans exist precisely because the tax code rewards business owners for reducing taxable income. The mortgage market caught up.

    What I also see is borrowers who assume the mortgage interest deduction is automatic. It is not. You have to itemize, your loan has to be secured by a qualified home, and the proceeds have to have been used to buy or improve that home. A home equity line used to fund a business does not qualify. These details matter, and most borrowers do not find out until they are sitting with their CPA after closing.

    My advice: have the mortgage conversation before you finalize your tax return for the year you plan to buy. One conversation between your CPA and your loan officer can save you from a declined application or a missed deduction worth thousands of dollars.

    — Chris Arco, NMLS #1281

    Specialized loan programs for self-employed borrowers and investors

    Self-employed borrowers and real estate investors have more financing options than most conventional lenders suggest. 1st Nationwide Mortgage is a direct mortgage banker, not a broker, licensed in 18 states with a BBB A+ rating. The programs available include bank statement loans, DSCR loans for investment properties, and mortgage options without tax returns for borrowers with complex income structures.

    https://1stnwm.com

    If you are building a rental portfolio or running a business with significant write-offs, the right loan program changes the entire qualification picture. Explore the full range of loan programs at 1st Nationwide Mortgage or use the mortgage calculators to estimate payments across different loan structures before you apply.

    FAQ

    What is a high write-off mortgage qualification?

    High write-off mortgage qualification is the process of securing a home loan when significant business or tax deductions reduce your reported income below conventional lender thresholds. Alternative programs like bank statement loans and DSCR loans solve this by using actual cash flow or rental income instead of tax return figures.

    Can I still get a mortgage if my tax returns show low income?

    Yes. Bank statement loans use 12–24 months of deposits to calculate qualifying income, bypassing tax returns entirely. DSCR loans for investment properties qualify based on rental income, with no reference to your personal tax return.

    What is the IRS limit on mortgage interest deductions?

    The IRS limits deductible mortgage interest to the first $750,000 of debt for loans originated after december 15, 2017, and $1,000,000 for older debt. Interest on balances above these limits is not deductible.

    Do I need to itemize to claim the mortgage interest deduction?

    Yes. You must file Schedule A on Form 1040 to claim the personal mortgage interest deduction. With the standard deduction now at $30,000 for married filers, you need total itemized deductions above that threshold to benefit.

    Are DSCR loans a good option for real estate investors with write-offs?

    DSCR loans are the strongest option for investors because personal income and tax returns are not part of the qualification. The property’s rental income covers the debt service, and the loan can be held in an LLC with no cap on the number of properties financed.

  • Alternative Income Documentation Mortgage: 2026 Guide

    Alternative Income Documentation Mortgage: 2026 Guide

    An alternative income documentation mortgage is a home loan that uses non-traditional financial records, such as bank statements, profit and loss statements, or 1099 forms, to verify a borrower’s income instead of W-2s and pay stubs. This approach exists because the standard tax return model fails freelancers, self-employed business owners, and real estate investors who write off significant expenses. Fannie Mae guidelines, IRS transcript requirements, and the federal Ability-to-Repay rule all shape how lenders handle these loans. If you earn income outside a traditional paycheck, understanding how alternative income verification works is the first step toward qualifying.

    What counts as alternative income documentation for a mortgage?

    The documents lenders accept as non-traditional income proof fall into several clear categories. Each one tells a different part of your financial story, and lenders typically want more than one type.

    Bank statements are the most common alternative. Lenders review 12 or 24 months of personal or business deposits to calculate average monthly income. The deposit total replaces the adjusted gross income figure on a tax return, which often understates what a self-employed borrower actually earns.

    Hands organizing bank statements for mortgage

    Profit and loss statements prepared by a licensed CPA carry significant weight. They show revenue, expenses, and net income for a defined period. Lenders use them alongside bank statements to confirm that the numbers align.

    IRS tax return transcripts serve as a third-party verification layer. Lenders commonly request current-year profit and loss statements plus recent business bank statements alongside signed personal federal tax returns. The transcript confirms what was actually filed with the IRS, not just what a borrower submits.

    1099 forms document income paid to contractors and consultants. A full two-year history of 1099s, combined with bank records, gives lenders a clear picture of income consistency. Borrowers who qualify for a 1099 mortgage loan skip the tax return requirement entirely under certain non-QM programs.

    Rental income documentation includes executed lease agreements, Schedule E from prior tax returns, and sometimes a current rent roll. Investment property borrowers often pair this with a DSCR analysis.

    • Bank statements (12 or 24 months, personal or business)
    • CPA-prepared profit and loss statements
    • IRS tax return transcripts via Form 4506-C
    • 1099 forms for contractors and freelancers
    • Executed lease agreements and rent rolls for rental income
    • Business licenses and contracts proving active self-employment

    One factor that cuts across all document types is ownership structure. Borrowers who own 25% or more of a business are treated as self-employed under Fannie Mae rules, triggering the full alternative documentation review regardless of how they receive their pay.

    Pro Tip: Ask your CPA to prepare a year-to-date profit and loss statement within 60 days of your application date. Lenders treat statements older than 60 days as stale, which can stall your file.

    Infographic showing mortgage documentation steps

    How do lenders verify self-employed income under current guidelines?

    Lender verification of non-traditional income follows a structured process, not a judgment call. Two frameworks drive most of it: Fannie Mae underwriting guidelines and the federal Ability-to-Repay rule.

    Fannie Mae requires a 2-year history of self-employment income supported by signed personal federal tax returns and business returns when applicable. That two-year window exists to filter out borrowers whose income is new and unproven.

    Income must also pass a continuance test. Qualifying self-employed income must be stable and likely to continue for at least three years after closing. Lenders analyze earnings trends and exclude one-off or declining income sources. A freelance designer who earned $120,000 two years ago but $80,000 last year will face questions about that downward trend.

    The IRS verification step adds another layer. The IRS Income Verification Express Service, accessed through Form 4506-C, lets lenders request tax transcripts directly from the IRS with your signed consent. The IRS only releases transcripts after the borrower approves the request. This step cross-checks the returns you submit against what the IRS has on file.

    Automation has real limits here. Fannie Mae’s Desktop Underwriter can validate self-employed income automatically only for sole proprietors filing Schedule C. Borrowers with S corporations, partnerships, or multi-member LLCs require manual underwriting. That means a human underwriter reviews every page of your tax package.

    “Borrowers with income outside DU automated validation scope often face manual underwriting, making documentation quality the deciding factor.” — Fannie Mae DU Validation guidelines

    The federal Ability-to-Repay rule applies to all loan types, including non-QM products. Lenders must verify income using reliable third-party records. Self-certification alone is not sufficient. Even bank statement loans must satisfy this standard, which is why lenders cross-reference deposits against business records.

    1. Collect two years of signed personal and business tax returns.
    2. Request IRS transcripts using Form 4506-C to confirm filed returns.
    3. Run the file through Desktop Underwriter for automated validation.
    4. Shift to manual underwriting for S corps, partnerships, and LLCs.
    5. Apply the three-year continuance test to all income sources.
    6. Confirm compliance with the Ability-to-Repay rule before approval.

    Pro Tip: If your business structure is anything other than a sole proprietorship, tell your loan officer upfront. It saves two weeks of back-and-forth when the underwriter flags it during review.

    How to prepare and submit your alternative income documentation

    Preparation separates borrowers who close on time from those who spend weeks chasing documents. The process is straightforward when you know what each income type requires.

    Step 1: Identify your income type and match your documents.
    Sole proprietors need two years of personal tax returns with Schedule C. S corporation owners need personal returns plus Form 1120-S. Partners in a partnership need personal returns plus Form 1065. Each structure has its own document set, and mixing them up wastes everyone’s time.

    Step 2: Authorize IRS transcript requests early.
    Sign Form 4506-C as soon as your lender requests it. Form 4506-C errors and mismatches cause delays in transcript delivery and can disrupt your entire mortgage timeline. Verify that your name, Social Security number, address, and tax year entries match your IRS records exactly before signing.

    Step 3: Organize bank statements by account and month.
    Lenders want clean, sequential statements with no missing pages. If you use multiple accounts, label each one clearly. Unexplained large deposits trigger questions, so prepare a brief written explanation for any deposit that looks unusual.

    Step 4: Get your CPA to prepare a current profit and loss statement.
    The statement should cover the current year to date and be signed by your CPA. Lenders treat unsigned or self-prepared P&L statements with skepticism, especially during manual underwriting.

    Step 5: Gather supporting business documents.
    These include your business license, any active client contracts, and a letter from your CPA or attorney confirming your business has been operating for at least two years.

    Common mistakes that delay approval:

    • Submitting unsigned tax returns
    • Missing pages in bank statements
    • Form 4506-C data that does not match IRS records exactly
    • P&L statements older than 60 days
    • Failing to disclose all business entities you own

    When your income pattern looks unusual, write a short letter to the underwriter explaining it. A seasonal contractor whose income spikes in summer and drops in winter should explain that pattern in writing. Underwriters appreciate context. It reduces the number of conditions they issue.

    Working with a mortgage specialist who focuses on self-employed mortgage documentation makes a measurable difference. These specialists know which documents satisfy which guidelines and can flag problems before the file reaches underwriting.

    Which alternative income documentation mortgage fits your situation?

    Different loan products serve different borrower profiles. The table below compares the three most common options.

    Loan type Income documentation Best for Key consideration
    Bank statement loan 12 or 24 months of deposits Self-employed with strong cash flow Higher rates than conventional; no tax returns needed
    1099 loan Two years of 1099 forms Contractors and consultants Income averaged over 24 months
    Conventional loan W-2s, pay stubs, tax returns Salaried employees Lowest rates; strict documentation rules
    DSCR loan Rental income and property cash flow Real estate investors No personal income verification required
    No-income verification loan Asset statements or none High-asset borrowers Highest rates; limited availability

    Non-QM loans use alternative documentation such as bank statements and profit and loss statements instead of traditional tax returns. The Ability-to-Repay rule still applies, but lenders have more flexibility in how they satisfy it.

    Bank statement loans work best for self-employed borrowers who show lower taxable income on returns due to business deductions. A bank statement mortgage uses actual deposits to calculate qualifying income, which often results in a higher loan amount than a conventional loan would allow.

    DSCR loans serve real estate investors who want to qualify based on property cash flow rather than personal income. The lender calculates whether the rental income covers the mortgage payment, and personal income documents are not required.

    1099 loans target contractors and consultants who receive most of their income on 1099 forms. These borrowers often have strong gross income but complex tax situations that make conventional qualification difficult.

    Key takeaways

    Alternative income documentation mortgages qualify borrowers by using bank statements, 1099 forms, profit and loss statements, or rental income records instead of W-2s and pay stubs.

    Point Details
    Two-year income history required Fannie Mae requires two years of self-employment income with signed tax returns or approved alternatives.
    Form 4506-C accuracy is critical Errors on this IRS transcript request form cause delays that can derail your mortgage timeline.
    DU automation has limits Desktop Underwriter validates only Schedule C filers; all other business structures require manual underwriting.
    Income must show continuance Lenders require income to be stable and likely to continue for at least three years after closing.
    Loan type should match income type Bank statement loans, 1099 loans, and DSCR loans each serve a distinct borrower profile.

    What I’ve learned from working with alternative income borrowers

    By Chris Arco, NMLS #1281

    The biggest mistake I see is borrowers treating alternative income documentation as a workaround. It is not. It is a legitimate underwriting path with its own set of rules, and those rules are just as strict as conventional guidelines. Borrowers who approach it casually end up with incomplete files and extended timelines.

    The second mistake is waiting too long to involve a loan officer. I have worked with self-employed borrowers who spent months organizing documents on their own, only to find out they had the wrong tax years or a Form 4506-C that did not match their IRS records. Starting the conversation early gives you time to fix problems before they become deal-breakers.

    One thing that surprises many borrowers: a declining income trend is often more damaging than a lower income level. A borrower earning $90,000 consistently over two years qualifies more easily than one who earned $130,000 and then $85,000. Lenders look at direction, not just totals.

    My practical advice is to work with a lender who specializes in non-traditional income mortgages. Generalist lenders often apply conventional logic to non-QM files, which creates unnecessary friction. Specialists know which documents satisfy which guidelines and can structure your file correctly from the start.

    — Chris Arco, NMLS #1281

    Mortgage programs built for non-traditional income borrowers

    Self-employed borrowers and investors often qualify for more than they expect when they use the right loan program. 1st Nationwide Mortgage specializes in exactly this type of financing.

    https://1stnwm.com

    1st Nationwide Mortgage offers bank statement loans that use 12 or 24 months of deposits to calculate qualifying income, bypassing the tax return requirement entirely. For contractors and consultants, 1099 mortgage options provide a direct path to approval using the income forms you already receive. Real estate investors can qualify through DSCR loan programs based on property cash flow, with no personal income documentation required. Use the bank statement income calculator to estimate your qualifying income before you apply, or contact a loan specialist at 1st Nationwide Mortgage to review your specific situation.

    FAQ

    What is an alternative income documentation mortgage?

    An alternative income documentation mortgage is a home loan that verifies income using non-traditional records such as bank statements, 1099 forms, or profit and loss statements instead of W-2s and tax returns. It is designed for self-employed borrowers, contractors, and investors with non-traditional income sources.

    What documents do self-employed borrowers need for a mortgage?

    Self-employed borrowers typically need two years of signed personal and business tax returns, recent bank statements, a current CPA-prepared profit and loss statement, and a signed Form 4506-C authorizing IRS transcript verification.

    Can I get a mortgage using only bank statements?

    Yes. Bank statement loans use 12 or 24 months of deposit history to calculate qualifying income without requiring tax returns. These are non-QM loans, so rates are typically higher than conventional mortgages, but they are widely available for self-employed borrowers.

    How does the Ability-to-Repay rule affect alternative income loans?

    The Ability-to-Repay rule requires lenders to verify income using reliable third-party records regardless of loan type. Even non-QM bank statement loans must satisfy this standard, meaning self-certification alone is never sufficient for approval.

    Does Fannie Mae accept bank statements as income proof?

    Fannie Mae primarily requires tax returns for self-employed borrowers, but it does allow IRS transcripts and current profit and loss statements as supporting documentation. Bank statement loans that bypass tax returns entirely are typically non-QM products outside Fannie Mae’s standard guidelines.